
Lloyds Bulls Take the Wheel Ahead of May Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
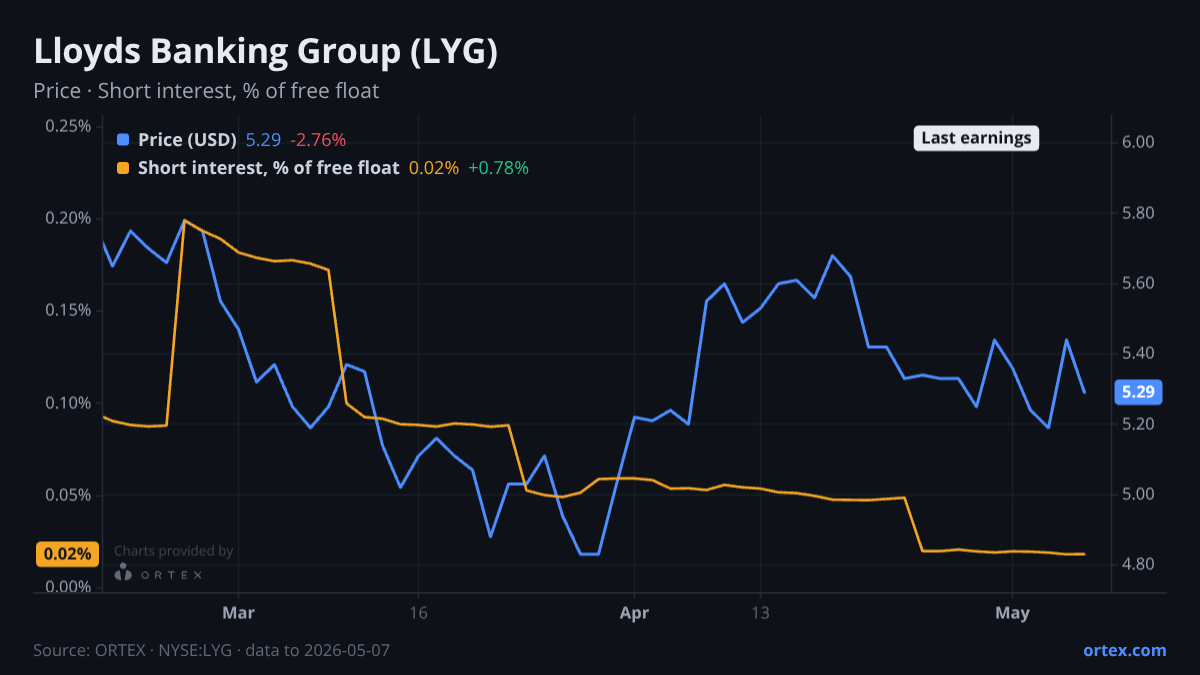
LYG heads into its May 14 interim results with options traders at their most bullish in weeks — a marked contrast to the short-side retreat that has unfolded over the past month.
The dominant signal right now is in the options market. The put/call ratio has dropped to 0.192, nearly three standard deviations below its 20-day average of 0.236 — the most call-skewed reading in the recent period and approaching the 52-week low of 0.076. That signals heavy relative demand for upside exposure heading into the announcement. The shift is recent and sharp: through most of April, the PCR held steadily above 0.24, then broke lower in the first week of May. The stock has kept pace, adding 4.4% over the past month to $5.43, including a 2.6% gain in the final session before the earnings blackout window.
The short-selling community has been stepping back at the same time. Estimated short interest collapsed by roughly 69% over the past month — from around 8.2 million shares in late March to just 2.5 million now — and fell a further 7% in the past week. The borrow market reflects this retreat: cost to borrow has eased to under 0.9%, down more than 38% over 30 days and well off the 2% level seen in early April. Availability remains comfortable, meaning there is no squeeze dynamic in play. The ORTEX short score has drifted down to 35.96 from above 40 earlier in April, consistent with waning short conviction rather than any escalating pressure.
Analyst momentum has tilted constructive ahead of the print. UBS upgraded Lloyds to Buy from Neutral on April 30 — the second major upgrade in under a month, following Citigroup's move to Buy on April 9. Both are bellwether names for UK banking coverage, and both cited the same directional shift to positive. The broader fundamental backdrop offers some support: EPS surprise ranks in the 80th percentile of the ORTEX universe, and the 90-day forward EPS momentum score sits at the 74th percentile, reflecting a pattern of consistent beats. The analyst recommendation divergence score ranks at the 97th percentile — meaning the gap between where analysts are and where the consensus was has rarely been wider, suggesting the upgrades are pulling ratings well above the historical baseline.
The institutional picture adds context. BlackRock holds 9.5% of shares, with Vanguard and FMR (Fidelity) both recently adding exposure. FMR increased its position by 137 million shares in the last reported period, one of the larger recent institutional inflows among the top holders. That flow sits alongside the options and short interest data to paint a consistent picture of reduced hedging and incremental buying ahead of results.
The May 14 print will test whether the earnings delivery — particularly net interest income trajectory and any update on the motor finance provision — can justify a positioning structure that has rapidly moved from sceptical to optimistic.
Against its own history
This week's change in short interest is 3.2 standard deviations above the company's typical weekly move over the past year.
Stocks in this article
See the live data behind this article on ORTEX.
Open LYG on ORTEX →How this article was generated
- Generated
- 11 May 2026, 04:04
- Data as of
- 11 May 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signals
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.