
Pinnacle West Heads Into Q1 Print With Options Skew Near a Year High
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
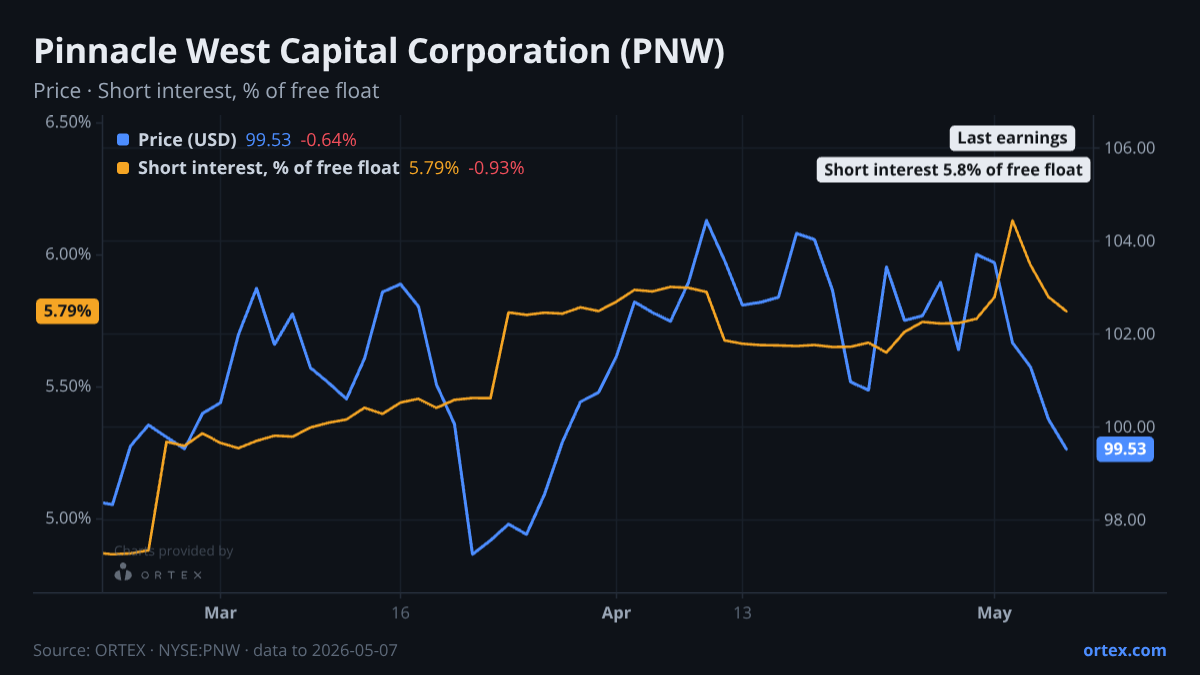
Pinnacle West Capital reports first-quarter results on May 14 with options traders leaning notably more defensive than they have been for most of the past year.
The options signal is the sharpest thing in the setup. The put/call ratio has climbed to 0.70 — nearly two standard deviations above its 20-day average of 0.32 — and is brushing against the 52-week high of 0.71. That level of put demand is unusual for a regulated utility, where options volumes tend to be subdued. The shift began abruptly around May 4, when the PCR nearly doubled overnight from 0.30, and has held elevated since.
That defensive tilt follows a rough week for the stock. PNW fell 4.1% over the past five sessions to close at $99.25, a steeper decline than most of its closest peers. LNT dropped 3.1% over the same stretch, DUK fell 3.4%, and XEL shed 3.9% — so some of the pressure is sector-wide — but AEP and SO both fared worse, down nearly 5% each. PNW is not the weakest link, but it has not found any defensive shelter either.
Short interest adds nuance rather than alarm. At 5.8% of the free float, the short position is meaningful for a utility but has been drifting lower over the past month. It ticked up about 1% over the week, but the lending market gives no sign of pressure: cost to borrow has eased to 0.43% after briefly touching 0.59%, and availability remains well-supplied. The ORTEX short score of 54 is moderate and has slipped back slightly from a five-day high of 56.5 on May 5.
Analyst opinion is cautiously neutral. Most coverage is clustered around Hold-equivalent ratings, with a mean price target near $105 — implying modest upside from current levels. Recent moves have been small and directionally mixed. Barclays nudged its target up to $102 just this week, while Morgan Stanley trimmed slightly to $98 in late April; neither action shifts the narrative materially. The bull case rests on 5.2% retail sales growth, a 2.4% customer expansion, and management's reaffirmed 4–6% long-term sales growth outlook — all pointing to the Arizona service territory's strong population dynamics. Bears focus on a roughly 10% year-on-year earnings decline driven by higher operating costs, and a regulatory overhang from the Arizona Public Service rate case procedural schedule, which has pushed EPS expectations for 2026 and 2027 into negative-revision territory. The EV/EBITDA multiple has compressed about 0.2x over the past 30 days, suggesting the market has already begun discounting some of that pressure.
The May 14 print will test whether the operating-cost drag and rate-case uncertainty are fully priced at $99, or whether the underlying demand story — in one of the fastest-growing utility service territories in the US — warrants a re-rating higher.
Against its own history
This week's change in short interest is 1.9 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved -4.1% over the past week against a median of -3.3% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open PNW on ORTEX →How this article was generated
- Generated
- 11 May 2026, 04:06
- Data as of
- 11 May 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signals
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.