
Options Signal the Bullish Case Into RBC Bearings' May Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
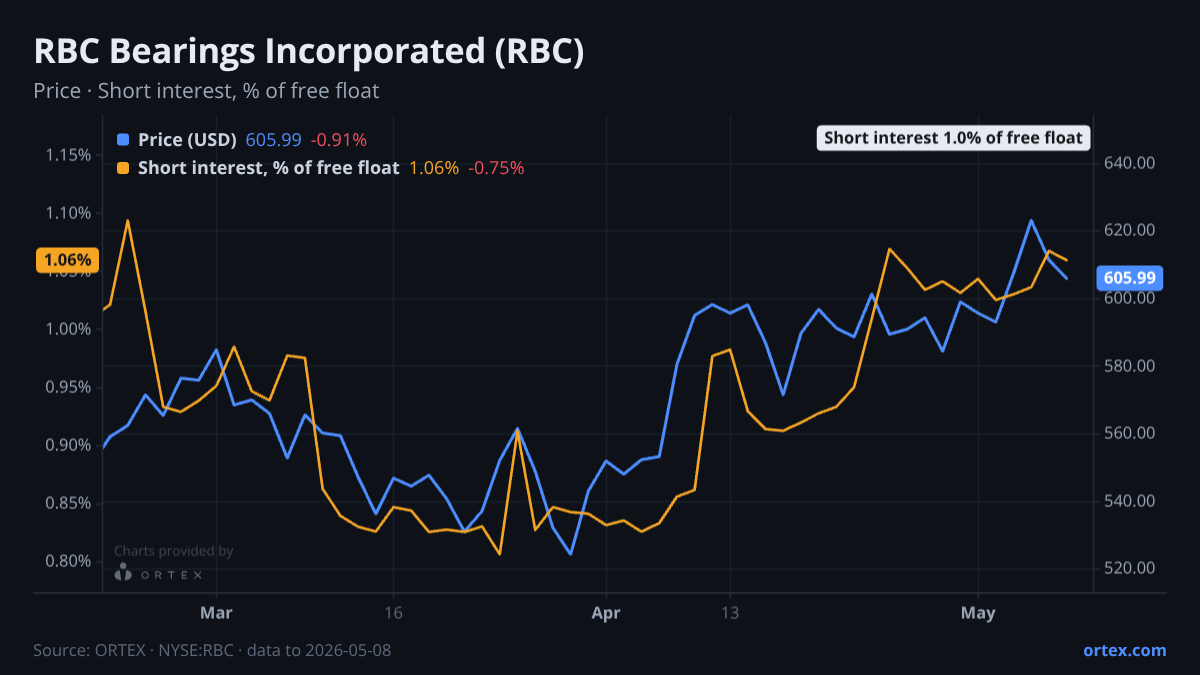
RBC Bearings heads into its May 15 earnings release with options traders showing unusually strong conviction on the upside — a notable tilt given the stock trades at a lofty premium.
The clearest positioning signal is a sharp shift in options sentiment. The put/call ratio has dropped to 0.72, more than two standard deviations below its 20-day average of 0.85 — meaning calls are dominating the options market by the most in months, well below even the 52-week low of 0.22 on a relative basis. That's an unusually bullish lean heading into the print. It follows a solid month for the stock, which has added 2.6% over the past month and 3.5% in the last week, closing at $613.59. Peer performance has been more mixed: TKR gained 6% on the week while OSK fell more than 10%, suggesting sector tailwinds are flowing selectively.
Short interest is too small to drive the story here. At under 1% of the free float, bearish positioning through the lending market is minimal. Cost to borrow has eased roughly 11% over the past week to 0.32%, and availability remains ample — the borrow market offers no meaningful squeeze risk in either direction. The ORTEX short score of 28.6 is consistent with a low-conviction short thesis. What is notable is a 27% rise in short shares over the past month, albeit from a very low base, which bears watching if it continues after the print.
Bulls point to genuine operational momentum. The most recent quarter showed revenue up 7.3% year-over-year to $436 million, with gross margins at 45.4% — among the strongest in the industrial machinery peer group. The backlog reportedly stood at $1.6 billion, up 86% year-over-year. EPS growth of 26% in the prior period beat estimates, and EPS momentum scores rank in the 82nd percentile on a 90-day basis. Keybanc has repeatedly raised its target, most recently to $680 in March, maintaining an Overweight rating. Bears focus on the valuation: RBC trades at roughly 41x trailing earnings and an EV/EBITDA of about 28x, expensive multiples that leave limited margin for disappointment. The bear case also flags guidance risk — revenue guidance falling short of consensus has been a past pattern — and the lingering complexity of integrating the Dodge acquisition. Goldman Sachs maintained a Neutral rating as recently as mid-2025, a position that acknowledged the quality of the business while questioning whether the price already reflects it.
The last two confirmed earnings events produced one-day moves of roughly 5.3–5.4% and five-day moves of 6.2–6.5% on the upside, suggesting the stock has rewarded beats with meaningful rallies. The May 15 print will therefore test whether execution at this margin level — and any revision to full-year guidance — can justify a valuation that has well outpaced even the most bullish analyst targets of a year ago.
Against its own history
This week's change in short interest is 2.9 standard deviations above the company's typical weekly move over the past year.
Against its peers
Shares moved +3.5% over the past week against a median of +2.9% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open RBC on ORTEX →How this article was generated
- Generated
- 12 May 2026, 04:02
- Data as of
- 12 May 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signals
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.