
Guardant Health Shorts Ease Into Q1 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
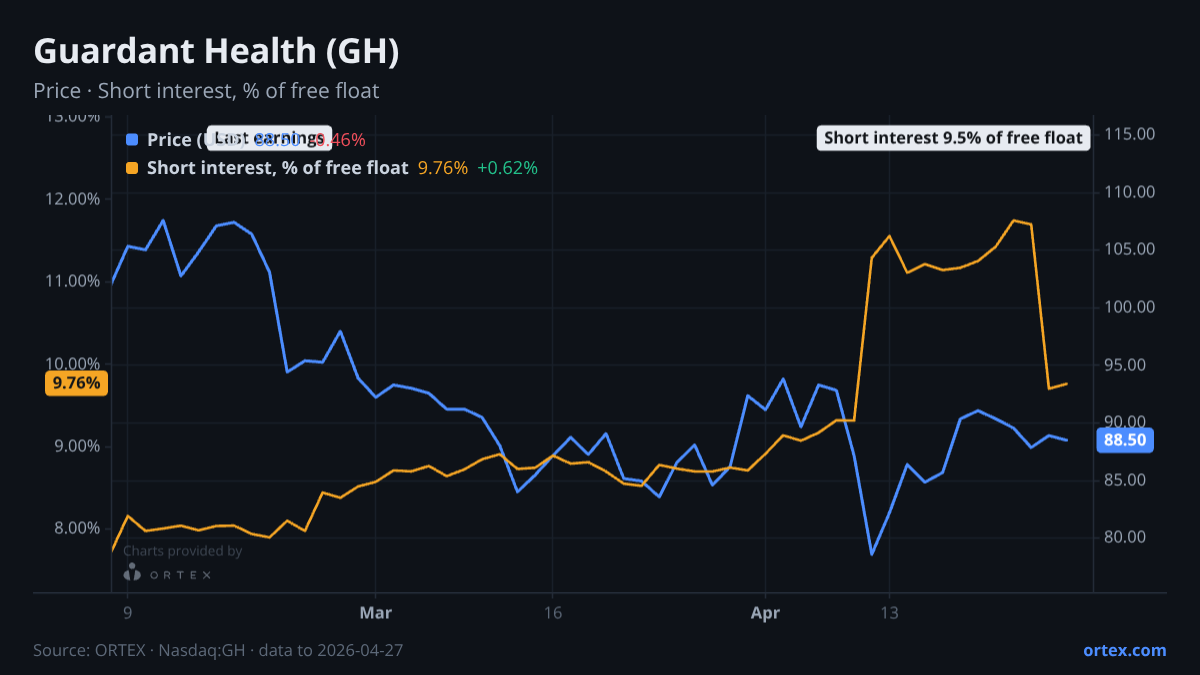
GH heads into its April 30 Q1 earnings release with short sellers retreating sharply — yet the stock keeps falling anyway.
The clearest signal in the data is the divergence between short interest and price. Shorts covered aggressively last week: SI dropped 17% from mid-April highs, falling to 9.5% of the free float from a recent peak near 11.2%. Days to cover stand at roughly four sessions. Yet the stock fell 6% on Tuesday alone and is down 8% on the week to $83.09, underperforming close peers like CSTL (flat on the week) and NEO (up nearly 5%). That combination — short covering without a bounce — suggests the selling is coming from long-side holders reducing exposure, not from bears pressing the thesis.
The borrow market corroborates this reading: the lending environment is not distressed. Cost to borrow has eased nearly 20% over the past week to around 0.43% annualised — barely above the risk-free rate. Borrow availability remains loose at over 1,000%, meaning there are no constraints on fresh short positioning if sentiment sours further. The options market, meanwhile, tells a less defensive story than the price action might suggest. The put/call ratio has actually declined to 1.02, about 1.6 standard deviations below the 20-day average of 1.16. Options traders have been rotating away from protective puts — an unusual configuration given the stock's recent slide.
The fundamental debate centres on a single pivot point: reimbursement. Bulls point to Guardant's commanding 50%-plus share in liquid biopsy genomic profiling, 30% year-on-year volume growth in that segment, and an EPS surprise track record ranking in the 92nd percentile. Forward EPS growth expectations also rank in the 83rd percentile year-on-year — unusually optimistic for a company still running negative EBITDA. Bears counter with a more structural concern: PAMA regulations could trigger a roughly $100 million one-time revenue reduction, while reimbursement uncertainty around multi-cancer early detection tests clouds the medium-term commercial path. Recent analyst moves have been asymmetrically cautious — Barclays and Evercore both trimmed targets in April (to $115 and $90 respectively), while the last set of raises came in February post the prior quarter's print. The consensus remains Buy with 16 buy ratings and a mean target implying roughly 45% upside from current levels, but the Street has been walking that target down.
The Q1 print is therefore less about whether volume growth continues and more about whether Guardant can demonstrate a credible path through the reimbursement headwinds — at a price that no longer reflects the optimism of two months ago.
Against its own history
This week's change in short interest is 2.6 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved -8.0% over the past week against a median of -3.0% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open GH on ORTEX →How this article was generated
- Generated
- 29 Apr 2026, 04:44
- Data as of
- 29 Apr 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signals
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.