
PBH Insiders Sell Into Earnings as Short Sellers Circle
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
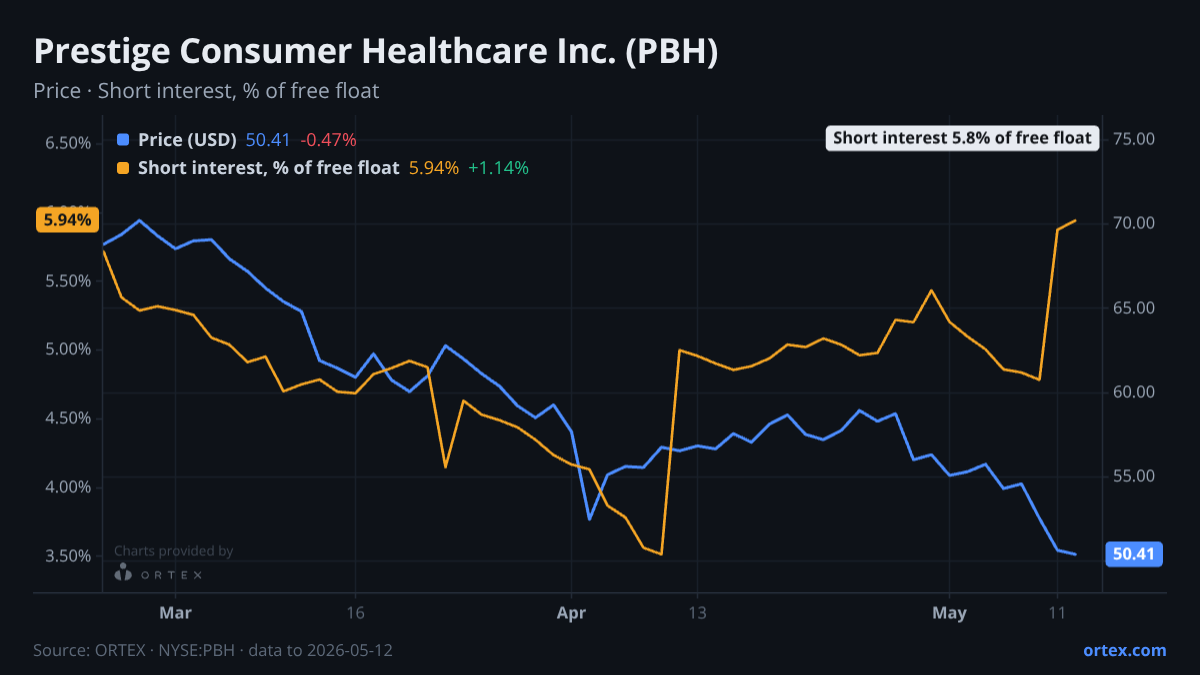
PBH reports its Q4 2026 results on May 14 with an unusual cluster of executive selling pressure competing against the most aggressive short-interest build in months.
The most striking signal into today's print is the insider activity. CEO Ron Lombardi and CFO Christine Sacco both sold shares on May 5 and May 7 — just days before the earnings release. Lombardi disposed of a combined $261,000 worth of stock across the two sessions. Sacco sold roughly $125,000. An SVP added further sales on May 5, 7, and 11. This isn't noise: multiple C-suite names selling in the week before results is the kind of coordination that tends to attract attention, even when the volumes are individually modest.
Short sellers have been building alongside that insider activity. Short interest climbed 53% over the past month to reach 5.8% of the free float — a meaningful acceleration from the ~3.5% level seen at the start of April. The weekly jump alone is 16%. Borrowing costs remain low at just 0.50%, and availability is comfortable, so this isn't a technically squeezed position — it's a deliberate directional bet. Days to cover are running at 6.3, adding some friction for any rapid unwind.
Options positioning, however, reads differently. The put/call ratio has dropped to 0.63 — well below its 20-day average of 0.81 and sitting 1.3 standard deviations below the mean. That tilts toward call demand rather than hedging, a signal that some options traders are positioned for upside rather than protection. The stock itself is down 8.4% on the month and 4.6% on the week, closing at $51.81 on Wednesday. The RSI has fallen to an oversold 27.4, and the stock is roughly 18% lower year-to-date. Price weakness has compressed valuation: the PE multiple now sits near 10.3x, and EV/EBITDA at 8.3x — both pulled down materially over the past 30 days.
The analyst picture has been uniformly downward. Every recent target revision has been a cut: Oppenheimer lowered to $65 from $77 on May 7 while keeping its Outperform rating. The consensus remains at six buys and no sells, with analyst-implied upside of roughly 52% from current levels. Bulls are focused on expected organic volume growth, new product launches, and potential EBITDA margin expansion from easing input costs. Bears point to below-trend revenue growth, ongoing margin pressure, and the risk that the company's largest customer relationships continue to drag on operating performance.
Today's print tests whether the sharp valuation reset and the month of insider selling are leading indicators of a guidance cut — or whether the oversold RSI and bullish options positioning are closer to the truth.
Against its own history
This week's change in short interest is 1.9 standard deviations above the company's typical weekly move over the past year. Short interest is at its highest level in at least a year.
Against its peers
Shares moved -4.6% over the past week against a median of -0.7% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open PBH on ORTEX →How this article was generated
- Generated
- 14 May 2026, 04:12
- Data as of
- 14 May 2026, 03:50
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signals
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.