
NBIX Faces Q1 Print with Bears Building Ahead of Crenessity Verdict
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
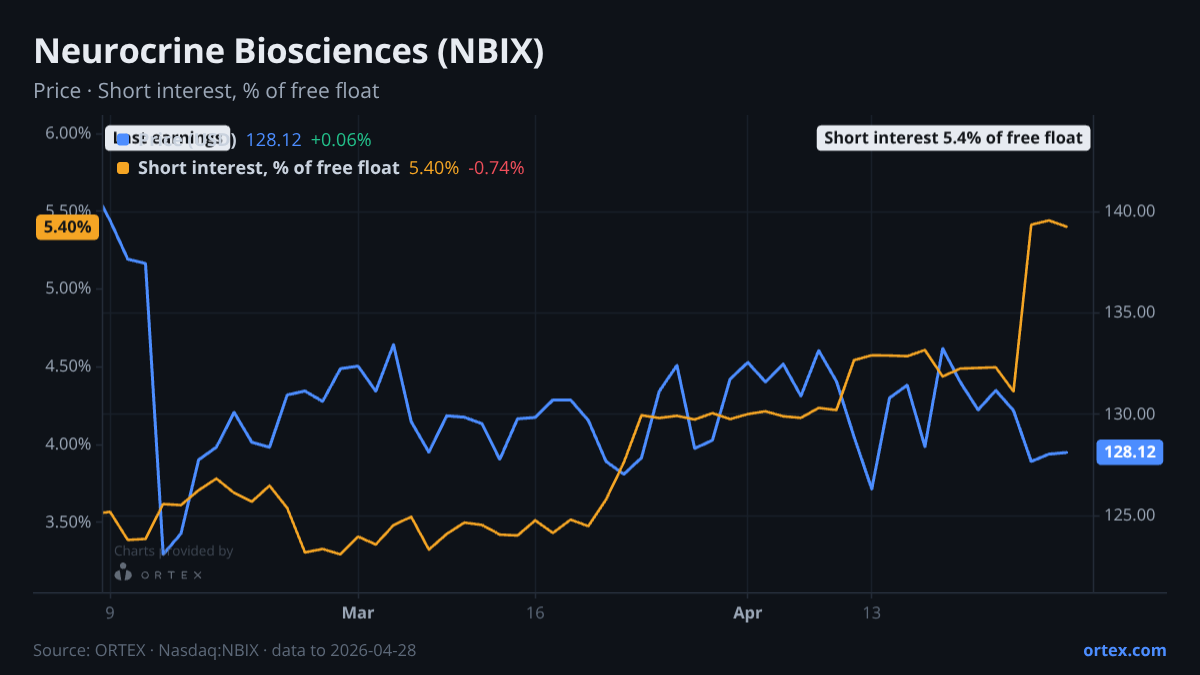
Neurocrine Biosciences heads into its May 1 Q1 results with short sellers meaningfully more aggressive than they were just a month ago — and options traders turning cautious on the day before the release.
The short interest buildup is the clearest signal. At 5.4% of the free float as of April 28, short interest is up 20% on the week and nearly 40% over the past month — a rapid accumulation that stands out even by biotech standards. Despite the climb, the borrow market remains relaxed: cost to borrow is just 0.32% APR, down sharply over the week, and availability is ample relative to the lending pool. That combination — rising short positions alongside easy and cheap borrowing — points to deliberate directional bets rather than any technical squeeze dynamic. The short score at 41.7 has ticked up over the past week, consistent with the buildup. Meanwhile, the stock itself has barely moved: NBIX closed at $131.23 on April 29, roughly flat on the week and up only 2% on the month. Options positioning turned notably more defensive on April 29 specifically, with the put/call ratio jumping to 1.49 from around 0.98 the prior session — though that reading remains below the 52-week high of 1.76 and only 0.77 standard deviations above the 20-day average of 1.28.
The bull-bear debate centres tightly on Crenessity. Bulls point to the drug's commercial infrastructure, Neurocrine's strong payer relationships, and expectations that the recent acquisition becomes accretive by FY26. EPS momentum ranks in the 92nd percentile on a 30-day basis and 79th on 90 days — forward estimates have been moving higher. Analysts have broadly ratcheted up price targets following the February earnings miss, with multiple firms raising targets in early April: Citigroup lifted to $242, Canaccord to $200, and Morgan Stanley to $185 while keeping an Equal-Weight rating — a split that captures the Street's uncertainty. The consensus mean target of $185.65 implies roughly 41% upside to the current price. Bears, however, focus on Crenessity's inconsistent sales trajectory, ongoing competitive pressure, and rising R&D costs that have already forced a trimmed financial outlook. The February print dropped the stock 10.6% in a single session, with an additional 6.7% lost over the following five days — the market has punished misses sharply here before.
Institutional ownership is stable and concentrated. BlackRock holds 12.8% and Vanguard 9.6%, both adding modestly in Q1. JP Morgan Asset Management added nearly 390,000 shares in the quarter, a more notable incremental commitment. Insider activity from February was largely routine — awards offset by concurrent sells following vest events — with no directional signal in either direction.
The earnings report will therefore test whether Crenessity's launch trajectory has inflected, and whether rising operational expenditure is tracking toward the accretion timeline the bulls are pricing in.
Against its own history
This week's change in short interest is 2.4 standard deviations above the company's typical weekly move over the past year. Short interest is at its highest level in at least a year.
Against its peers
Shares moved +0.0% over the past week against a median of -1.9% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open NBIX on ORTEX →How this article was generated
- Generated
- 30 Apr 2026, 04:24
- Data as of
- 30 Apr 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signals
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.