
Analysts Lift Targets as Wyndham Heads Into Q1
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
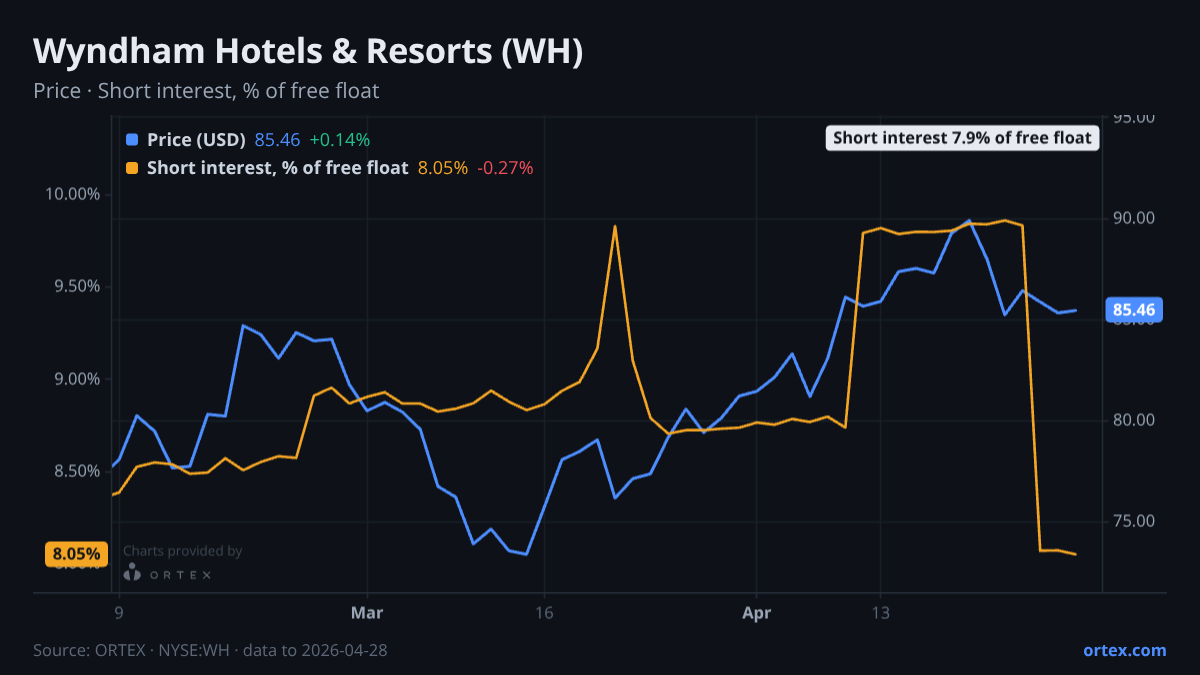
Wyndham Hotels & Resorts reports first-quarter results on April 30 with the Street firmly in its corner — but options traders telling a very different story.
The analyst setup is unusually bullish heading into the print. JP Morgan, Barclays, and Truist all raised price targets in the past three weeks, maintaining positive ratings. The consensus mean target is $99.82 against a current price of $84.09 — implying roughly 19% upside. Morgan Stanley also lifted its target to $87 earlier in April after a brief trim in March. The direction of travel is clear: the Street has been building conviction, not trimming it.
Options positioning cuts against that constructive tone. The put/call ratio dropped sharply to 0.83 on April 29 — nearly four standard deviations below its 20-day average of 1.46. That is the most call-heavy reading in recent memory, well below the 52-week low of 0.20 as a reference point, and suggests traders rotated aggressively into calls ahead of today's release. Whether that reflects genuine bullish conviction or short-term positioning is the open question.
Short sellers have been retreating. SI fell 18% over the past week to 7.9% of the free float — a meaningful pullback from the mid-April peak near 9.7%. The lending market backs that up: borrow availability is ample and cost to borrow has eased 15% on the week to just 0.43% annualised. The ORTEX short score dropped from around 52 to 47 after April 23, tracking the sharp reduction in borrowed shares. Bears are not pressing here.
The bull case rests on room-count expansion and geographic diversification — 6% RevPAR growth in EMEA and 25% in Latin America standing out against domestic softness. Bears point to Adjusted EBITDA growth guidance of 5%-7%, below the prior 8.5% CAGR target, and a 2.9% RevPAR decline in March. Peers HLT and MAR fell roughly 5% on the week, while WH lost only 1.3% — a relative resilience that itself becomes a point of debate about whether the valuation gap is justified. The last earnings print produced a 1.8% one-day drop, reversing an earlier positive reaction; the Q1 release will test whether the recent analyst optimism and call-buyer conviction align with what management actually delivers on RevPAR trends and the full-year EBITDA trajectory.
Against its own history
This week's change in short interest is 2.1 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved -1.3% over the past week against a median of -4.7% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open WH on ORTEX →How this article was generated
- Generated
- 30 Apr 2026, 04:43
- Data as of
- 30 Apr 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signals
- Validation notes
- soft: missing section mentions: short interest (informational only)
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.