
SMMT CEO Buys Ahead of Today's Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
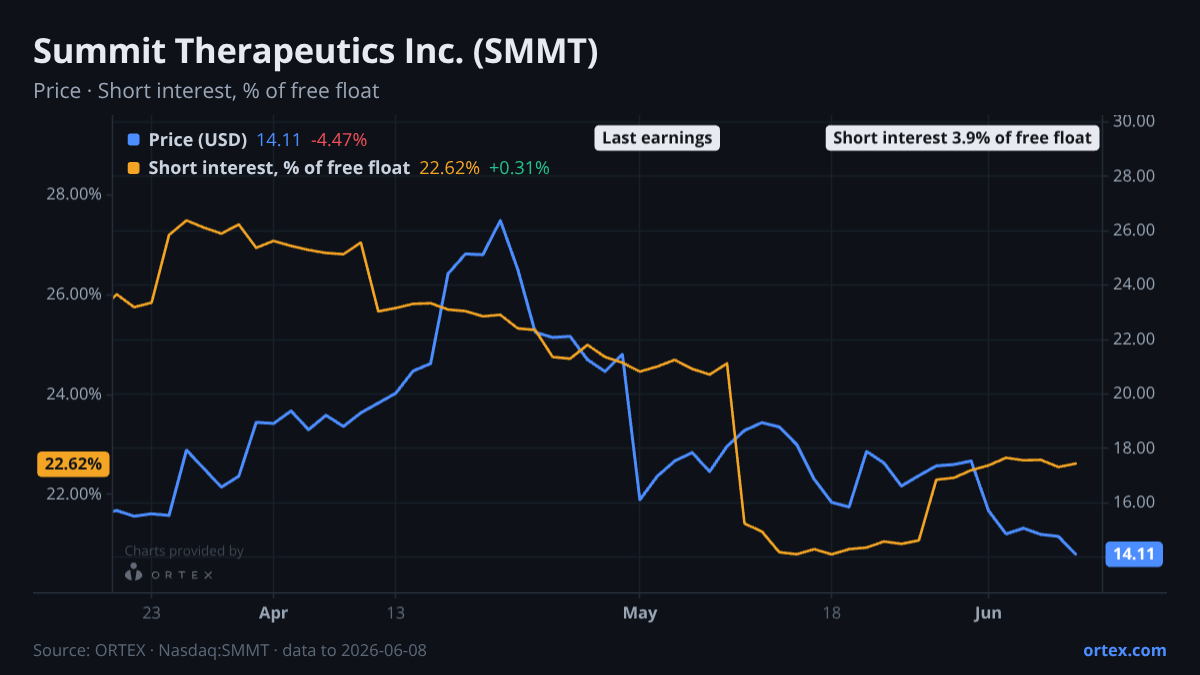
Summit Therapeutics heads into its June 10 earnings report with its own executives making a conspicuous case for the stock just days before the release.
On June 4, CEO Maky Zanganeh purchased 100,000 shares at $14.60 — a $1.46 million buy — while CFO Manmeet Soni added 50,000 shares across two tranches at roughly the same price, committing around $720,000. Together, that's over $2.18 million in net insider buying in a single session, just six days before the print. The timing is notable: the stock had already shed 21% over the prior month, and the insiders stepped in near what appears to be a deliberate accumulation level rather than a routine grant-related purchase.
The analyst community is far less unified. Bernstein initiated coverage on May 22 with an Underperform and a $7.70 target — barely half the current $14.29 price — citing concern over delayed HARMONi-2 overall survival disclosure and competitive pressure from Merck's immunotherapy data. That same day, HC Wainwright downgraded to Neutral from Buy. Both moves came within the past three weeks and represent a meaningful shift in tone from a firm that had previously been one of Summit's most consistent bulls. On the other side, Stifel initiated in April with a Buy and a $45 target, and a handful of holders maintain price targets well above $20. The mean consensus target runs at $21.27, implying over 40% upside from current levels — but the distribution underneath that average is unusually wide, reflecting genuine disagreement rather than a consensus with minor dispersion.
The bear case centres on one question: when, and at what level, will ivonescimab's overall survival data arrive, and whether it can hold up against Merck's updated pembrolizumab profile. Bulls point to the 80% estimated approval probability in non-small cell lung cancer and meaningful trial probabilities across additional indications including triple-negative breast cancer and colorectal cancer. The ORTEX short score, at 74.8, remains elevated even as it has eased modestly over the past two weeks from a peak near 77.4 — signalling that short-side conviction is high but no longer accelerating. Short interest at 3.9% of free float is moderate rather than extreme, and borrowing costs have eased to around 0.73% with availability loosening sharply to 107%, so the lending market is not signalling an imminent squeeze.
Past earnings reactions at Summit have been dramatic in both directions: the May 4 print produced a one-day gain of nearly 9% and a five-day follow-through of almost 16%, while an April 30 event delivered a single-day drop of 23%. The print arriving today will test whether the insider buying cluster at $14-$15 reflects informed confidence in the data pipeline — or simply a floor that the market has yet to decide it agrees with.
Against its own history
This week's change in short interest is 3.3 standard deviations above the company's typical weekly move over the past year.
Against its peers
Shares moved -3.8% over the past week against a median of -0.9% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open SMMT on ORTEX →How this article was generated
- Generated
- 10 Jun 2026, 04:07
- Data as of
- 10 Jun 2026, 04:02
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.