
CMG Put-Call Ratio Hits 52-Week High as Bears Pile In
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
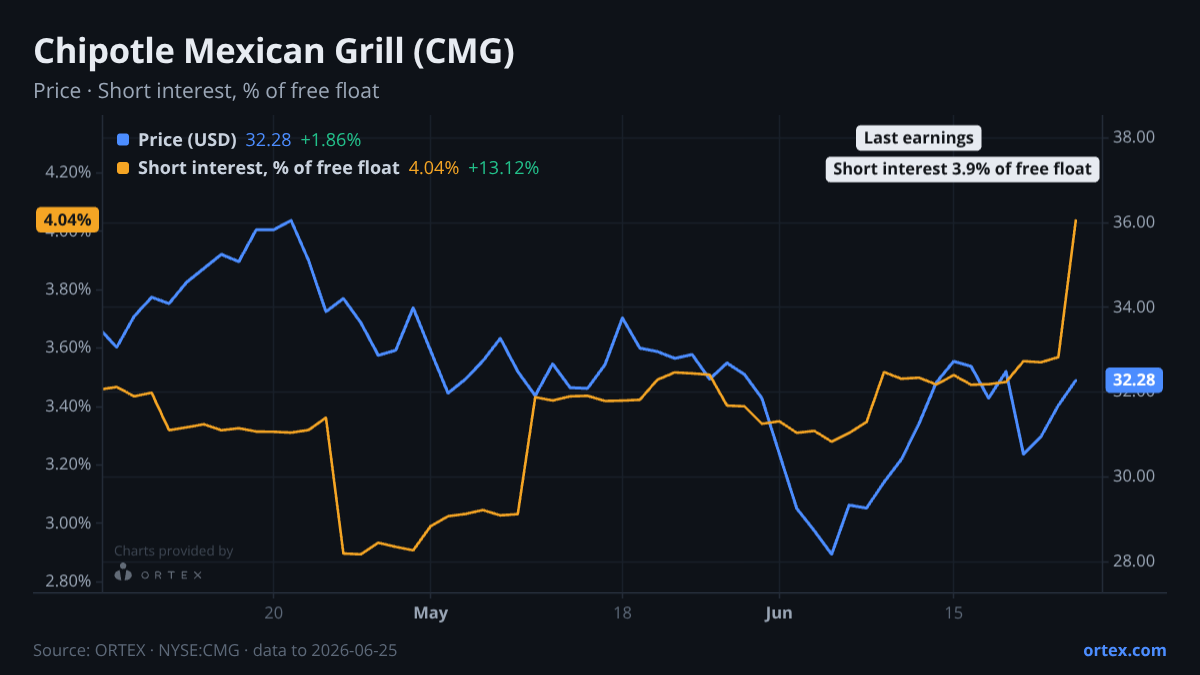
Options traders have turned sharply defensive on CMG. The put-call ratio hit 1.296 on June 25 — just shy of the 52-week high of 1.302 set the day before. That reading sits 2.2 standard deviations above the 20-day mean of 1.09. Analysts are cutting targets too. The signals are stacking up.
Options Market Flashes Bearish
The put-call ratio has climbed steadily since mid-May. It was 0.93 on May 19. By June 24 it reached 1.302 — the highest in a year. Demand for downside protection is at its most elevated level in at least 12 months. The 20-day mean is 1.09, and the current level is firmly in extreme territory by statistical measure.
The shift has been consistent, not a single-day spike. Six consecutive sessions above 1.18 suggest sustained hedging demand rather than a one-off event.
Analysts Have Been Pulling Back
Recent analyst moves reinforce the cautious tone. Morgan Stanley's Brian Harbour downgraded CMG to Equal-Weight from Overweight on June 3, slashing the price target from $49 to $37. JP Morgan's John Ivankoe followed on June 5, upgrading to Overweight but simultaneously cutting the target from $38 to $35.
The stock trades at $32.28. Most targets on the table — $35 to $46 — still sit above current levels. But the direction of travel on targets is clearly downward.
Shorts Build Quietly, Borrow Stays Loose
Short interest rose 13.1% on June 25 alone, reaching 3.9% of free float. The one-week increase is 16.1%. That is a notable acceleration in positioning.
The borrow market tells a different story, however. Availability stands at 8,591% of estimated short interest. That is an extremely loose lending pool — roughly 86 shares available for every one already borrowed. Cost to borrow has collapsed to 0.094%, down 75% over the past week. Shorts building here face no friction in finding shares to borrow.
At 3.9% of float, the absolute short interest level is not extreme. But the pace of increase — from around 4.2% in early May to the current level — alongside options positioning signals growing institutional skepticism.
Earnings Approach on July 24
The next earnings date is July 24. That context matters. Put-call ratios near 52-week extremes ahead of earnings often reflect hedging activity rather than pure directional conviction. The bull case centres on improving same-store sales and pricing power. The bear case flags weak comps and margin pressure.
The convergence of elevated put buying, analyst target cuts, and rising short interest heading into a catalyst date is worth tracking.
- PCR: 1.296, 52-week high 1.302, 20-day mean 1.09, z-score 2.16
- SI % of FF: 3.9%, up 16% over one week
- Availability: 8,591% — extremely loose borrow market
- Cost to borrow: 0.094%, down 75% in one week
- Next earnings: July 24, 2026
Against its own history
Short interest is at its highest level in at least a year.
Against its peers
Shares moved -0.6% over the past week against a median of +2.6% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open CMG on ORTEX →How this article was generated
- Generated
- 26 Jun 2026, 13:19
- Data as of
- 26 Jun 2026, 13:08
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.