
ARM: Calls Rule as Bears Keep Covering
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
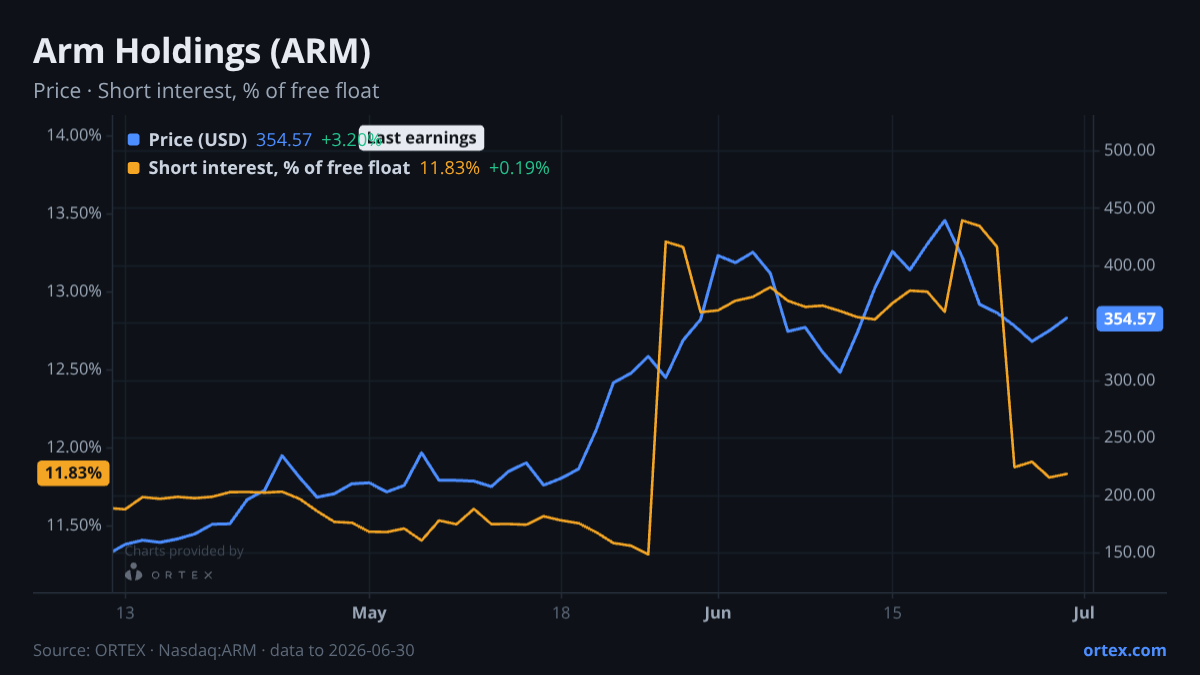
Why this matters: Three distinct signals are aligning on ARM in the same direction. Short sellers are reducing exposure. Call buyers are dominant in the options market. Borrow costs are rising even as the lending pool stays well-supplied. The setup is unusual — and it arrives four weeks before July 29 earnings.
Short Sellers Keep Retreating
The short-covering that began in late June has continued. Short interest fell another 12% in the week to June 30, dropping to 16.9 million shares. That follows the 2.2-million-share cover reported in the previous ORTEX note. Since the peak above 19.2 million in mid-June, roughly 2.3 million additional shares have been covered.
The borrow market tells a consistent story. Availability stands at 196% — roughly two shares available for every one currently borrowed. That is ample supply. Yet cost to borrow has still jumped 67% over the past week to 0.82%. The rate remains low in absolute terms. But a sharp CTB move into a well-supplied pool suggests incremental demand for borrows, even as headline short interest falls. New shorts are initiating while older positions close.
Options Market Tilts Toward Bulls
The put-call ratio on ARM sat at 1.20 on July 1. That looks elevated in isolation, but it is 1.6 standard deviations below its 20-day mean of 1.24. Put options are cheap relative to calls by recent standards. Call demand has been the dominant driver.
The 52-week PCR range runs from 0.78 to 1.35. The current reading is in the lower third of that range. Traders positioning through options are leaning bullish — or at minimum, they are not paying up for downside protection.
Street Stays Constructive Despite the Pullback
ARM is down 6% over the past week and 4.8% on the latest session, trading at $337.47. The stock has now given back most of the move from $334 that followed the initial post-selloff bounce.
The analyst backdrop has not shifted. TD Cowen raised its target to $475, UBS to $470, and BofA to $460 — all in the week of June 24, all into the weakness. The consensus mean of $297 lags those fresh targets significantly. At $337, ARM now trades above the consensus mean but well below the most active recent target levels. The lone downgrade — New Street Research to Neutral on June 18 — remains the only dissenting voice at the top of the house.
The bull case centres on a 20% royalty revenue CAGR through 2031 and a $15 billion CPU revenue opportunity by fiscal 2031. The bear case flags SoftBank dependency and the risk that rising royalty rates alienate existing customers.
Data Summary
- Short interest: 16.9M shares as of June 30; down 12% week-on-week, up 7% over 30 days
- Cost to borrow: 0.82%, up 67% week-on-week; level classified as low
- Availability: 196% — tight end of the normal range, down 9% week-on-week
- Put-call ratio: 1.20 on July 1; -1.6 standard deviations vs. 20-day mean of 1.24
- Price: $337.47, down 4.8% on the day, down 6% on the week
- Next earnings: July 29, 2026
Against its peers
Shares moved -6.0% over the past week against a median of -0.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open ARM on ORTEX →How this article was generated
- Generated
- 2 Jul 2026, 06:08
- Data as of
- 2 Jul 2026, 06:04
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.