
KLAC: Options Bears Dig In as Analysts Diverge Before Earnings
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
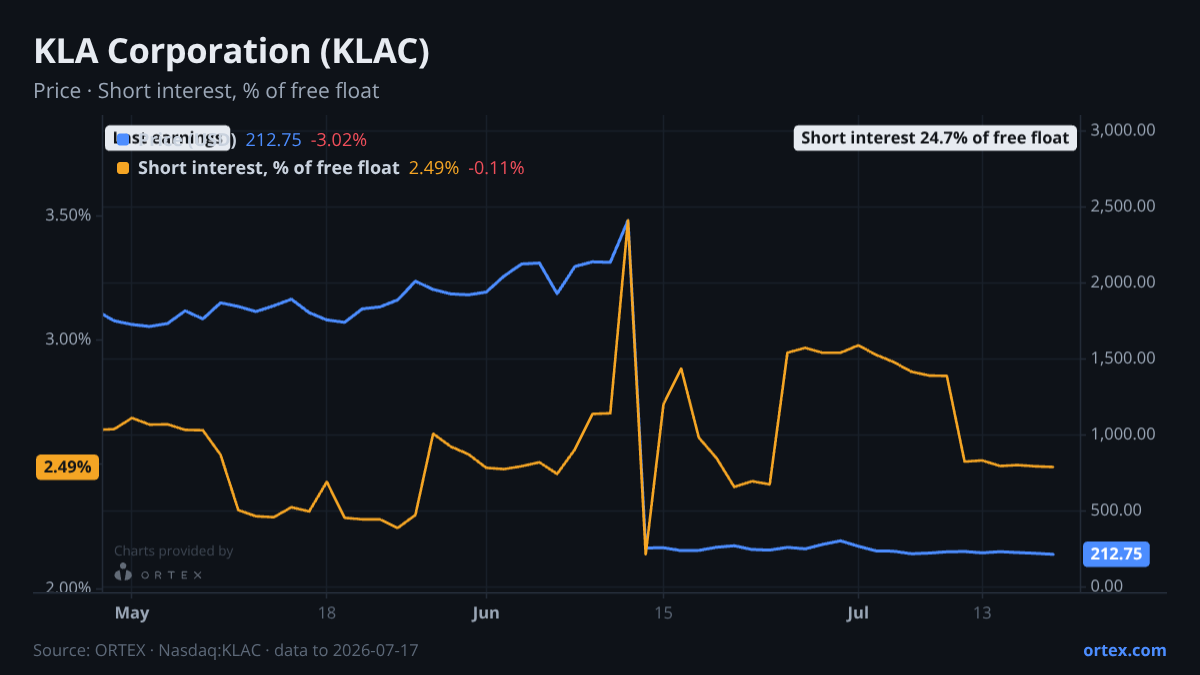
KLA Corporation reports on July 28. Since the last note six days ago, the options market has turned decisively more defensive — and the analyst consensus has fractured in an unusual way.
PCR Hits a Three-Week High
The put-call ratio has moved from 1.46 on July 20 to 1.60 today. That's a z-score of 3.23 against the 20-day mean of 1.36. In plain terms, options buyers are paying up for downside protection at the fastest pace in weeks. The stock is down 20% over the past month and off a further 6.6% this week. Some of that defensive positioning reflects the price action; some of it may be pre-earnings hedging from holders who want to keep their shares but cap the risk.
Analysts Split on the Same Day
The analyst picture has sharpened since the last article. On July 20 — the same day the PCR spiked — UBS analyst Timothy Arcuri cut his price target to $240 from $255. That reverses his own raise just five days earlier (he took it from $218 to $255 on July 15). Arcuri maintains a Neutral rating throughout.
That sits uncomfortably alongside the bullish cluster from earlier this month. Morgan Stanley raised to $274 on July 6. Stifel and Needham both raised to $270 on July 10. Oppenheimer raised to $260 on July 16. The consensus target sits at $234 — still 13% above today's $207.60 close. The UBS reversal stands out precisely because it came after the stock's sharp drop, while the others preceded it.
Short Covering Continues, Cost to Borrow Ticks Up
Short interest has held steady at roughly 24.7% of free float, down from ~29% at the start of the month. The covering that drove that move has not resumed at pace — daily changes since July 10 have been minimal. Borrow availability remains extraordinarily loose at around 9,500%. That is unchanged in character from the prior note; bears who want to rebuild positions face no borrowing constraint.
Cost to borrow did jump 71% over the past week to 0.59%. That sounds dramatic, but the absolute level remains trivial. At 0.59%, shorting KLAC costs less than one percent per year to carry. This is not a borrow-squeeze story.
Insider Sales Add Context
Executives sold aggressively in late June and early July. The CFO Bren Higgins sold over $15.8M across two transactions on June 30 and July 2. CEO Richard Wallace sold $12.8M on June 30 alone, after selling ~$10M on June 11. These were at prices of $265–$285 — well above today's $207.60. The sales were pre-scheduled in pattern, but the volume and proximity to earnings is notable context.
Peers are broadly weaker. AMAT fell 8.6% this week. LRCX dropped 7%. ONTO fell 8.4%. The selloff in semiconductor equipment is sector-wide.
What to Watch
July 28 is seven days away. The setup is: heavy put buying, a fractured analyst view, continued (if slowing) short covering, and a stock trading 13% below the consensus target. Whether the options market is right to hedge this aggressively becomes clear next Monday evening.
Against its peers
Shares moved -6.6% over the past week against a median of -7.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open KLAC on ORTEX →How this article was generated
- Generated
- 21 Jul 2026, 11:07
- Data as of
- 21 Jul 2026, 11:03
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.