
DexCom Options Flash Rare Defensive Signal Ahead of Q2 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
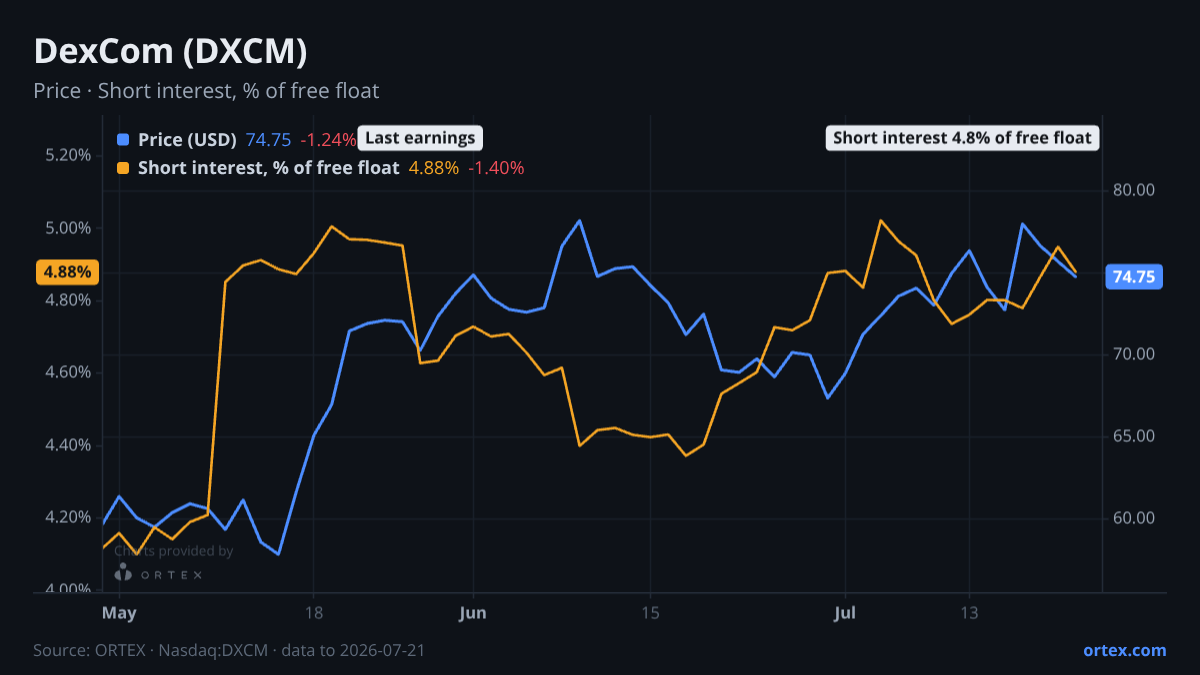
DXCM heads into tonight's Q2 earnings report with options traders flashing their most defensive positioning in nearly a year.
The put/call ratio has climbed to 1.00, more than two standard deviations above its 20-day average of 0.81 — a reading that ranks close to the 52-week high of 1.06. That level of put demand is unusual for DXCM and points to concentrated hedging activity rather than routine pre-earnings caution. The stock has added to the defensive mood with a 4.4% drop on Wednesday alone, leaving it at $71.43 — down roughly 1.8% on the week and 1.4% on the month. Most correlated peers also fell Wednesday, but DXCM's move was sharper: PODD dropped 2.9% and ISRG fell 2.7%, while STE and EW held near flat.
The borrow market tells a much calmer story. Availability is extremely loose at roughly 1,715% — meaning shares available to borrow dwarf the current short position by a wide margin. Borrowing costs have eased sharply, dropping more than 22% over the past week to just 0.47%. Short interest has crept up about 10% over the past month to 4.8% of the free float, but at that level it reflects a measured bearish bet rather than a high-conviction short thesis. The lending conditions offer no squeeze pressure whatsoever.
The analyst debate is squarely about the pace and durability of DexCom's expansion beyond Type 1 diabetes. Bulls point to the company's leadership in CGM technology, meaningful upside from broader coverage of non-intensive Type 2 patients, and a consensus price target of $85.75 — roughly 20% above Wednesday's close. Truist raised its target to $87 just last week, and Mizuho followed earlier in the month at $90, both maintaining positive ratings. Bears flag pricing pressure from payors, competition in the diabetes device sector, and the risk that slower adoption of 15-day sensors and GLP-1 drug tailwinds reduce device demand. The CFO joined a cluster of insiders selling shares in recent months — the Executive Chairman alone sold close to $4 million worth across two July transactions — though these appear to be scheduled disposals rather than a directional call on the business.
The print will test whether DexCom's volume growth in Type 2 is tracking ahead of consensus expectations and whether management's guidance is enough to justify a valuation — currently 26x trailing earnings — that demands visible execution on the expansion story.
Against its peers
Shares moved -1.8% over the past week against a median of -1.3% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open DXCM on ORTEX →How this article was generated
- Generated
- 23 Jul 2026, 04:25
- Data as of
- 23 Jul 2026, 04:10
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.