
Masco Shorts Retreat Ahead of Q2 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
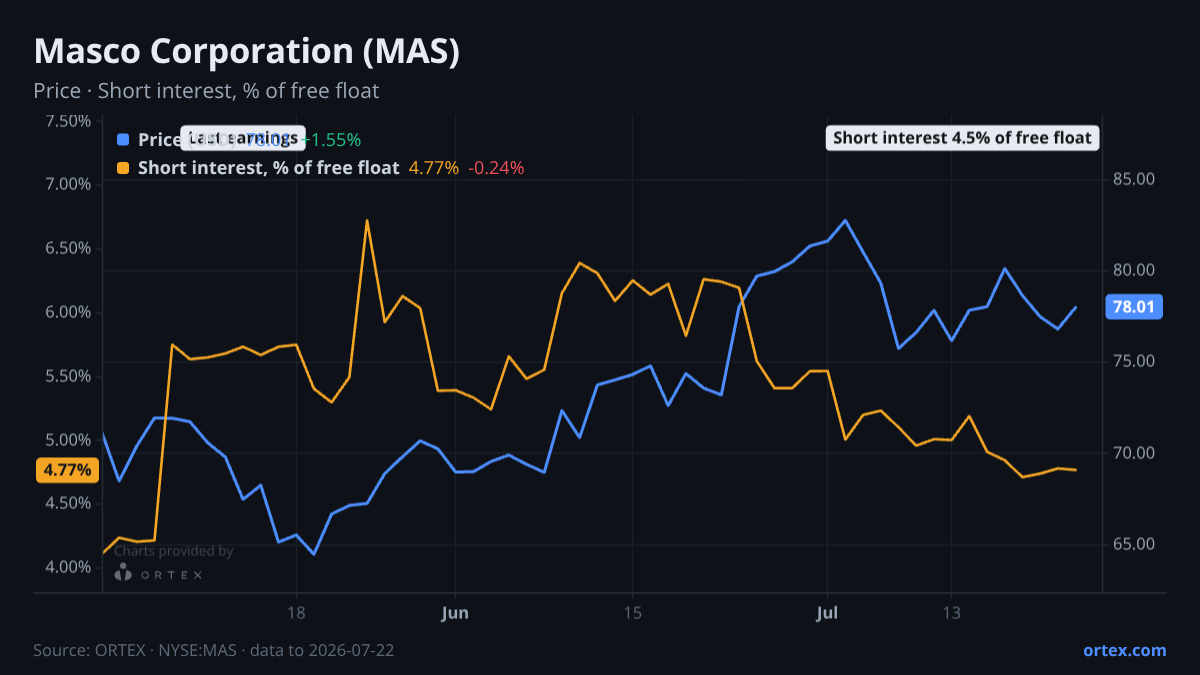
MAS heads into its July 27 earnings report with bears in full retreat — short sellers have cut positions sharply — yet analysts remain split on whether the underlying business can justify the stock's recent recovery.
The bear capitulation is the most striking feature of the pre-earnings setup. Short interest has fallen 22% over the past month to 4.5% of the free float, with the bulk of that decline concentrated in the last week — an 8% single-week drop. That covers roughly 9.4 million shares, down from nearly 12.5 million in mid-June. The lending market corroborates the retreat: availability is generous at roughly ten-times the shares currently borrowed, and cost to borrow is a negligible 0.48%, making a short position in MAS essentially free to carry. Options traders, meanwhile, are showing no particular anxiety — the put/call ratio of 0.46 is barely above its 20-day average and well off the high of 2.06 seen during the past year's most defensive readings. The stock itself is down 3.5% on the week to $77.34, slightly underperforming close peers SSD and ZWS, which each fell under 2.5%, while BLDR fared worse at nearly 10% down.
Analysts are cautiously constructive but far from enthusiastic. Wells Fargo and Barclays both raised targets in the past ten days — Wells to $87, Barclays to $82 — while keeping existing ratings intact, an "improving but not upgrading" posture that captures the Street's mood. The consensus mean target of $81.82 leaves only modest upside from current levels. Bulls point to Masco's entrenched brand position in plumbing and decorative architectural products, its repair-and-remodel exposure (which is less cyclical than new construction), and its history of consistent share buybacks. The EPS surprise factor score ranks in the 76th percentile, reflecting a track record of beating estimates. Bears counter that commodity and input costs remain a drag, sales growth is running below what the stock's post-rally multiple demands, and a broader housing slowdown could compress margins further. The trailing P/E near 17x is not demanding, but the EV/EBITDA has drifted to roughly 12.2x, ticking higher over the past month.
The July 27 print will test whether Masco's input cost story has genuinely turned, or whether the short-seller retreat was simply a tactical squeeze ahead of a number that may yet disappoint on the margin line.
Against its own history
This week's change in short interest is 1.6 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved -3.5% over the past week against a median of -4.5% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open MAS on ORTEX →How this article was generated
- Generated
- 24 Jul 2026, 04:05
- Data as of
- 24 Jul 2026, 03:52
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.