
AbbVie at $257 — Three Days From the Q2 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
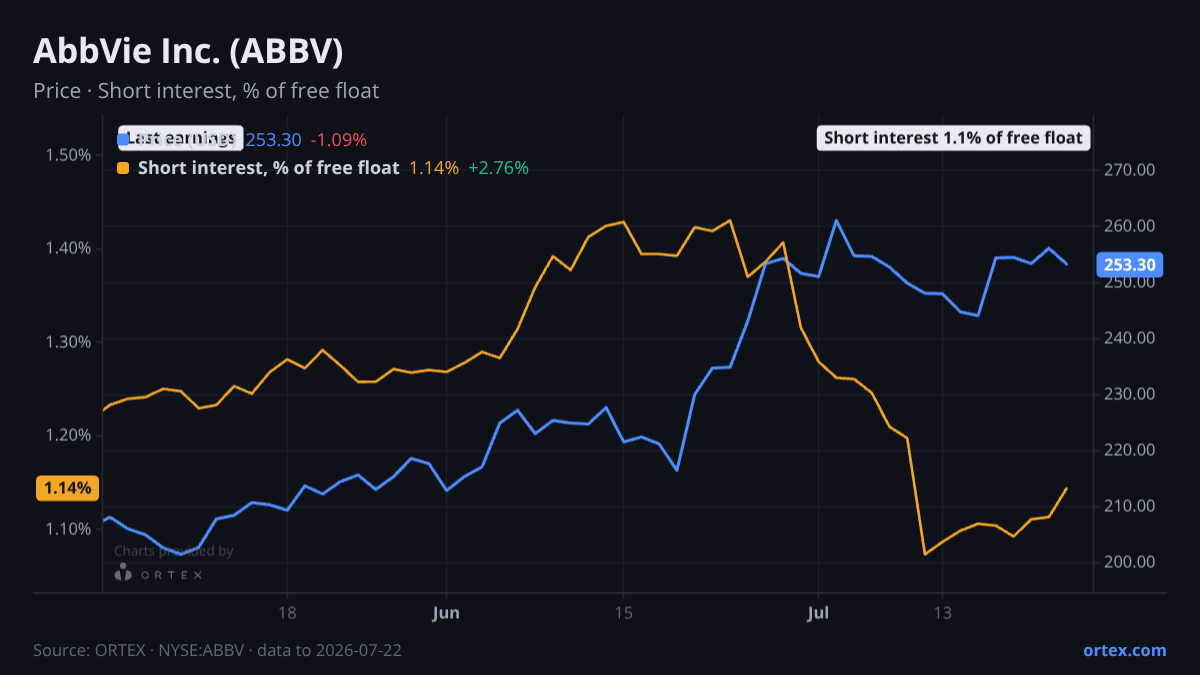
ABBV enters the final stretch before its July 27 Q2 report having added 12% in a month, with the analyst community and the options market both pointing in the same direction.
Options positioning offers the clearest read on sentiment: traders are not hedging this print aggressively. The put/call ratio runs at 0.76, fractionally below its 20-day average and nowhere near the defensive readings seen earlier this year. The 52-week high on the PCR is 1.13 — the current reading is at the relaxed end of that range. In the lending market, the picture is equally calm. Availability is essentially uncapped, borrow costs hover near 0.4%, and short interest has retreated sharply — down roughly 18% from a month ago to just 1.14% of the free float. Bears have been covering into the rally, not adding.
The analyst debate, such as it is, has tilted decisively bullish. Ten target increases have arrived since July 6. JP Morgan raised to $280 from $260. Wells Fargo lifted to $295. BMO sits at $300. The caution comes from Citigroup and UBS, both at Neutral with targets of $260 — a level the stock has now passed. The consensus mean of $266.89 implies roughly 4% further upside from $256.92, a gap that has compressed considerably as the stock has rallied. Bulls frame this as a franchise re-rating: Skyrizi and Rinvoq driving consistent script growth, a pipeline of over 90 compounds reducing single-product dependency, and forward EPS growth ranking in the 99th percentile of the ORTEX universe. Bears have not changed their argument — pricing headwinds, Imbruvica competition, and the risk that valuation now prices in the optimistic case — but they are losing the near-term narrative.
One ownership data point sharpens the setup. Capital Research added over 11.5 million shares in the most recent reported quarter, the largest net addition among the top institutional holders. BlackRock added another 3.6 million. These are not small adjustments for a stock of this size, and they arrived ahead of the current rally — suggesting the institutional accumulation preceded rather than chased the price move. The earnings history adds further texture: the April print produced a 6.9% gain on the day. The May event was essentially flat. Two prints, two different outcomes, which keeps the range of reactions genuinely open.
The July 27 Q2 report therefore tests a specific question: whether the Skyrizi and Rinvoq revenue trajectory, combined with pipeline progress, can validate the 12-point monthly re-rating at a valuation where the cautious wing of the Street is already sitting at-the-money.
Against its own history
This week's change in short interest is 2.9 standard deviations above the company's typical weekly move over the past year.
Against its peers
Shares moved +1.0% over the past week against a median of -0.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open ABBV on ORTEX →How this article was generated
- Generated
- 24 Jul 2026, 04:07
- Data as of
- 24 Jul 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.