
Crane Analysts Turn Constructive Ahead of July 27 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
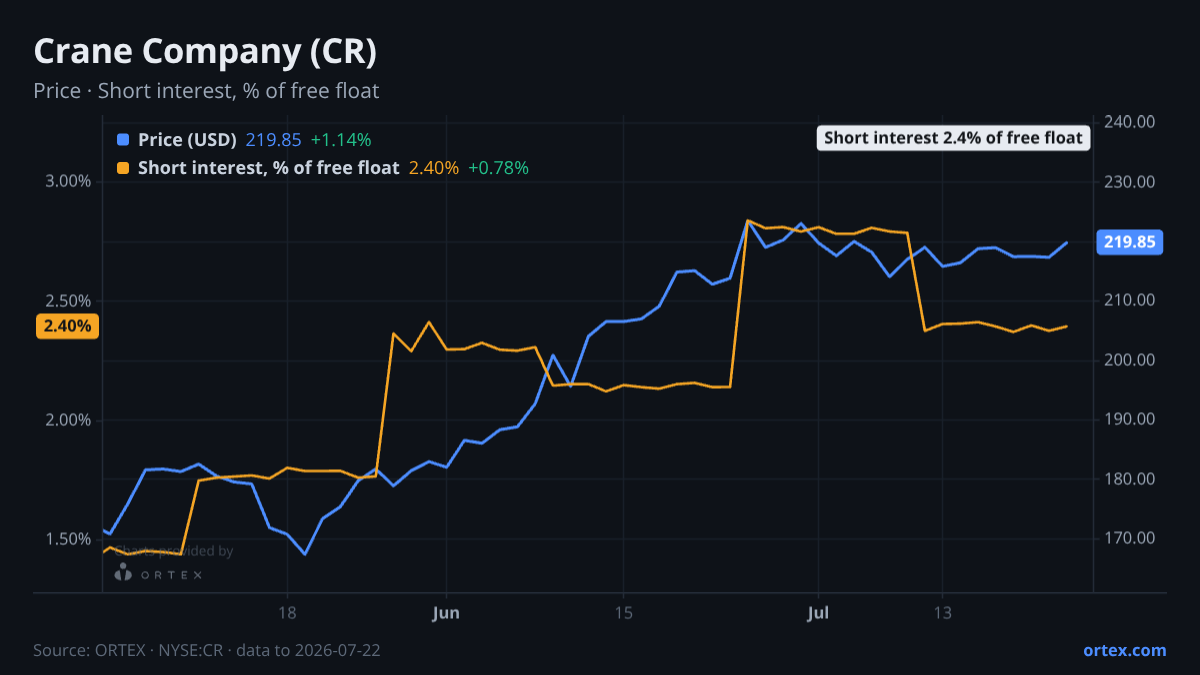
Crane Company heads into its Q2 earnings report on July 27 with the analyst community shifting notably more positive — even as options traders bet heavily on the upside.
The most telling move came this week. Stifel raised its price target from $215 to $242 on July 20, keeping a Buy rating. The same day, BMO Capital initiated coverage with an Outperform and a $253 target — the most bullish on the Street. That puts the consensus mean target at $230, a 5.5% premium to the current price of $218. The direction of travel is clear: analysts who spent early 2026 cautious are now leaning in. Stifel's own journey is illustrative — the firm sat at Hold with a trimmed $200 target in April before upgrading to Buy after the Q1 print.
Options positioning reinforces that bullish lean, sharply so. The put/call ratio has collapsed to 0.46 — nearly two standard deviations below its 20-day average of 0.92 and close to the 52-week low of 0.25. That's an unusually call-heavy tilt. The shift is stark: through mid-July, the PCR ran above 1.05 for nearly two weeks straight. Something changed around July 17, and call buying has dominated since.
The bull case centers on Crane's diversified industrial franchise, clean balance sheet, and M&A optionality. Bears point to lingering aerospace-related exposure, potential cost pressure from steel and aluminum inputs, and a valuation that isn't cheap — the stock trades at a trailing P/E near 30 and EV/EBITDA approaching 20. Crane's forward EPS growth ranks in the 87th percentile of its universe, which supports the multiple, but its EPS surprise track record is more modest at the 36th percentile. That matters because the last three earnings prints all produced negative one-day moves, averaging roughly 3% lower on the day and extending losses over the following week.
Short interest offers little drama here. At 2.4% of the free float, it is low by any measure. Borrow availability is essentially unlimited — availability runs well above 9,000% — and cost to borrow is just 0.48%, a negligible friction. Short sellers are not a meaningful force in this setup either as a threat or as a potential catalyst. Among close peers, Parker Hannifin and Rexnord both gained on the week while EPAC slipped 3.2% — a mixed backdrop for the broader industrial machinery space.
Sunday's print will test whether Crane's improving operational momentum is durable enough to justify the fresh analyst optimism — and whether call buyers who piled in this week get the confirmation they're positioned for.
Against its own history
This week's change in short interest is 1.6 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved -0.4% over the past week against a median of +1.3% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open CR on ORTEX →How this article was generated
- Generated
- 24 Jul 2026, 04:09
- Data as of
- 24 Jul 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.