
Colgate Bulls Lift Targets as Analysts Rally Ahead of Q2 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
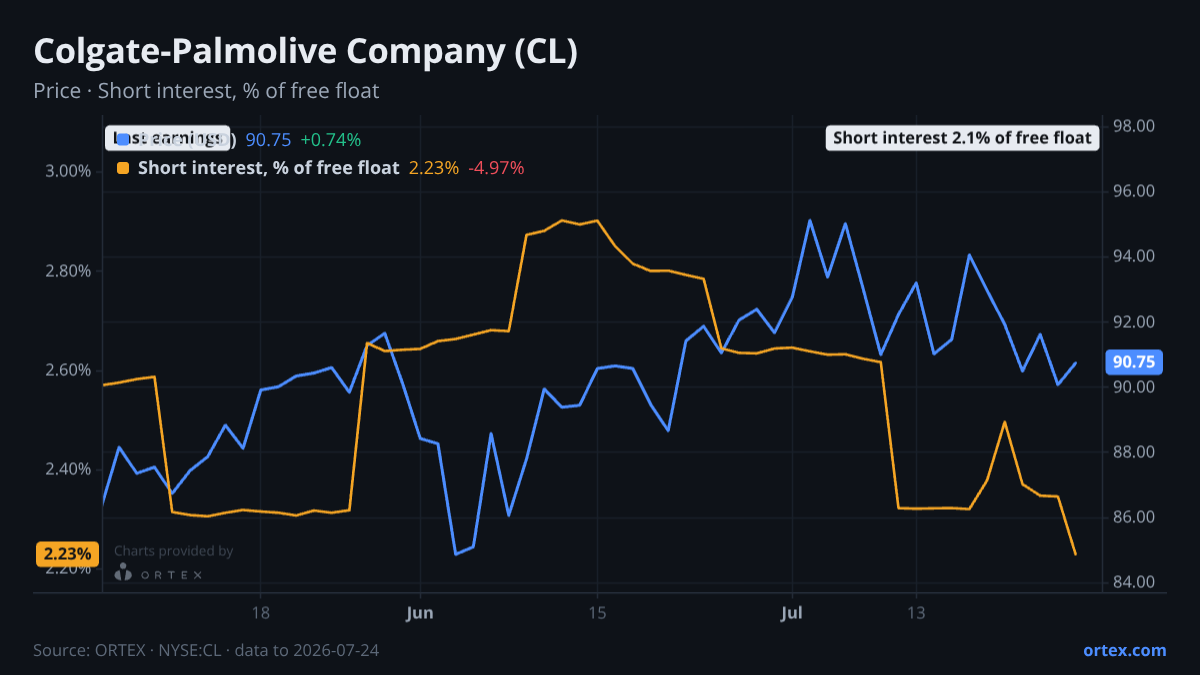
Colgate-Palmolive heads into its July 31 Q2 earnings report with analysts broadly more constructive than they were a month ago — and the options market reflecting that confidence rather than fear.
The most striking pre-earnings signal is the wave of upward analyst revisions. Four bellwether firms — JP Morgan, UBS, Citigroup, and Barclays — all raised price targets in the past three weeks, with JP Morgan lifting to $104 and UBS moving to $106. Barclays, which holds the most cautious view at Equal-Weight, still nudged its target from $80 to $87 last week. The mean consensus target now sits at $97.65, roughly 6% above the current price of $91.98. That breadth of upward revision — across both bulls and neutral-rated firms — is the clearest signal that the Street is resetting expectations ahead of the print.
Options positioning reinforces that broadly relaxed tone. Call demand has been running ahead of put demand, with the put/call ratio at 0.58 — below its 20-day average of 0.65 and near the 52-week low of 0.51. That represents the least defensive options posture Colgate has seen all year. Short interest adds little tension to the picture: at just over 2% of the free float, it has fallen more than 20% over the past month, a steady unwind rather than any kind of squeeze setup. The borrow market is extremely loose, with availability far exceeding any plausible demand for new short positions, and cost to borrow remains negligible at 0.44% despite a recent uptick.
The bull case rests on Colgate's international franchise — roughly 70% of sales come from outside the US — and an expectation that emerging-market volumes recover as input cost pressures ease. Bears point to the margin story: gross margin fell 75 basis points year-over-year in Q2 2025 due to raw material costs and tariffs, and volume trends remained slightly negative through last year. Hill's, the pet nutrition unit, has shown sustained weakness in measured retail channels. The PE of roughly 23x is not demanding for a consumer staples compounder, but the price-to-book above 96x reflects how thin the equity base is relative to the stock's valuation. Among close peers, PG slipped 1.7% on the week while KMB gained 1.2%, leaving Colgate broadly in the middle of the group.
The earnings report will therefore test whether Colgate's volume trajectory has turned — and whether management can point to margin recovery credible enough to justify the freshly lifted targets from analysts who moved early.
Against its peers
Shares moved +0.1% over the past week against a median of -1.3% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open CL on ORTEX →How this article was generated
- Generated
- 28 Jul 2026, 04:04
- Data as of
- 28 Jul 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.