
SPY Put-Call Ratio Spikes as Shorts Complete Their Exit
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
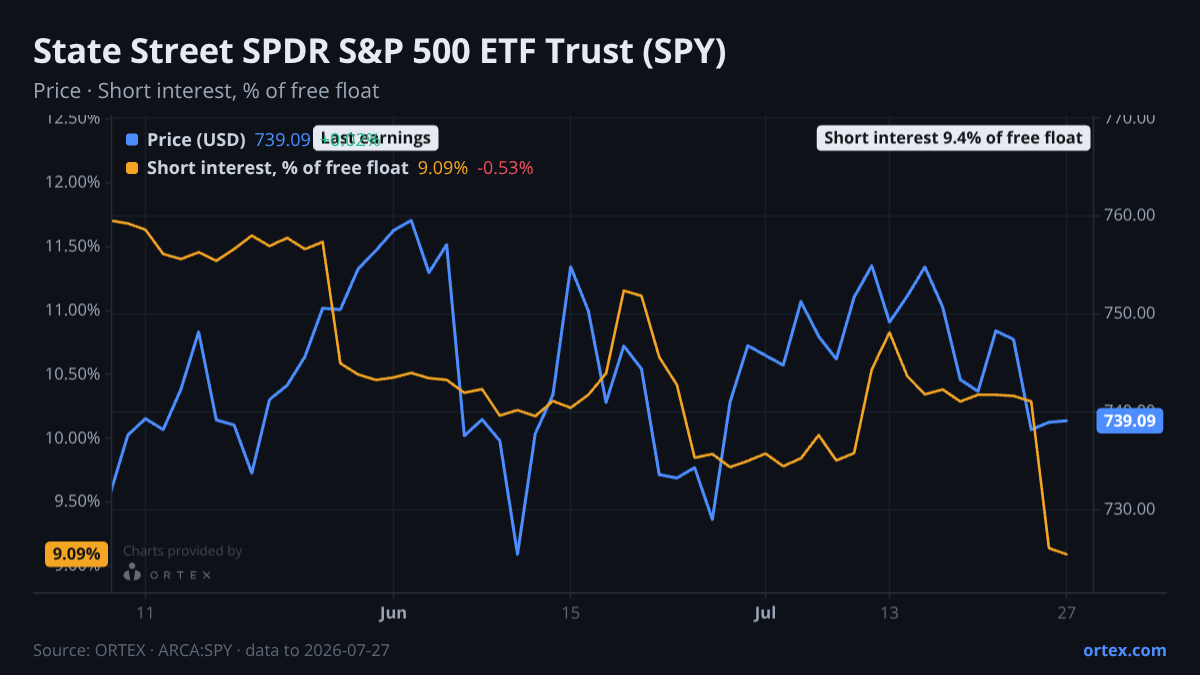
Options traders turned sharply defensive on Tuesday. SPY put-call ratio jumped to 1.99 — a z-score of 2.14, the highest in weeks. That's happening even as the short sellers who drove the prior cycle have nearly finished covering.
The divergence is the story. Shorts are out. Options hedgers are stepping back in.
Options Hedgers Flip Defensive
The PCR move on July 28 stands out. At 1.99, it is well above the 20-day mean of 1.75 and sits at a z-score of 2.14. The 52-week high is 2.40, so this is elevated but not extreme. What makes it notable is the speed. Just last week, PCR was 1.67. It rose 19% in a single session.
That is the options market pricing in tail risk. Whether that risk is geopolitical, macro, or simply a hedge against the recent rally is unclear from the data alone. What is clear: put demand spiked sharply on Tuesday.
Shorts Already Cleared Out
The short covering that dominated last week's report is now embedded in the data. SI sits at 9.4% of the free float as of July 27, down from the 10.5–10.6% plateau that held from July 13 to 22. The 11% weekly decline is the largest cover of the current cycle.
Shares short stand at 96.4 million — roughly where they were in early July before the Iran escalation rebuilt positions. The thesis that drove that rebuild has unwound. The data is consistent with the July 27 report: shorts abandoned Iran-driven positions following the ceasefire news.
Borrow Market Has Loosened Sharply
Availability now reads 2,608% — more than 26 shares available for every one currently lent out. That is the loosest reading since before the Iran escalation began in mid-June. For context, availability hit as low as 194% on June 19 at the peak of geopolitical fear.
Cost to borrow has pulled back to 0.25%, down 44% over the past month. The borrow market is no longer pricing in stress.
Two Markets, Two Views
The tension now is between positioning signals. Short sellers have covered. The borrow market is loose. Yet options traders bought puts aggressively on Tuesday.
The ORTEX short score sits at 44.2 and has been declining steadily from 48.1 on July 21. That directional fall reflects the short cover and easing borrow conditions.
The put-call ratio spike sits against that backdrop as a counter-signal. It does not reverse the short cover story. But it suggests at least one corner of the market is not fully convinced the risk has passed.
- SI % of free float: 9.4% (July 27), down 11% week-on-week
- PCR: 1.99 (July 28), z-score 2.14 vs 20-day mean of 1.75
- Availability: 2,608% — loosest reading of the current cycle
- Cost to borrow: 0.25%, down 44% month-on-month
- Short score: 44.2, falling from 48.1 one week ago
Against its own history
This week's change in short interest is 1.9 standard deviations below the company's typical weekly move over the past year.
Stocks in this article
See the live data behind this article on ORTEX.
Open SPY on ORTEX →How this article was generated
- Generated
- 29 Jul 2026, 06:13
- Data as of
- 29 Jul 2026, 06:06
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notesPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.