
Itaú Heads Into Q2 Print With Options Traders on Edge
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
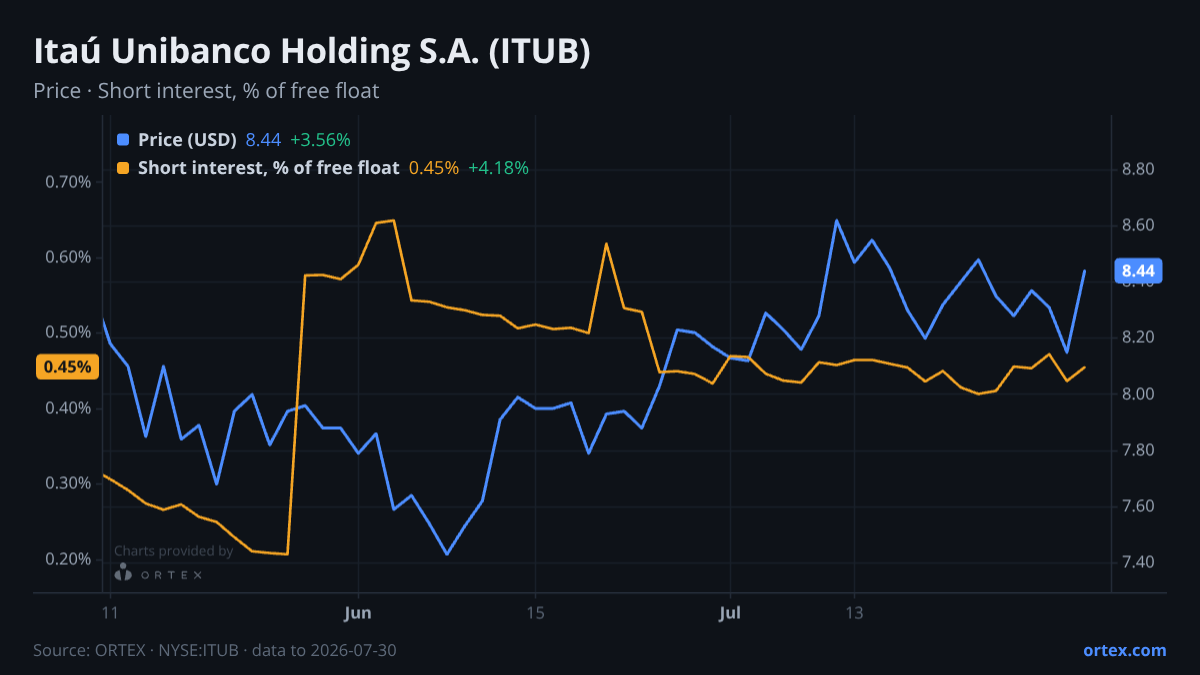
ITUB reports second-quarter results on August 4 with options positioning signalling more caution than the stock's recent drift higher would suggest.
The defensive tilt in options is the standout heading into the print. The put/call ratio has climbed to 1.248 — more than two standard deviations above its 20-day average of 1.18 — its most elevated reading in recent weeks. That level of hedging demand is notable precisely because the borrow market tells the opposite story: availability is extraordinarily loose at over 6,400%, meaning shares to borrow are plentiful and short sellers are not pressing the trade. Short interest edged up roughly 8% on the week to around 24.5 million shares, but borrowing costs remain near 0.58% — low by any measure, despite nearly doubling in the past month. The stock itself has moved modestly higher, gaining 2.2% on the week and 3.5% on the month to $8.46, recovering ground lost after the May print when it fell more than 4% on the day and nearly 8.5% over the following week.
That May reaction frames the bull-bear debate heading into August. JP Morgan lifted its target to $10 — an 18% premium to the current price — in early July, maintaining an Overweight rating for the third consecutive raise in twelve months. The consensus mean target of $8.84 implies more modest upside and the analyst data is slightly stale at 17 days old, though the directional drift from the Street has been constructive. Bears point to what a recent ORTEX note flagged: forward EPS estimates are trending lower, the 91-day relative-strength reading has turned negative, and quality scores have deteriorated materially over the past month. The valuation provides limited cushion on either side — a trailing P/E near 8.9x and a price-to-book around 2.1x reflect a bank priced for moderate growth in an economy where rate expectations remain fluid.
Capital Research and Management stands out on the ownership side, having added more than 32 million shares in the most recent reported period — a meaningful increase relative to its existing position. BlackRock and Vanguard also added incrementally, while the controlling shareholder Itaúsa holds over 46% of shares, anchoring the register. That concentrated ownership and the loose borrow market together limit the conditions for any sharp short-driven dislocation around the print.
The August 4 result is therefore less a test of whether Itaú is growing — loan growth and net interest margins have held up — and more a test of whether management guidance on 2026 expansion targets and margin trajectory can justify a stock that has re-rated higher even as forward earnings estimates have been revised down.
Stocks in this article
See the live data behind this article on ORTEX.
Open ITUB on ORTEX →How this article was generated
- Generated
- 1 Aug 2026, 04:10
- Data as of
- 1 Aug 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.