
UBS Upgrade Meets Bullish Options Surge as SOLV Heads Into Q2 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
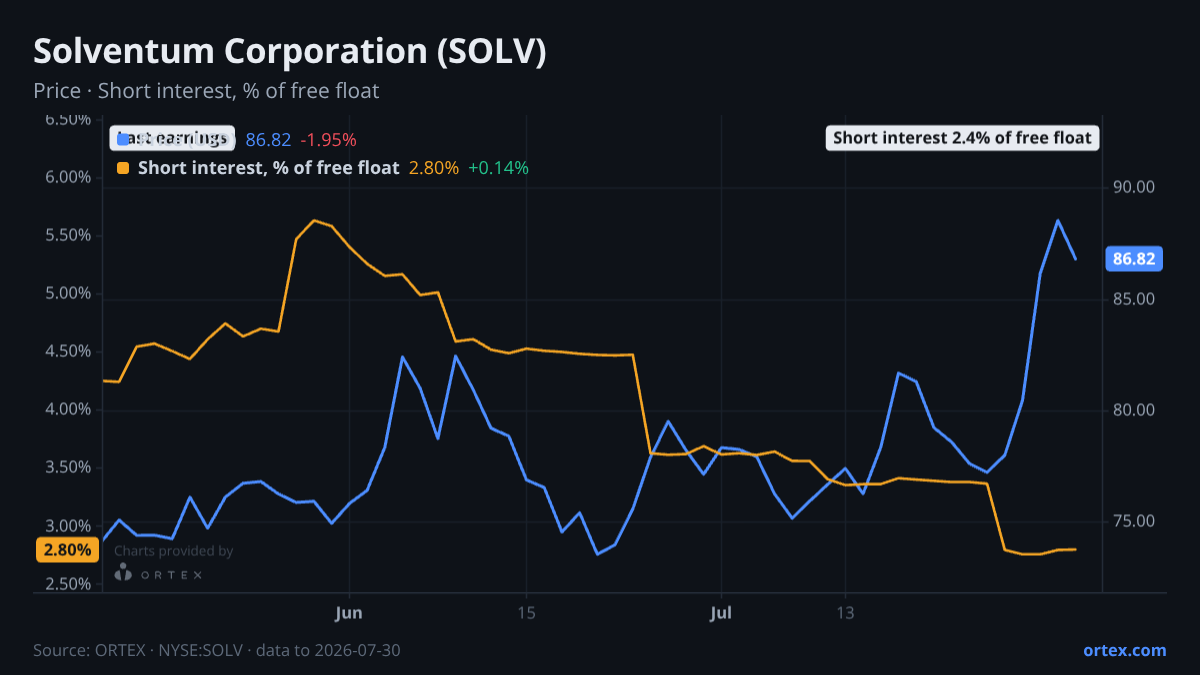
SOLV enters its August 5 earnings release riding a 10.7% one-month gain to $85.44, with the most striking pre-print signal coming not from short sellers but from the options market and a well-timed analyst upgrade.
Options positioning has shifted decisively toward calls. The put/call ratio has collapsed to 0.037 — near its 52-week low of 0.037 — running almost 1.7 standard deviations below its 20-day average of 0.22. That is an unusually aggressive call-side lean, suggesting options traders have been adding upside exposure rather than hedging into the print. The move is consistent with the price action: SOLV gained nearly 10% over the past week alone, and the stock now trades fractionally above the consensus mean price target of $84.69.
The analyst backdrop adds fuel to that optimism. UBS upgraded SOLV to Buy with a $95 target on July 28 — just days before the earnings release — reversing a prior Neutral stance. That is a meaningful signal from a bellwether firm, and it puts UBS near the top of the target range. The broader consensus leans constructive, with seven buys against five holds. Bulls point to a strengthening product portfolio, progress toward 2028 financial targets, and modestly better-than-expected Q1 results as evidence the post-spinoff story is taking hold. Bears counter that organic growth of just 2.3% for FY26 reflects heavy dependence on deals like the Acera acquisition, while tariff headwinds could weigh on pre-tax earnings by up to $120 million. The forward EPS growth picture is weak — the 12-month forward year-on-year increase ranks in just the 7th percentile — and EPS surprise history has been inconsistent, sitting at the 13th percentile.
Short selling tells a quieter story. Bears have been retreating: short interest fell 37% over the past month to roughly 2.4% of the float, well into low-conviction territory. Borrow availability is exceptionally loose at 1,357% — more than 13 shares available for every one currently borrowed — so there is no structural squeeze dynamic at play. Cost to borrow has ticked up 45% over the past week to 0.60%, but at that level it remains a negligible friction. The institutional register also skews toward stability: 3M Company retains a 14.8% stake, and Trian Fund Management holds nearly 5%, providing a base of long-term holders unlikely to exit on a modest miss.
Past prints have been kind: over the last three earnings events the stock moved higher on the day each time, with one-day gains ranging from 2.3% to 5.3% and five-day follow-through reaching as high as 11.4%. The August 5 print will test whether those momentum credentials and the UBS conviction are justified by the underlying numbers — particularly on organic growth and the degree to which M&A activity is masking operational progress.
Against its peers
Shares moved +9.5% over the past week against a median of +7.9% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open SOLV on ORTEX →How this article was generated
- Generated
- 2 Aug 2026, 04:26
- Data as of
- 2 Aug 2026, 04:04
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.