
Marriott Heads Into Results After Sharp Selloff — Options Tell the Real Story
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
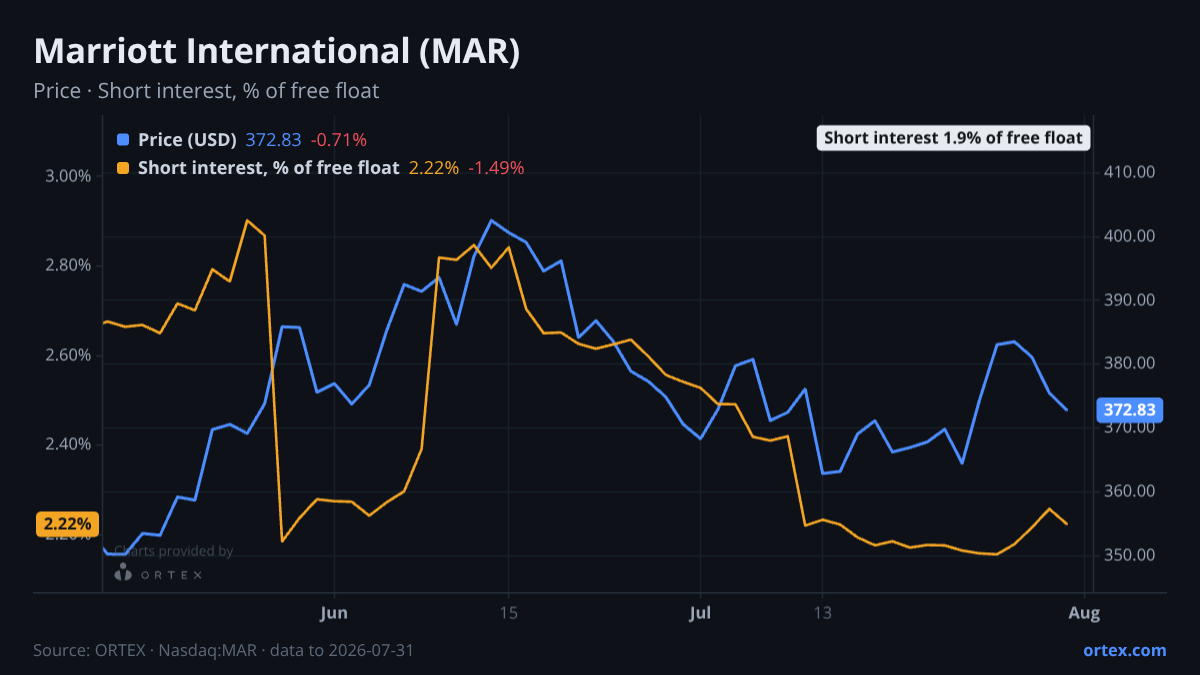
Marriott International reports Q2 2026 earnings on August 6 against an unusually charged backdrop: a stock down nearly 10% in a week, options traders hedging at their most defensive level in over a year.
The clearest pre-earnings signal is in the options market. The put/call ratio jumped to 0.75 on Monday — more than two standard deviations above its 20-day average of 0.68, and the highest reading of the past year. Demand for downside protection has spiked sharply just as the stock accelerated lower. Marriott fell 7% on Monday alone, extending a one-month loss to 7% and leaving the stock at $346.83. That move is strikingly large relative to peers: Hilton was off less than 0.5% on the day, Hyatt fell 1.5%, while Carnival and IHG closed essentially flat. Marriott's selloff looks idiosyncratic — and it has pulled the stock below the mean analyst price target of $381, making the print a credibility test for the bulls.
The analyst community has been broadly constructive heading into results. Multiple banks lifted targets in mid-to-late July — Morgan Stanley raised to $380 from $353, JP Morgan moved to $400 from $387, and TD Cowen went to $420. The bull case centres on the asset-light franchise model, a resilient global brand portfolio, and strong forward RevPAR and EBITDA guidance. Bears push back on three fronts: regional drag from the Middle East conflict is estimated to be shaving 100–125 basis points from global RevPAR growth; group and government travel remains flat; and the balance sheet carries elevated debt. Macquarie's Alpha Model flags lower-percentile exposures across value, momentum, and quality factors — a warning that the multiple may not be adequately pricing in these risks. With the PE multiple running near 29.8x and EV/EBITDA at 18.6x, Marriott is priced for continued execution.
Short interest is not what's driving the debate. At roughly 1.9% of the free float — and down more than 15% over the past month — there is no meaningful short base building pressure ahead of the print. Borrow availability is extraordinarily loose at over 2,600%, with a cost to borrow near 0.39%. The ORTEX short score of 34.5 sits in the middle of its recent range. This is a stock where the pressure is coming from long-side holders reassessing the thesis, not from shorts pressing a position.
Thursday's print will test whether the regional headwinds in CALA and EMEA are as manageable as management has implied — and whether demand trends in North American leisure and business travel remain strong enough to justify a valuation that had, until this week, left little room for disappointment.
Against its peers
Shares moved -9.5% over the past week against a median of +1.7% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open MAR on ORTEX →How this article was generated
- Generated
- 4 Aug 2026, 04:12
- Data as of
- 4 Aug 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.