
Sea Limited Heads Into Q2 Print With Options Traders Turning Cautious
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
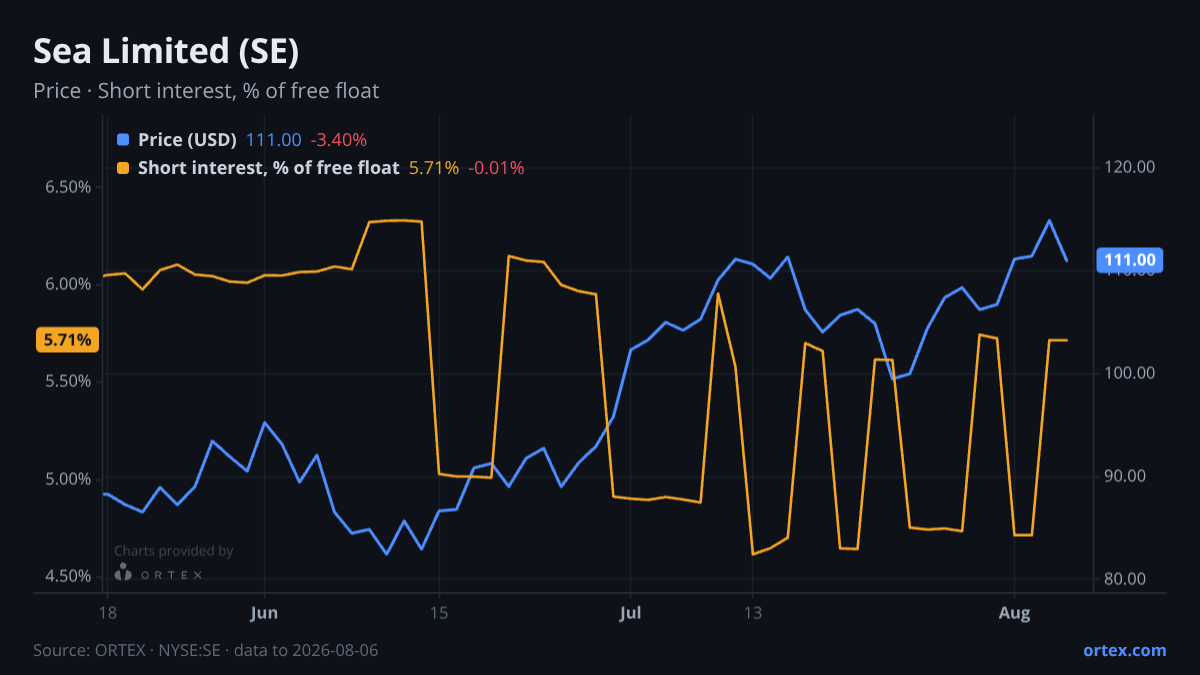
SE heads into its August 11 earnings report with one signal diverging sharply from an otherwise calm setup: options traders are the most defensively positioned they have been in months.
The put/call ratio jumped to 0.65 on August 7 — more than 2.4 standard deviations above its 20-day average of 0.59. That is the most skewed reading in recent memory, though still well below the 52-week high of 1.12, suggesting caution rather than outright fear. The move stands out against a backdrop where the broader positioning looks relaxed. Borrow availability is extraordinarily loose at over 2,200% — meaning shares available to lend dwarf the current short position by a factor of more than 22. Cost to borrow has fallen 39% over the past month to just 0.34%. Short sellers have also been trimming exposure, with shares short down roughly 3.7% over the same period to around 18.9 million. That combination — fading short interest, abundant borrow supply, and cheap financing — describes a stock that bears are not pressing hard. The options tick on August 7 is therefore the one note of genuine caution heading into the print.
The bull-versus-bear debate on SE centers on whether the company can convert strong top-line momentum into durable profitability. Bulls point to the fintech arm — SeaMoney delivered 70% year-over-year revenue growth with adjusted EBITDA up more than 50% — alongside a 25% GMV expansion at Shopee and continued bookings growth at Garena. Bears counter that the e-commerce segment's EBITDA margin of just 0.8% of GMV leaves little room for error, particularly as reinvestment spending keeps profitability thin. Analyst sentiment reflects this split. The consensus mean price target of $142 implies roughly 25% upside from the current $113.43. TD Cowen, which holds a Hold rating, cut its target to $100 just this week — sitting below the current price, a meaningful signal of skepticism on valuation. JPMorgan carries an Overweight with a $163 target, while Barclays has an Overweight at $122, both trimmed from higher levels earlier in the year. The Street broadly still sees upside, but the range of targets from $100 to $163 reflects genuine disagreement about the pace of margin improvement.
One ownership dynamic worth noting: COO Gang Ye sold roughly $2.2 million worth of shares across August 5 and 6, just days before the print. These are small relative to his total stake of 3.46% of the company. Net insider activity over the past 90 days is modestly positive at roughly $12 million in net purchases across all insiders. The largest institutional holders — Tencent at 16.7%, Baillie Gifford at 6.3%, and T. Rowe Price, which added nearly 12.9 million shares in the most recent quarter — remain committed longs. The stock gained 10.2% on the day of its last earnings release in May, though that gain faded to roughly 2.8% over the following five trading days.
The August 11 print will test whether Sea can show a credible path to margin expansion at Shopee — or whether continued reinvestment spending keeps the bull case a story of promise rather than delivery.
Against its peers
Shares moved +6.3% over the past week against a median of +1.4% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open SE on ORTEX →How this article was generated
- Generated
- 8 Aug 2026, 04:04
- Data as of
- 8 Aug 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.