
Comcast bounces hard as shorts retreat
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
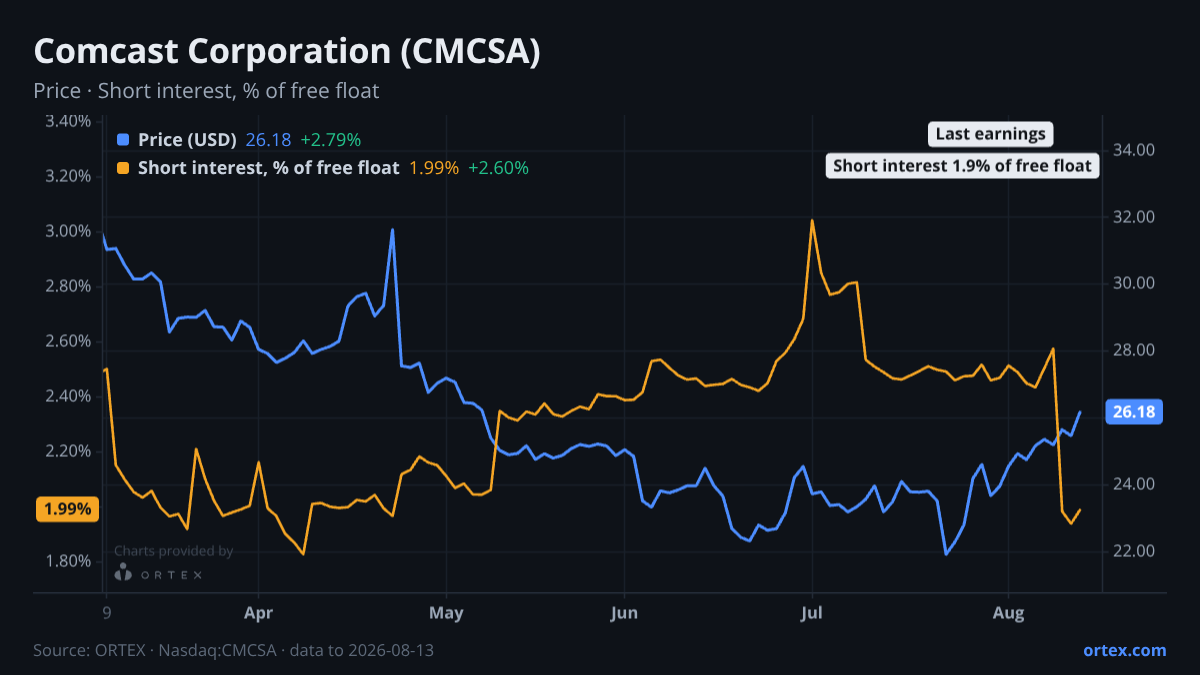
Comcast has staged a sharp 13% recovery over the past month while short sellers have been covering at the fastest pace seen in the data — and the question now is whether the rally has legs or simply reflects crowded shorts unwinding.
The most striking development in the lending market is how quickly short positioning has collapsed. Short interest fell nearly 29% over the past 30 days and shed another 19% in the past week alone, dropping from roughly 88 million shares to just under 70 million. At 1.9% of the free float, short interest is now firmly in "low" territory — this is not a crowded short. Borrow conditions tell the same story: availability is exceptionally loose at 6,812%, meaning roughly 3.5 billion shares remain available to borrow versus the 70 million currently shorted. Cost to borrow, at 0.43%, is close to riskless. There is no squeeze mechanic here — the short covering has been orderly, not forced. Options confirm the relaxed mood: the put/call ratio at 0.44 sits fractionally below its 20-day average of 0.46, with a z-score barely a standard deviation below that average. Neither calls nor puts are dominating; positioning is quiet.
The Street is a more complicated picture. Target-price cuts dominated analyst activity through July, with Wells Fargo, Barclays, RBC, Goldman, and Morgan Stanley all trimming — in most cases by $2–$3 — while holding their ratings unchanged. That pattern suggests analysts still broadly see upside from current levels but are anchoring to lower base cases after the company's Q2 print. The mean price target sits at $30.08, about 15% above the current $26.20. Wells Fargo maintains the clearest bearish lean with an Underweight rating and a $23 target — actually below the current price — while Rosenblatt holds a $31 Buy. EV/EBITDA has drifted up to 5.7x and the PE is running near 7.3x, both modest multiples for a company of this scale but not obviously cheap given the structural headwinds. Factor scores reflect the same ambivalence: the dividend score ranks in the 99th percentile (the stock is valued heavily on yield), but EPS momentum over both 30- and 90-day windows ranks in the 20s — near the bottom of the universe — and the analyst recommendation differential sits at just 5, signalling near-consensus neutrality.
The earnings reaction history is worth keeping in mind. Q2 results on July 23 knocked the stock 5.2% lower on the day, though it recovered within a week to close up 0.6% from the pre-print level. The prior event on July 30 produced a smaller 2.6% drop with a similar subsequent recovery. The pattern — sharp knee-jerk lower followed by a bounce — has been consistent, which may partly explain why shorts moved to cover so aggressively after the July dip rather than add. No next earnings date is currently set, so near-term catalysts are thin.
On the institutional side, the ownership picture is stable but not particularly directional. Capital Research added around 21 million shares in the latest filing period, and State Street added 12 million — both constructive at the margin. Arrowstreet's 40-million-share addition is notable in size if consistent with their quantitative rotation strategies. BlackRock, the largest holder at 8.8% of shares, added incrementally. None of these moves suggest a decisive institutional inflection, but the net bias among recent filers is mildly accumulative.
The key variable to watch from here is whether the fundamental picture — broadband subscriber trends, early NBCU spinoff signals, and first-year NBA rights cost absorption — begins to improve enough to pull target prices back up toward the mid-$30s, or whether the stock's one-month rally simply exhausts the short-covering tailwind and runs into the ceiling of neutral analyst conviction.
Against its own history
This week's change in short interest is 2.8 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved +3.3% over the past week against a median of +1.5% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open CMCSA on ORTEX →How this article was generated
- Generated
- 15 Aug 2026, 20:05
- Data as of
- 15 Aug 2026, 20:04
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.