
TJX Options Traders Turn Defensive Ahead of Tuesday's Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
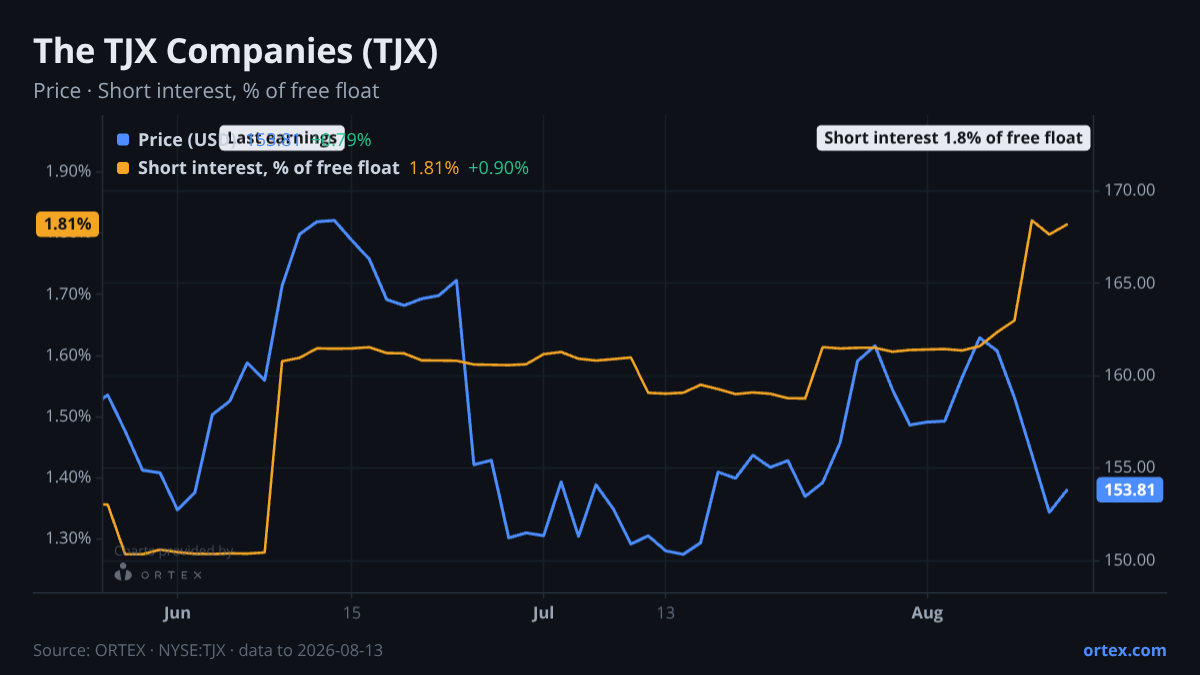
TJX heads into its August 19 earnings release with options positioning flashing its most defensive signal in months, even as the fundamental debate remains firmly tilted toward the bulls.
The clearest pre-earnings signal is in the options market. Downside protection demand has climbed well above its recent norm — the put/call ratio hit 1.06 on Friday, more than 2.5 standard deviations above its 20-day average of 0.82. That makes it one of the more elevated defensive readings of the past year, against a 52-week range of 0.31 to 1.33. The hedging push follows a bruising week for the stock, which dropped 5.7% to $152.11, though it remains up about 1% over the past month. Closest peer ROST also fell nearly 4% on the week, while BURL shed 5.8% — suggesting the move reflects sector-wide pressure rather than TJX-specific concern.
Short interest tells a notably less anxious story. Bears have been adding positions — short interest climbed roughly 13% over the past month to 1.8% of the free float — but that remains a low absolute level, and the lending market is far from stressed. Borrow availability is extraordinarily loose at over 7,000% of existing short interest, meaning new shorts face no friction whatsoever in sourcing shares. Cost to borrow has eased back to 0.43% after briefly touching 0.72% earlier this month. The ORTEX short score has drifted higher recently, reaching 33.0 from 31.6 two weeks ago, but that still ranks in just the 58th percentile — positioning looks cautious rather than crowded.
The Street is firmly in the bull camp, though all of the most recent analyst activity dates from May following the last earnings print, when a broad group of firms — including UBS, Barclays, and JPMorgan — raised price targets while holding positive ratings. The current consensus is a buy, with targets clustering between $174 and $197, well above the current price. Bulls point to TJX's durable off-price model, strong financial health (an f-score of 7 and return on assets of 13.7%), and its historical ability to gain share when consumers trade down. Bears counter that elevated inventory levels risk forcing margin-dilutive markdowns, and that the international expansion into Europe introduces cost complexity. Valuation is not cheap — the stock trades at roughly 27.7x trailing earnings and 13.6x book — and with a forward EPS growth score in just the 25th percentile, the multiple leaves little room for a guidance miss.
History has been kind to TJX around recent prints: the last three results each produced a one-day gain of roughly 4.5% to 5%, with the move holding through the following week. Tuesday's report will test whether that pattern holds against a backdrop of sector-wide selling pressure and the most defensive options setup the stock has seen in several months.
Against its own history
Short interest is at its highest level in at least a year.
Against its peers
Shares moved -5.7% over the past week against a median of -2.1% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open TJX on ORTEX →How this article was generated
- Generated
- 16 Aug 2026, 04:01
- Data as of
- 16 Aug 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.