
AIG: Options Defensiveness Persists as Analysts Trim Targets
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
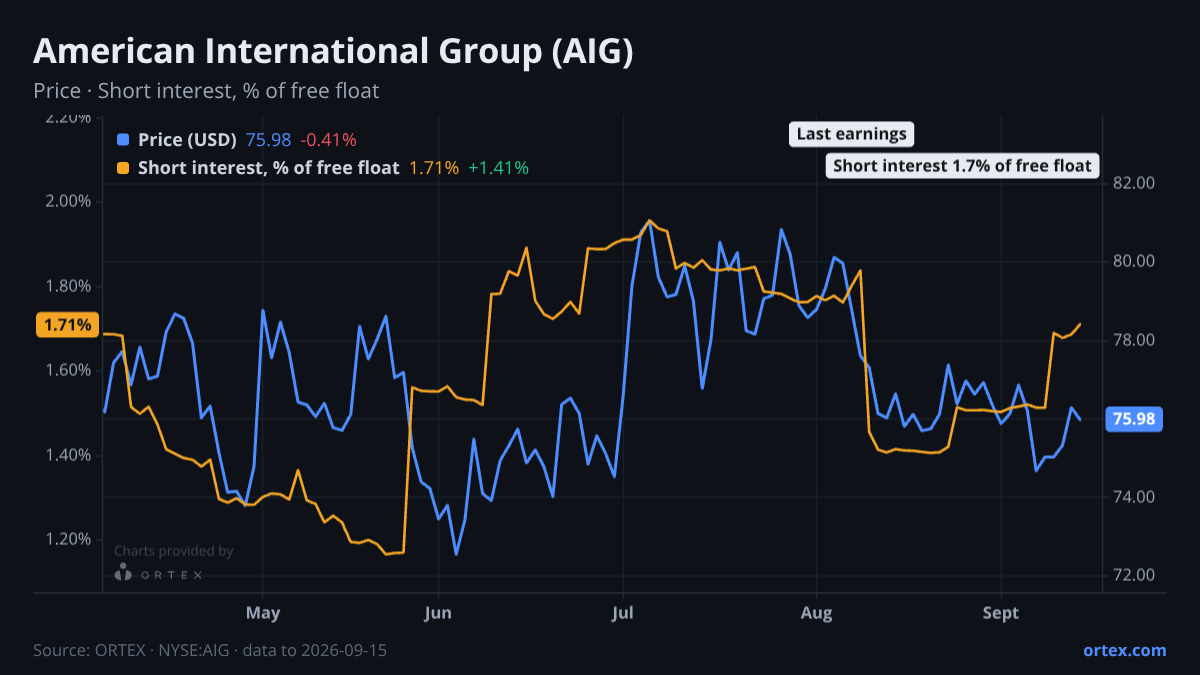
AIG heads into the back half of September with a familiar tension: analysts still see meaningful upside, but the recent pattern of target cuts has quietly eroded confidence in how quickly that gap closes.
The options market tells a modestly defensive story. The put/call ratio has run above 1.30 for most of the past three weeks, and while the current reading of 1.32 is only a quarter standard deviation above the 20-day mean of 1.28, the direction of travel is telling — the PCR peaked at 1.43 in early September, its highest level of the past year, before easing fractionally. That sustained elevation in put demand suggests investors have been leaning on downside protection through a stock that closed Tuesday at $75.98, up 1.7% on the week but still roughly flat over the past month. The borrow market, for its part, tells the opposite story: availability is effectively unlimited at current short interest levels, with costs running below 0.35% — a near-frictionless environment for anyone wanting to get short.
Short interest is low but building. At 1.65% of free float — around 8.9 million shares — the absolute level is not alarming. Yet the 12.6% weekly increase is the sharpest single-week jump in the 30-day window, driven by a visible step-change around September 9. Before that date, shares short had hovered near 7.9 million for most of August. The move happened quickly. At 0.35% cost to borrow and unlimited share availability, there is no mechanical friction deterring new short positioning, which makes that jump more deliberate than opportunistic.
The Street's read on AIG is a study in calibrated pessimism. Mizuho trimmed its target to $85 from $86 just this week, keeping a Neutral rating — and that move, small as it is, comes on top of a wave of post-earnings target reductions from Wells Fargo, Morgan Stanley, Barclays, and Cantor Fitzgerald following the early August print. Most who cut maintained their ratings, keeping the consensus constructive on paper; the mean target of $88.45 implies roughly 16% upside from current levels. But the direction of travel is clear. Against that, Keefe Bruyette raised its target to $96 and Argus reiterated Buy at $90, suggesting a genuine split between bulls who trust the P&C turnaround story and neutrals who have seen enough missed expectations to wait for evidence. The bear case centres on Convex underwriting drag, a slower buyback pace, and competitive margin pressure. The bull case points to net investment income growing 13% year-on-year and Convex premium growth compounding at 25% over three years. The EPS growth factor score ranks in the 97th percentile for forward estimate revisions — a striking number — yet near-term EPS momentum languishes around the 27th percentile, suggesting that long-run upgrade story has not yet fed into quarterly estimate trajectory. The P/E ratio of 8.9 and price-to-book below 1.0 keep valuation constructive in isolation.
On the insider side, the most notable recent activity requires a caveat before a conclusion. Executive Chair Peter Zaffino sold just over 236,000 shares across two days in mid-August, generating roughly $18 million in proceeds — but every transaction was executed under a pre-arranged 10b5-1 plan. Planned sales carry far less informational weight than discretionary ones. The net 90-day insider position across all transactions runs to a net sale of 236,829 shares, but stripping out compensation-linked awards and 10b5-1 plan sales leaves the true discretionary signal close to neutral.
Peers broadly had a slightly better week. MET gained 2.8%, EG rose 2.6%, and THG added 3.7% against AIG's 1.7% — continuing a pattern flagged in prior notes of AIG lagging the insurance peer group's recovery. The next scheduled earnings event is November 4, and with a stock that fell nearly 3% the day after its most recent Q2 print and a further 4% over the following week, what the options market does as that date approaches will be the sharpest measure of where sentiment is truly settling.
Against its own history
This week's change in short interest is 3.6 standard deviations above the company's typical weekly move over the past year.
Against its peers
Shares moved +1.7% over the past week against a median of +1.5% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open AIG on ORTEX →How this article was generated
- Generated
- 16 Sept 2026, 18:04
- Data as of
- 16 Sept 2026, 18:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.