
DRI: Post-Earnings Positioning Firms Up as Shorts Continue to Retreat
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
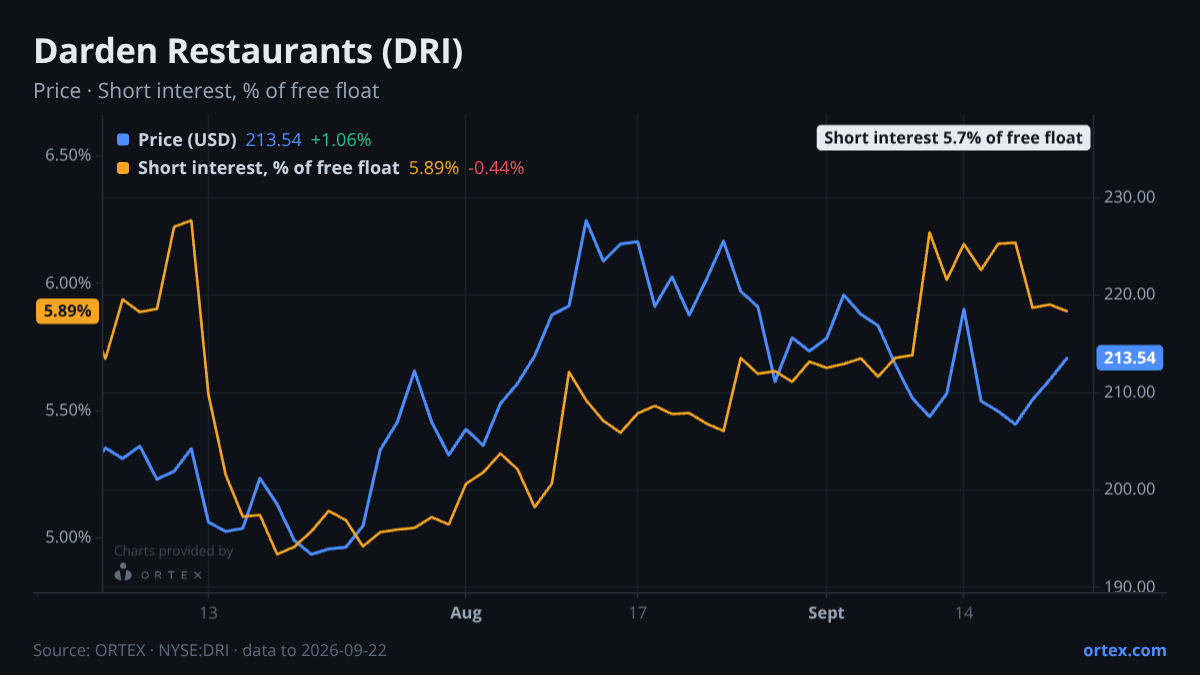
Darden Restaurants has cleared its earnings hurdle, and the market's response in the 24 hours since is telling a more constructive story than the pre-print setup suggested.
The short unwind that began after results hit is continuing. SI has eased to 5.7% of free float — around 6.66 million shares — down 4.3% on the week, reversing a build that ran more than 7% through August and early September. The lending market offers no friction to that retreat. Availability is extraordinarily loose at 954%, meaning roughly ten shares remain available to borrow for every one already lent out. That compares with the 52-week tightest reading of 576% — itself not a restrictive level. Borrow costs have also softened, running at 0.40% after falling 11% over the past week. The ORTEX short score has drifted lower to 46.7, near the softer end of its recent range, consistent with a position being quietly wound down rather than defended. Options positioning has turned mildly bullish: the put/call ratio dropped to 0.77 on the day of results, more than one standard deviation below its 20-day average of 0.84, suggesting the hedging demand that had been building through September has begun to lift.
The analyst community entered the print already leaning hard in one direction. Morgan Stanley and Oppenheimer both raised targets in the week before results — to $255 and $245 respectively — while Seaport Global initiated at Buy with a $240 target. The mean consensus target of $232.96 implies roughly 9% upside from Wednesday's close of $213.69, and every recent move from the Street has been upward. Bulls point to Darden's durable share gains across Olive Garden and LongHorn, its pricing discipline, and its position as the largest full-service dining operator globally. The one note of caution comes from Stephens, whose $220 target sits barely above the current price and reflects the bear case: food and labour inflation persistence, uneven consumer spending at mid-price dining occasions, and integration drag from recent acquisitions. The PE multiple has contracted roughly 1.2 points over the past 30 days to 17.7x, which gives the bulls room to argue the valuation reset is now behind the stock.
Peer behaviour over the past week adds context. CAKE surged 6.5% and DIN gained 5.5%, both outpacing DRI's 2.7% weekly gain. EAT added 1.6%, while TXRH and QSR both fell. DRI has held its ground relative to the more volatile names in the group, consistent with its lower-volatility profile entering a print where most of the Street was already positioned constructively.
The print has now cleared the near-term uncertainty, leaving the market to decide whether the post-results stability — shorts unwinding, options hedges lifting, analysts holding targets well above the current price — reflects genuine conviction or simply the absence of a negative catalyst to push back against.
Against its own history
This week's change in short interest is 2.4 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved +2.7% over the past week against a median of -1.3% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open DRI on ORTEX →How this article was generated
- Generated
- 24 Sept 2026, 04:01
- Data as of
- 24 Sept 2026, 03:58
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesPrevious Mi Articles
- Validation notes
- soft: missing section mentions: short interest (informational only)
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.