
Argus Downgrades YUM as Bears Build Positions
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
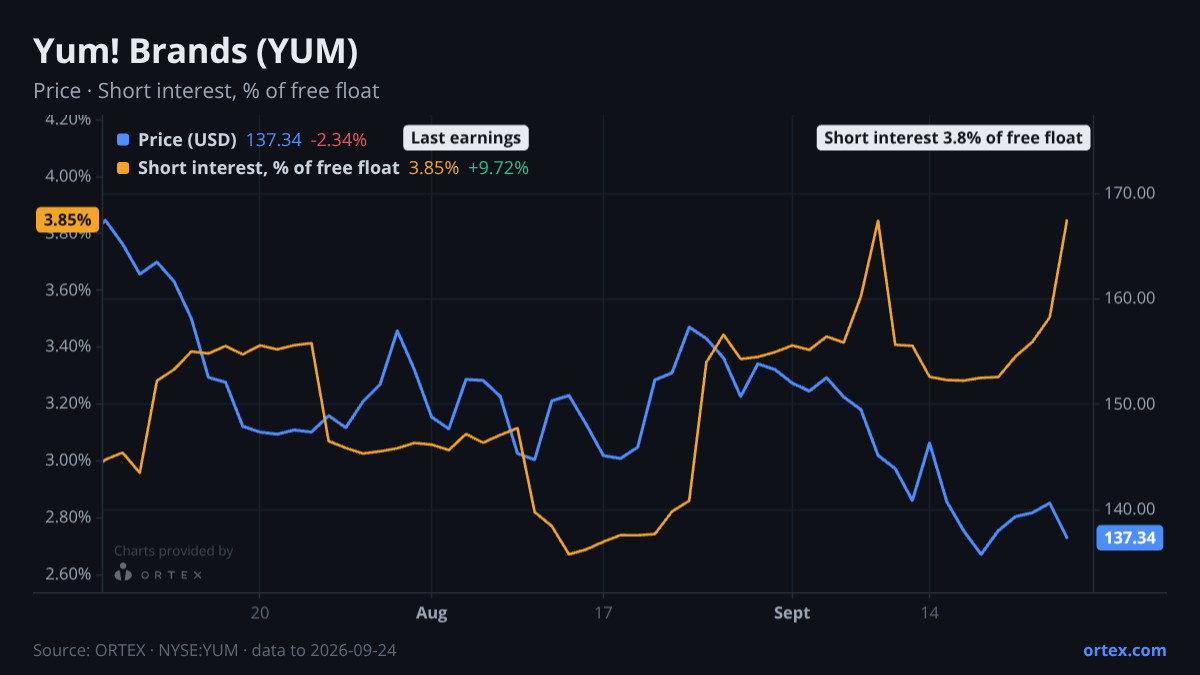
Why this matters: Three signals converged on YUM in 24 hours. Argus Research cut its rating to Hold. Short sellers pushed positions to the highest level since August. Options traders, however, dialled back their hedges sharply. The picture is mixed — but the direction of travel on the stock is clear: down 12.7% in a month.
Converging Signals
Argus pulls the Buy. John Staszak at Argus Research downgraded YUM to Hold on September 24 — just weeks after cutting his price target from $185 to $180 in August. This is the same analyst who maintained conviction through the summer weakness. The reversal signals that patience on the fundamental recovery thesis is wearing thin. The consensus has now shifted to Hold, with 10 buys against 14 holds as of September 24.
Short sellers accelerate. SI % FF hit 3.77% as of September 24, up 17.2% in one week and 40.5% over the past month. That's the highest short interest reading since August. The stock has fallen 12.7% over the same 30-day window. Shorts are not wrong — they're pressing a position that has been working. Days to cover stands at 4.9, per the most recent FINRA settlement data.
Options traders step back from hedges. The put-call ratio fell to 0.301 — a two-month low, sitting 1.78 standard deviations below its 20-day mean of 0.39. That's a notable divergence. While shorts press the bear case through the lending market, options traders are not adding protective puts. Either they see limited near-term downside, or they've already hedged via other means.
Corroborating Context
The borrow market is not flashing distress. Availability sits at 841%, meaning there is ample supply of shares to borrow. Cost to borrow is just 0.55% — low, despite rising 16.7% over the past month. There is no mechanical squeeze pressure building in the lending market.
T. Rowe Price added 1.28 million shares as of September 1. JP Morgan Asset Management added 904,000. Those are material inflows from large institutional holders — a counterweight to the short-side pessimism, though both filings predate the most recent leg down.
Earnings are due November 4. The bear case is well-documented: KFC international unit development slowing, Pizza Hut drag, margin pressure across the QSR sector. Peers MCD and CMG are also under pressure, both down more than 4% on the week.
Data Summary
- Price: $137.34, down 12.7% past month, down 2.3% yesterday
- SI % of Free Float: 3.77%, up 17.2% week-on-week (highest since August)
- Short interest change, 1 month: +40.5%
- Days to cover: 4.9 (FINRA, settled Sep 15)
- Availability: 841% — borrow market loose, no squeeze pressure
- Cost to borrow: 0.55%, low
- PCR: 0.301, z-score −1.78 vs 20-day mean
- Analyst consensus: Hold (10 buy / 14 hold)
- Argus action: Buy → Hold, Sep 24
- Next earnings: November 4, 2026
Against its own history
This week's change in short interest is 1.9 standard deviations above the company's typical weekly move over the past year. Short interest is at its highest level in at least a year.
Against its peers
Shares moved +1.2% over the past week against a median of -2.5% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open YUM on ORTEX →How this article was generated
- Generated
- 25 Sept 2026, 11:41
- Data as of
- 25 Sept 2026, 11:30
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.