
ZM Gives Back Its Rally With the Print One Day Away
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
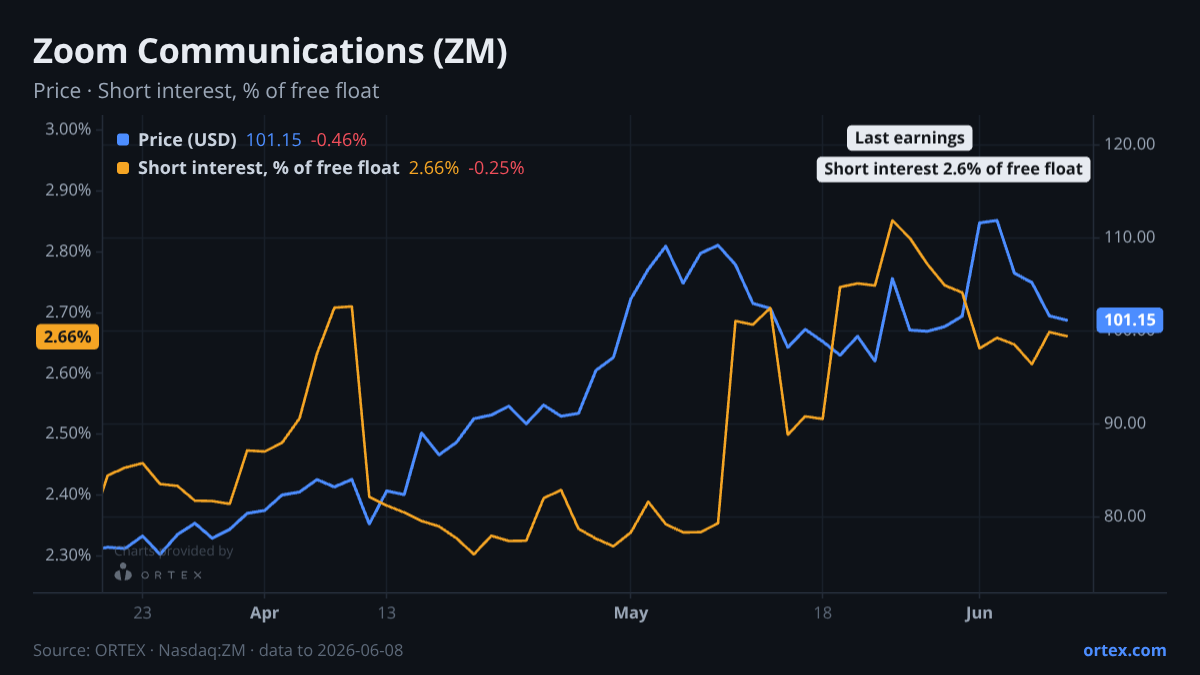
Zoom Communications heads into its June 11 earnings report having surrendered most of the gains that prompted last week's analyst upgrade wave — down 13% on the week and 4% on Tuesday alone, pulling back to $96.83 from the $111.88 level noted in the prior ORTEX article.
The reversal changes the setup materially. A week ago the stock was trading above most analyst targets; it now sits roughly 18% below the Street consensus of $113.92, with bulls at HSBC ($133) and RBC ($130) implying more than 30% upside from current levels. Options positioning is notably calm given the move — the put/call ratio of 0.57 is almost exactly in line with its 20-day average, and the z-score of 0.27 shows no unusual demand for downside protection. That is a quiet signal in the face of a sharp price decline. Borrow conditions tell the same relaxed story: availability is exceptionally loose at nearly 6,000% of short interest, and short interest itself has drifted lower on the week to 2.6% of float, a level that carries no meaningful squeeze or crowding risk.
The bull case rests on enterprise AI adoption. The recent note flagging stronger-than-expected Q1 guidance, driven by expansion of AI-powered collaboration features among large accounts, is the core argument for buyers who have stepped in below $100. Bears point to the churn risk from white-label customers and question whether AICompanion 3.0 uptake is enough to offset it — a concern that has weighed on sentiment even as the company's core financial profile looks solid, with an EV/EBITDA near 9.8x and a P/E of 16.4x that are not stretched by software standards. Morgan Stanley and Wells Fargo holding Equal-Weight at $105 — a target now above the stock price — signals that the neutral camp sees fair value but no catalyst for re-rating. The ORTEX short score of 31.4 is benign, consistent with the wider picture of a stock that bears have not aggressively targeted.
The earnings report is therefore a test of whether the enterprise AI narrative is gaining real commercial traction, or whether white-label churn is running faster than the new growth vectors can replace it — a question the price action this week suggests the market has not yet resolved.
Against its own history
This week's change in short interest is 2.5 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved -13.5% over the past week against a median of -10.8% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open ZM on ORTEX →How this article was generated
- Generated
- 10 Jun 2026, 04:06
- Data as of
- 10 Jun 2026, 04:02
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.