
Analysts Cut Targets After DECK's Miss, Print Round Two Due Thursday
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
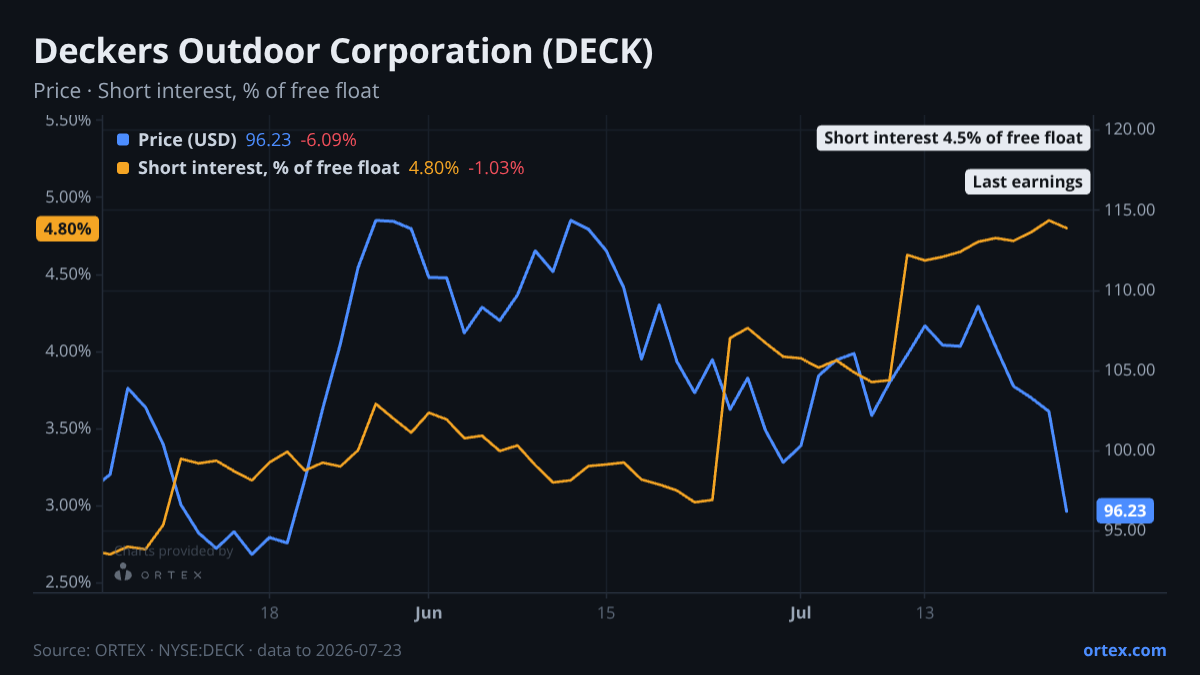
DECK reports again Thursday after a rough week that confirmed the bears' near-term concerns — the question now is whether the guidance picture has changed enough to matter.
The stock fell 6.3% after last Thursday's print and has shed nearly 10% on the week, closing Friday at $96.04. That reaction is the dominant new fact heading into the July 30 report. Options positioning has shifted sharply in response: the put/call ratio dropped to 0.74, almost 2.4 standard deviations below its 20-day average of 0.82. That reads as call-heavy, not defensive — a surprising tilt for a stock that just dropped hard, suggesting some traders are positioning for a bounce rather than bracing for further downside.
The analyst response to last week's miss was swift and uniform. Five firms cut price targets on Friday alone — Truist, Stifel, Barclays, Needham, and Baird all trimmed, though all but one maintained positive ratings. Truist cut its target from $125 to $105 while keeping Buy. Barclays came down from $141 to $133, staying Overweight. Telsey moved to $105 but held Market Perform. The consensus mean now stands at roughly $123, implying about 28% upside from current levels — that gap is wide, but it opened partly because the stock fell, not because targets moved up. The structural bull case remains intact on paper: Hoka's brand momentum, a multi-year framework targeting high-single-digit revenue growth, and a direct-to-consumer push. Bears counter with guidance that continues to disappoint relative to estimates, heavy brand concentration, and margin pressure from tariff exposure. The analyst recommendation score ranks in the 98th percentile versus the broader market — a factor score that reflects unusual divergence between the hold-heavy consensus and the bullish framing underneath it.
Short interest has remained elevated but is not accelerating. It held near 4.5% of free float heading into last week's print — up roughly 51% over the past month — and edged slightly lower in the sessions immediately around the event. Borrow conditions are entirely loose: availability runs at nearly 3,853% of short interest, and the cost to borrow sits at 0.44%. There is no squeeze pressure and no meaningful friction for new shorts, though the positioning data does not show a fresh wave of shorting after the post-earnings drop.
Thursday's print is less about whether Deckers can grow and more about whether management can deliver guidance that closes the gap between a $96 stock price and a Street consensus still anchored well above $120.
Against its peers
Shares moved -9.8% over the past week against a median of -2.3% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open DECK on ORTEX →How this article was generated
- Generated
- 27 Jul 2026, 04:07
- Data as of
- 27 Jul 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.