
Uber Heads Into Q2 Print with Options Traders More Defensive Than Usual
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
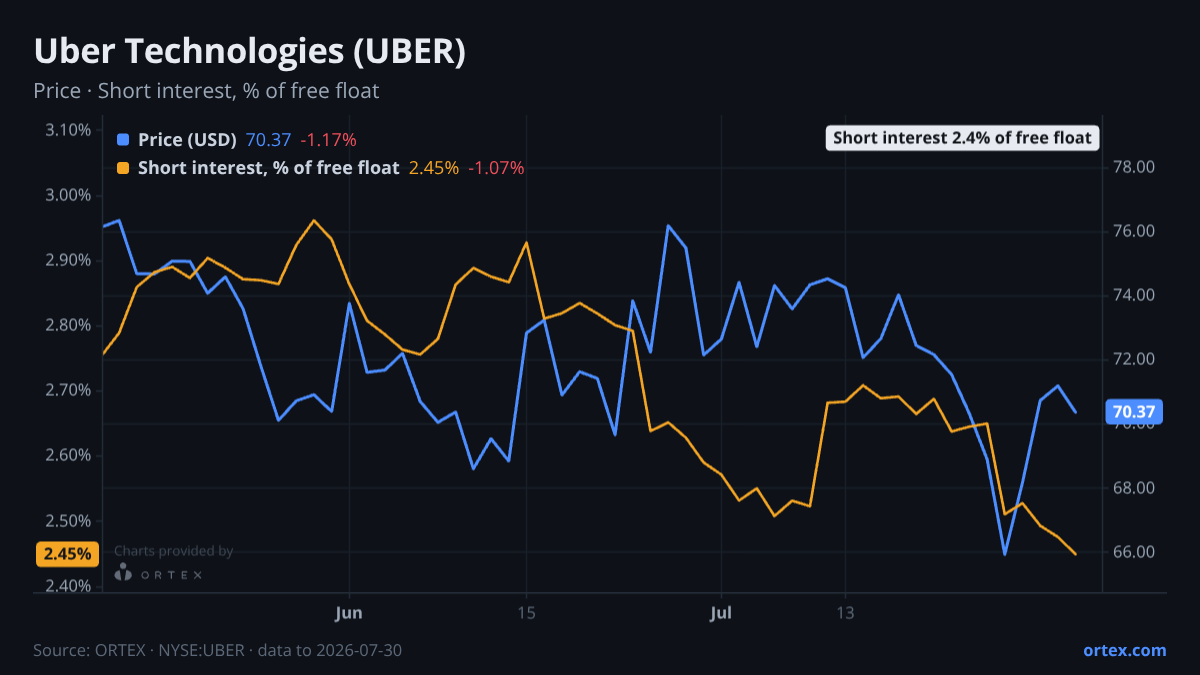
UBER reports Q2 results on August 4 with options positioning sharply more cautious than it has been all year — even as the short-selling community continues to back away.
The clearest signal heading into the print is in the options market. The put/call ratio jumped to 1.12 on July 31, nearly two and a half standard deviations above its 20-day average of 0.97 — the most defensive reading in the past 52 weeks aside from a single June spike. That demand for downside protection arrives after a mixed month for the stock: shares are down roughly 2.5% over the past month to $70.36, though they clawed back nearly 7% in the past week alone. The backdrop is a company that, after the last comparable quarterly print in May, rallied more than 5% on the day and held most of that gain over the following week.
Short interest tells a less aggressive story. Bears have been covering, not adding — short interest dropped over 7% across the past week and more than 12% over the past month, now running at just 2.4% of the free float. With availability at nearly 98 times current short interest, the lending market is about as loose as it gets. Borrow costs, while up roughly 18% on the week, remain negligible at 0.39%. There is no short-side pressure to speak of.
The bull-bear debate centers on whether Uber's expansion into 60-plus new markets via the Delivery Hero acquisition will compound the platform's existing momentum or simply import new regulatory and competitive headaches. Bulls point to 18% year-on-year revenue growth, rising forward EPS estimates, and a peer group struggling to keep pace — LYFT gained 10.9% on the week but has underperformed markedly in 2026, and GRAB is growing more slowly. Bears flag European regulatory risk, intensifying price competition, and a valuation that remains stretched: the PE stands near 17.8x and the quality-growth composite score, while strong at 69-70, carries a value pillar of just 36.8. The analyst community is broadly constructive — the mean price target of $103.89 implies roughly 48% upside from the current price — but BofA trimmed its target to $103 just days before the print while maintaining its Buy rating, and several other firms quietly shaved targets through July, suggesting growing selectivity rather than outright conviction.
The August 4 report is therefore less a test of whether Uber is growing and more a test of whether the Delivery Hero rationale holds water under scrutiny, and whether margin trajectory on the core business can justify a premium multiple while the options market is pricing in its most defensive stance of the year.
Against its peers
Shares moved +6.7% over the past week against a median of -1.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open UBER on ORTEX →How this article was generated
- Generated
- 1 Aug 2026, 04:26
- Data as of
- 1 Aug 2026, 04:06
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.