
MOD Shorts Jump 27% Ahead of Wednesday Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
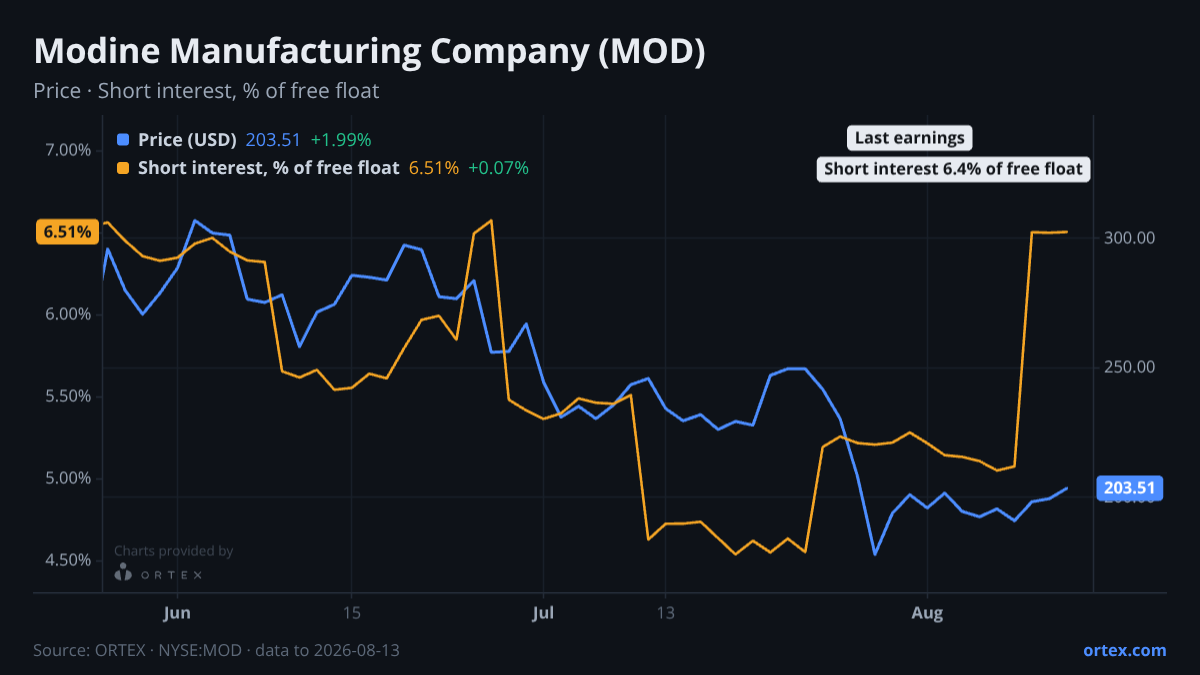
Modine Manufacturing heads into its August 20 earnings report with short sellers meaningfully more active than they were just two weeks ago — a setup that sharpens what is already a charged debate about supply chain risk versus data center growth.
The standout in the positioning data is how quickly bears have moved. Short interest climbed 27% over the past week to reach 6.4% of free float — a level that merits attention in its own right, but more notable for the speed of the move. The bulk of that increase happened sharply around August 10, when shares short jumped from roughly 2.6 million to 3.4 million in a matter of days. The lending market, however, is not tightening to match: availability remains extraordinarily loose at nearly 5,000% of short interest, and borrowing costs have actually fallen 25% over the past week to just 0.42%. That combination — rising short interest alongside easy, cheap borrowing — points to a considered bearish bet rather than a distressed squeeze setup.
Options positioning is calm by contrast. The put/call ratio of 0.59 sits barely half a standard deviation above its 20-day average of 0.57, and well below last year's high of 0.88. That tells a less alarmed story than the short interest data: options traders are not pricing in unusual downside risk ahead of Wednesday. The stock itself has had a volatile month — down 8.7% over 30 days but recovering 7.1% this past week to close at $209.50, suggesting the recent dip drew buyers back in.
The bull and bear debate heading into the print centers on a genuine operational split. Bears point to supply chain friction among Modine's 300-plus external data center components suppliers, a problem that materialized sooner than management guided, and a valuation that analysts peg at 20–22x FY28 EBITDA — stretched for an industrial. Keybanc trimmed its target to $280 from $370 following the most recent quarterly update, and B. Riley cut to $305 from $340, both maintaining positive ratings but signaling diminished conviction on near-term execution. The mean analyst target of $310 still implies roughly 48% upside from current levels, and bulls lean on the thesis that Modine's data center cooling franchise and CHVAC segment expansion give the company multi-year structural tailwinds that justify a premium. EPS growth expectations for the next 12 months rank in the 92nd percentile of the ORTEX universe, a strong fundamental underpinning even if momentum has softened of late.
Wednesday's print will test whether Modine can demonstrate that the supply chain headwinds are contained and temporary — or whether the bears who rushed to build positions over the past week are early to a more prolonged margin story.
Against its own history
This week's change in short interest is 3.6 standard deviations above the company's typical weekly move over the past year.
Against its peers
Shares moved +7.1% over the past week against a median of -1.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open MOD on ORTEX →How this article was generated
- Generated
- 17 Aug 2026, 04:02
- Data as of
- 17 Aug 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.