
BTI Options Turn Defensive Ahead of Tuesday's Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
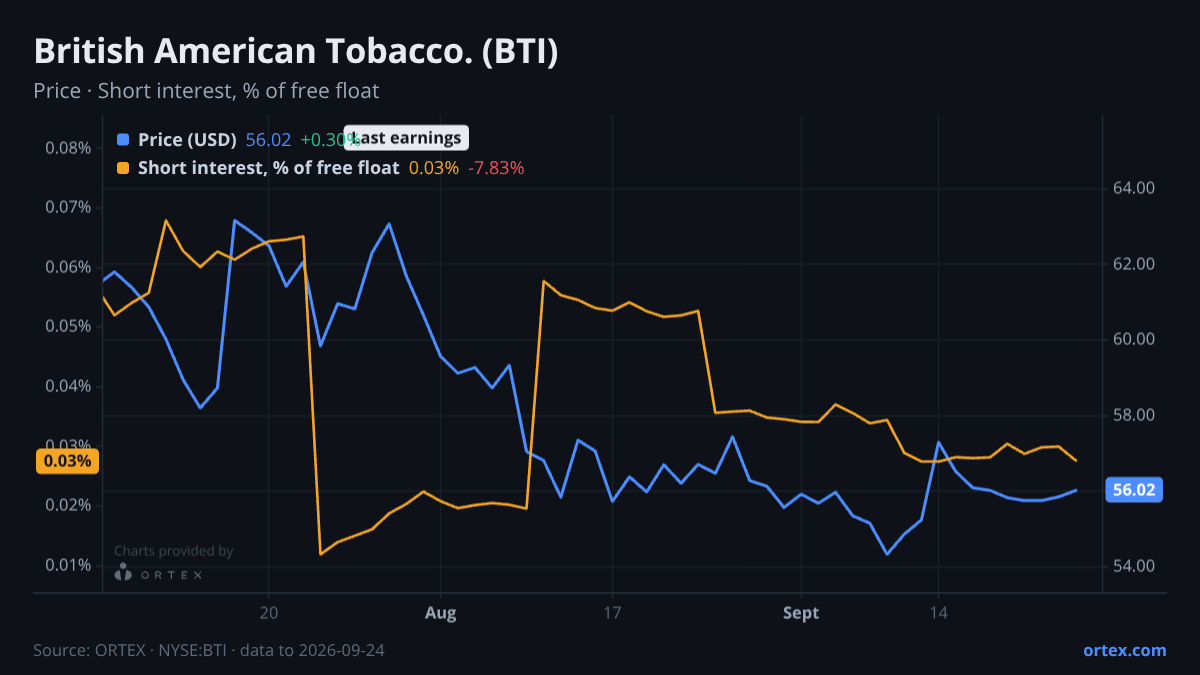
British American Tobacco heads into its September 29 results with options traders more cautious than they have been in months, even as short sellers continue to retreat.
The sharpest pre-earnings signal is in options positioning. The put/call ratio jumped to 0.61 on Thursday — more than two standard deviations above its 20-day average of 0.51, the most defensive reading relative to recent norms all year. That shift is notable because it arrived sharply and recently: the PCR had been running in the 0.46–0.50 range for most of September before spiking this week. Meanwhile the stock has drifted lower — down about 1.5% over the past month and fractionally softer on the week at $55.63 — adding a modest price-action tailwind to the defensive skew.
Short interest, by contrast, tells a much calmer story. Bears have been covering, not building. Short interest fell nearly 8% in a single session on September 24 and is down almost half from a month ago, now at roughly 2.8 million shares. The lending market confirms there is no meaningful squeeze dynamic at work: borrow availability is essentially unlimited, with no realistic constraint on new short positions for anyone who wanted them. Borrowing cost is negligible at 0.44%, barely changed week-on-week. The ORTEX short score of 25.9 is stable and unremarkable — this is not a stock where short-side pressure is building into the print.
The fundamental debate is well-worn. Bulls lean on the defensive income case: a dividend score in the 86th percentile, a PE around 11x, and a quality factor propped up by balance sheet metrics that remain competitive within tobacco. Argus Research upgraded to Buy about a year ago with a $62 target, and both Jefferies and UBS have moved to bullish stances in the past year or two — though no major firm has acted within the past two weeks. Bears point to structural deterioration: forward earnings are under real pressure, with the 12-month forward EPS growth trajectory ranking in just the 16th percentile across the universe, and the analyst recommendation differential sits in the bottom decile at a score of 5. The costly transition toward reduced-risk products is consuming capital while combustible volumes continue their long decline. The last major earnings event in late July resulted in a 3.8% one-day drop followed by a further 7% over the following five sessions — a pattern worth holding in mind.
Tuesday's print is less a test of whether BAT can sustain its dividend and more a test of whether management's next-generation product revenue can show enough momentum to justify the stock's current valuation without a further de-rating of the forward earnings outlook.
Stocks in this article
See the live data behind this article on ORTEX.
Open BTI on ORTEX →How this article was generated
- Generated
- 26 Sept 2026, 04:01
- Data as of
- 26 Sept 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.