
SLB Heads Into Q3 Print With Analysts Trimming Targets
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
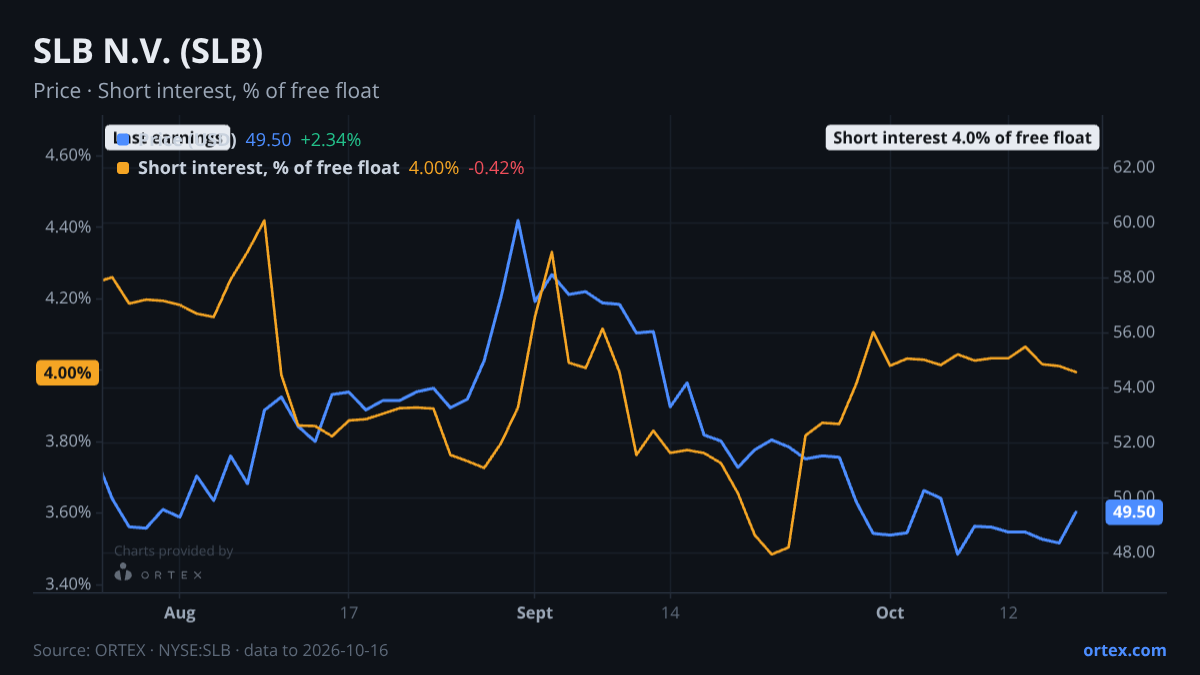
SLB reports Q3 results on October 23 with the analyst community broadly bullish but quietly walking back its price targets in the final days before the bell.
The most telling pre-print signal is the coordinated direction of analyst revisions. Citigroup lowered its target to $62 on Monday while holding its Buy rating. Piper Sandler trimmed to $63 the same day, also keeping Overweight. Barclays cut to $66 earlier in the week with an identical pattern: positive rating, lower number. The message from the Street is consistent: conviction in the long-term story remains intact, but near-term expectations are being dialled back. The consensus mean target of $62.34 still implies roughly 27% upside from the current price of $49.09, a gap that reflects either genuine undervaluation or lingering uncertainty about the pace of recovery.
The bull case rests on SLB's digital platform, which generated roughly $2.7 billion in revenue in 2025 with close to $900 million of adjusted EBITDA and a 35% margin, in a total addressable market management believes will expand from around $25 billion today to $35 billion by 2030. Bears point to a more immediate problem: continued Middle East disruptions dented Q2 guidance by $0.06 to $0.08 per share, North America is running flat sequentially, and the 2026 EBITDA estimate has been marked down to $8.0 billion against a prior Street consensus of $8.4 billion. That gap between digital ambition and near-term execution is the central tension heading into Thursday.
Short positioning and borrow conditions offer no additional pressure. Short interest is running at about 3.9% of the free float, and it has drifted lower over the past week, falling roughly 0.8% in that span. Borrow availability is exceptionally loose at 1,283%, meaning there are more than twelve shares available to lend for every one currently borrowed. Cost to borrow is just 0.52%, near multi-month lows. None of these readings suggest a community of traders making a high-conviction negative bet. Options positioning is similarly relaxed: the put/call ratio of 0.67 is modestly above its 20-day average of 0.64, barely one standard deviation away, well short of anything that would read as defensive hedging. The stock is down about 4% over the past month but recovered 0.7% on the week, broadly in line with the peer group, where HAL gained nearly 3% and BKR added 2.4%.
The last quarterly print in July produced a sharp 9% single-day gain that held over the following five days, the most recent entry in the earnings reaction history. That reaction followed positive revisions. The setup now is different: targets are moving lower into the print, not higher. The earnings report on Thursday is therefore less about whether SLB is growing and more about whether the digital segment and international volumes outside the Middle East can deliver enough to close the gap between management guidance and a Street that has spent the past week quietly reducing what it is willing to pay.
Against its peers
Shares moved +0.7% over the past week against a median of -1.0% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open SLB on ORTEX →How this article was generated
- Generated
- 20 Oct 2026, 04:07
- Data as of
- 20 Oct 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.