
AMKR drops 12% ahead of earnings as analyst cuts target to $46
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
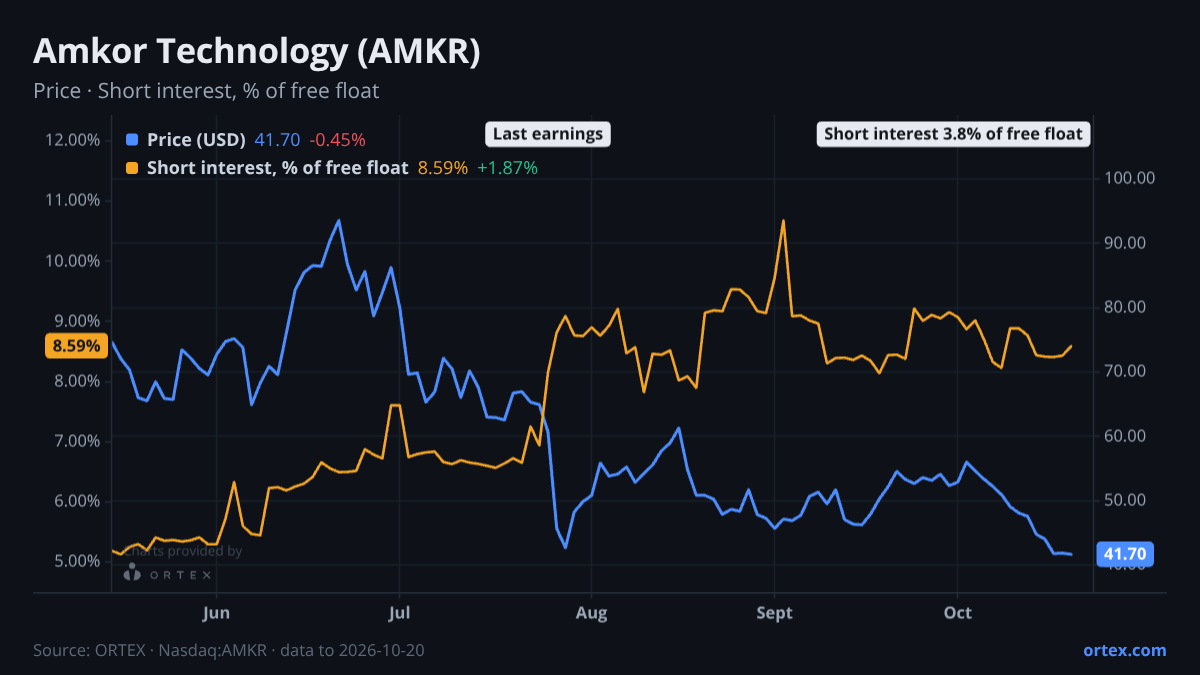
Amkor Technology fell 12.4% over the past week to close at $41.70, a sharper move than the median peer decline of 13.6%, as a same-day analyst target cut brought fresh attention to a stock already under pressure from a difficult July earnings print.
The most concrete signal this week came from B. Riley Securities. Craig Ellis cut his price target on AMKR to $46 from $65 on October 20, while holding a Neutral rating. That $46 target sits just 10% above the current price, the tightest gap in the analyst coverage tracked here. Elsewhere on the Street, the picture is more sanguine but dated. Bank of America initiated with a Buy in late August at a $70 target. Morgan Stanley raised its Equal-Weight target to $70 after the July print. Needham kept its Buy and its $90 target. UBS upgraded to Buy with a $90 target in late July. The consensus mean price target is $74.50, implying 79% upside from current levels. That gap between the consensus and today's price reflects how far the stock has fallen rather than a sudden outbreak of optimism: the bull case rests on AI and data center packaging demand and Amkor's Arizona facility investment, while the bear case flags reliance on foreign revenue and PC market softness. Valuation has compressed accordingly. The price-to-book multiple has dropped by roughly 0.5x over 30 days to 1.89x. The PE has contracted by nearly 3.9 points over the same period to 15.1x. The EV/EBITDA multiple of 5.6x has also drifted lower. Factor scores add nuance: the EV/EBIT score ranks in the 86th percentile, suggesting the valuation looks cheap against the universe on that measure, but 12-month forward EPS growth ranks in just the 15th percentile, and 30-day EPS momentum is in the 21st, both signals that estimate revisions have been moving the wrong way.
The positioning picture does not look charged. Short interest runs at 3.8% of the free float, about 9.3 million shares, and has eased roughly 3.3% over the week after ticking up modestly through September. The lending market reflects little urgency: borrow availability is at 4,020%, a level that means there is no shortage of shares to lend, with cost to borrow down 23% on the week to 0.39%. Neither the short interest level nor the borrow cost points to meaningful short pressure. Options tell a mildly more cautious story. The put/call ratio of 0.80 is about one standard deviation above its 20-day average of 0.75, an uptick in hedging demand that tracks the price weakness but falls well short of the 52-week high of 1.15. The ORTEX short score of 43.4 is in the middle of the range and has edged down slightly over the past week, not a setup that looks particularly squeezed or aggressively short.
The family ownership structure at Amkor is worth noting. John T. Kim holds a 13D position representing 30.4% of the class, last disclosed in May 2026, and the founding Kim family collectively controls a majority of the company through a cluster of registered holders. James Kim, Susan Kim, and related trusts account for well above 40% of shares held. BlackRock added just over one million shares in the most recent quarter to bring its stake to around 4.95%. Vanguard entities also added modestly. On the insider side, all recent transactions were made under pre-arranged 10b5-1 trading plans: the CFO sold 1,000 shares on October 13, and a Director sold and exercised in early October. Net insider activity over 90 days amounts to a modest sale of roughly 76,000 shares valued at about $4.2 million. These are plan-driven disposals, not discretionary signals of concern, but the absence of any open-market buying in the register is notable at a stock that has given up a significant portion of its 2026 gains.
The July print is the most relevant data point in the earnings history. The stock fell 29.7% the day after Q2 results and was still down 21.7% five days later, a reaction that reset the share price from above $50 to the mid-to-upper $30s before the recent partial recovery to $41.70. Q3 results are due October 26, five days from today. The peer group moved in a similar direction this week: COHU fell 16.0%, FORM fell 15.9%, ONTO dropped 16.7%, and LRCX declined 12.5%. ENTG held up better at minus 11.3% and KLIC at minus 9.2%. The sector-wide selling means that AMKR's move this week reflects broad semi equipment pressure rather than company-specific deterioration, but with the Q3 print five days out and the B. Riley cut now on record, the specific level to watch is the $46 target that currently represents the bear end of the formal analyst range.
Against its peers
Shares moved -12.4% over the past week against a median of -13.6% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open AMKR on ORTEX →How this article was generated
- Generated
- 21 Oct 2026, 18:07
- Data as of
- 21 Oct 2026, 18:02
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.