
Incyte Recovers Ahead of Earnings as Options Turn Defensive
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
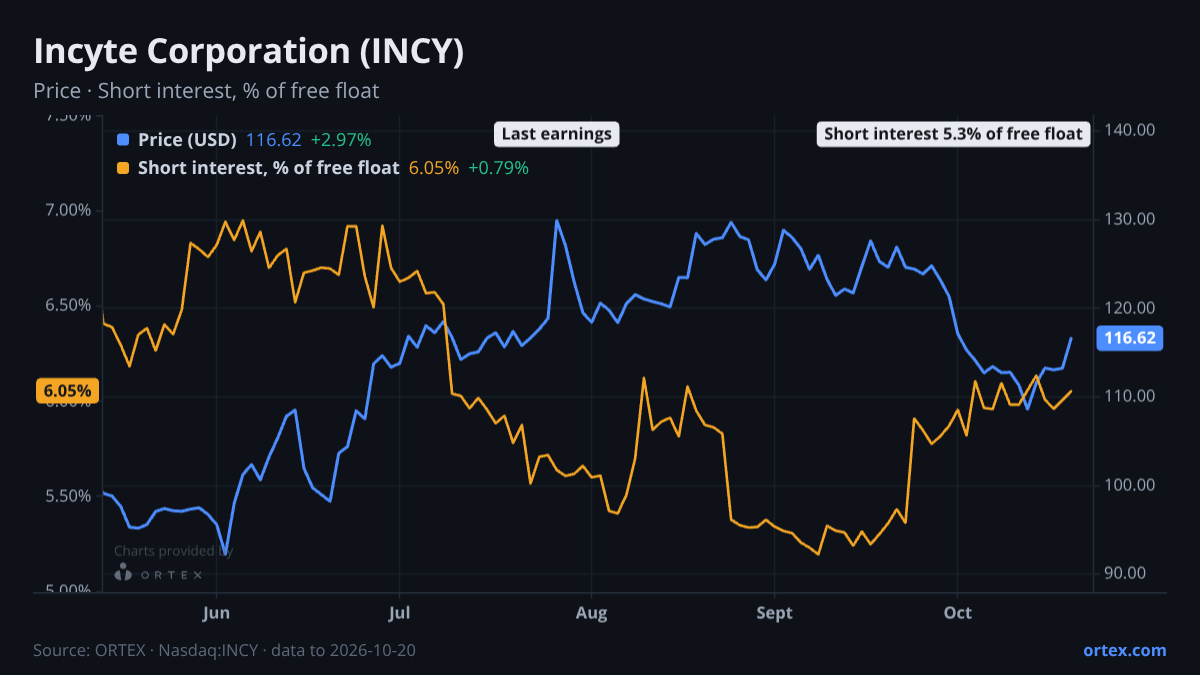
INCY gained 7.4% over the past week to $116.62, outpacing the median move of its closest biotech peers, but the recovery arrives with options positioning at its most defensive in months and short interest still rebuilding from September lows.
Among the correlated peer group, ORIC led with a 21.8% weekly gain and EXEL added 8.2%, while ABBV and VRTX both rose roughly 5 to 6%. INCY's 7.4% move places it comfortably in the upper half of the group, recovering ground after a month that had seen it fall nearly 7%. One week ago the stock was trading at $108.62; it has now recovered to $116.62 yet remains below where it started the month.
The clearest signal this week is in options, not borrow. The put/call ratio has climbed to 1.94, more than two standard deviations above its 20-day average of 1.75, and that gap is the widest it has been since September when the PCR ran above 2.2 for several weeks around that period's peak anxiety. The 52-week range on the ratio runs from 0.44 to 2.52, so the current reading is elevated but not at extremes. Demand for downside protection has picked up even as the stock itself has rallied, a combination that points to investors hedging an uncertain earnings outcome rather than expressing conviction in either direction. The next print is October 27.
Short interest continues its slow rebuild, but it is not the dominant story. The position has risen about 14% since mid-September to reach 5.25% of the free float, adding roughly 1.2% on the week. That month-long drift higher is worth noting, but the lending market provides no support for any squeeze narrative. Availability is extraordinarily loose at 3,614%, meaning there are roughly 36 shares available to borrow for every one already lent out. Even at the tightest point of the past year, availability never fell below 1,237%. The cost to borrow has slipped 25% over the week to 0.39%, cheap in any context. Positioning looks cautious rather than crowded: the put/call ratio is the active signal, short interest is a slow-building background note.
The Street has been incrementally more constructive through October. TD Cowen lifted its target to $140 from $138 today while keeping its Buy rating, and Stifel raised to $157 from $145 earlier in the month, both citing the Jakafi franchise and Opzelura's growth trajectory. Truist lifted its Hold target to $115 from $105, while RBC moved its Sector Perform target to $114 from $109. The consensus price target stands at $129.58, about 11% above the current price. Bulls point to the KRAS G12D data from INCB161734, where 33 of 48 previously untreated patients responded across chemotherapy combinations, and to Opzelura potentially approaching $0.9 billion in sales as a dermatology anchor. Bears focus on Jakafi's 2028 patent expiry and the risk that lifecycle-extension assets in myelofibrosis face a high competitive bar. The stock's EPS momentum ranks in the 90th percentile on a 90-day basis and the 80th percentile over 30 days, with EPS surprise at the 79th percentile, suggesting the fundamental trend has been running ahead of expectations coming into this quarter.
Felix Baker holds a Schedule 13D position at 15.6% of the company, down marginally from 15.7% at the prior filing in May, making him the single largest shareholder and an active 13D filer on the register. Baker Bros. Advisors holds a further 15.3% as reported at September quarter-end, a stake it added to by 312,565 shares in the period. BlackRock, Vanguard Capital Management and Dodge and Cox each hold between roughly 6 and 9%, rounding out a concentrated top-five ownership base. The recent insider record is mechanically driven: the only open-market-equivalent activity is a series of 10b5-1 plan transactions by the President of Global R&D in mid-October, all small and pre-arranged, with a net selling bias across the 90-day window of roughly $9.2 million in value.
The July earnings print moved the stock nearly 7% higher on the day, the only recent data point available, though it settled to a 1.5% gain by the five-day mark. With the October 27 date six days away, the question is whether a repeat of that post-print relief is priced in by the put/call elevation, or whether the options hedging reflects genuine uncertainty around Opzelura trajectory and any pipeline update on INCB161734 ahead of what the Street regards as a pivotal 2027 to 2028 window for the company's revenue base.
Against its peers
Shares moved +7.4% over the past week against a median of +6.1% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open INCY on ORTEX →How this article was generated
- Generated
- 21 Oct 2026, 18:32
- Data as of
- 21 Oct 2026, 18:31
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.