
PSA Leads Self-Storage Peers Into Earnings, but Analysts Turn Cautious
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
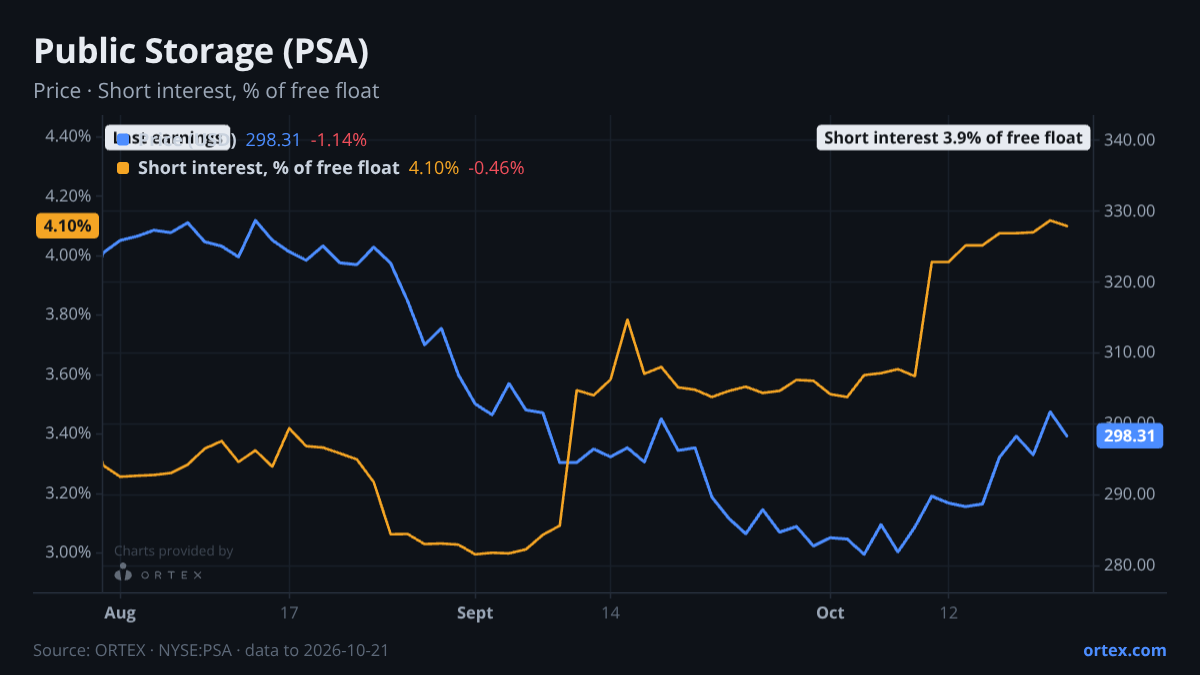
Public Storage gained 4.7% over the past week, outpacing the median weekly move of roughly 2.1% for its closest peers, with closest self-storage rivals EXR and CUBE adding 4.3% and 3.3% respectively. The stock closed Thursday at $309.13, up more than 4% on the month, making it one of the stronger performers across the REIT complex in recent sessions. Yet that relative strength sits in some tension with what analysts have been doing ahead of Sunday's print.
The analyst community has been trimming targets, not raising them. UBS cut its price objective to $294 from $326 on October 16, a meaningful step that pushed the target below the current share price. JP Morgan moved lower too, from $338 to $330 in September, while Truist Securities cut its Buy-rated target from $338 to $317. RBC held its Sector Perform rating and a $318 target unchanged. Only Barclays and Mizuho moved targets upward, and only modestly. The Street's mean target now sits at $329, which implies limited upside from current levels. The cluster of cuts suggests that while nobody is turning outright negative, there is a growing sense that the stock has run into its fair value range.
Options positioning reinforces that measured caution. The put/call ratio of 1.97 is above its 20-day average of 1.84, a level that has run structurally elevated for most of the past month, with brief spikes above 2.2 in mid-October. At the same time, the lending market carries none of the tension typical of a heavily contested stock. Borrow availability is extremely loose, with roughly 1,316% availability, meaning there are roughly 13 shares available to lend for every one currently borrowed. Cost to borrow has eased nearly 20% over the past month to just 0.36%. Short interest of about 3.9% of the free float has crept up roughly 8% over the past month but remains well short of levels that would suggest a crowded short thesis.
The bull case centres on Public Storage's position as the dominant US self-storage REIT, with improving move-in rates, resilient occupancy, and potential pricing power recovery as housing affordability constraints sustain demand. The bear case points to uncertainty around supply growth, capital needs following the National Storage Affiliates acquisition, and guidance that remains marginally below prior consensus. Institutional ownership is dense and stable, with BlackRock, the Vanguard entities and Capital Research all holding above 5%, and Capital Research notably adding more than 3.3 million shares in the most recent quarter.
The October 26 print will test whether Public Storage's operational momentum, particularly the trajectory of move-in rates and occupancy trends, justifies a stock that has recovered sharply from oversold territory but now trades in line with or above most analyst price targets.
Against its peers
Shares moved +4.7% over the past week against a median of +2.1% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open PSA on ORTEX →How this article was generated
- Generated
- 23 Oct 2026, 04:08
- Data as of
- 23 Oct 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.