
Novartis Options Skew Hits Near-Yearly Extreme Before Q3 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
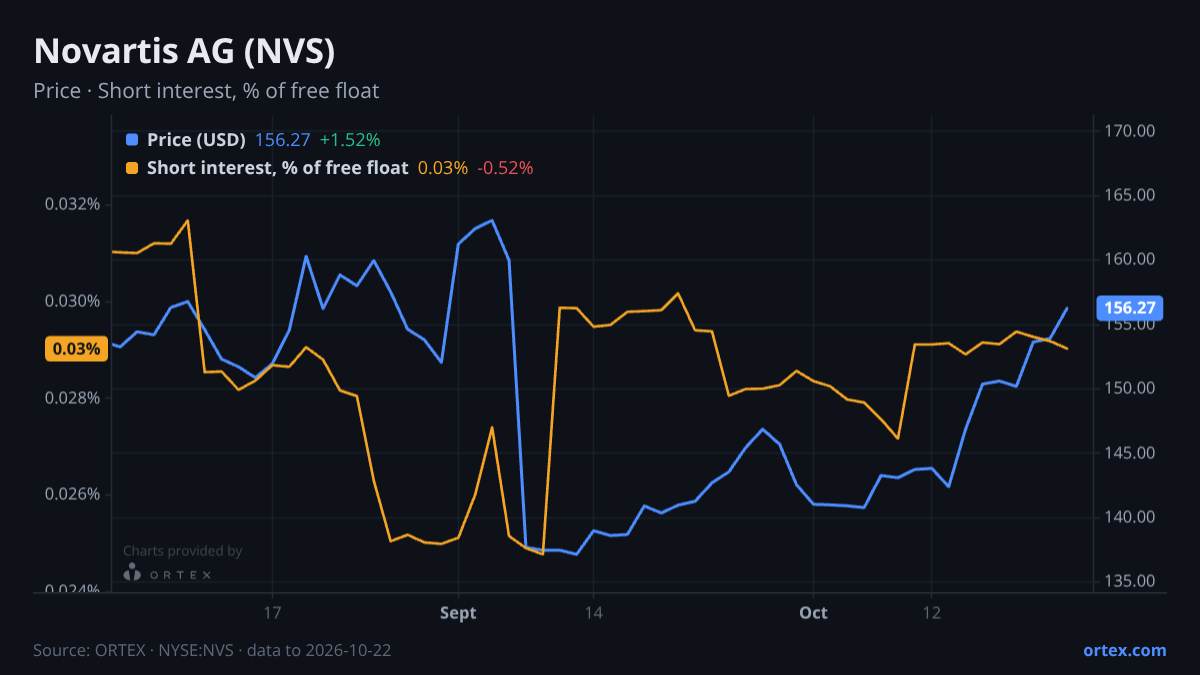
The most striking data point around NVS's October 27 results is not its short book, which is modest, but the put/call ratio, which has jumped to its highest level in nearly a year.
Options positioning has turned sharply defensive. The PCR closed Thursday at 2.32, almost three standard deviations above its 20-day average of 1.99, making it the most extreme defensive reading since the 52-week high of 2.56. That kind of skew reflects concentrated demand for downside protection ahead of the print, not a routine hedge. It arrived on the same day the stock fell 3.3% to $151.12, erasing a week of gains in a single session, even as the one-month trend remains up nearly 7%.
The short-selling picture, by contrast, looks calm. Shares short total roughly 5.4 million, a small fraction of the float for a $296 billion company, and the lending market is far from stressed. Borrow availability runs at more than 2,000%, meaning there are roughly twenty shares available in the lending pool for every one currently borrowed. Borrowing costs are low at 0.42%, though they have risen about 37% over the past week from a very low base. This is not a stock under short-seller pressure; the options skew is doing something else entirely.
Analyst opinion has divided meaningfully over the past year. Morgan Stanley raised its target to $170 in March while keeping an Overweight rating. HSBC upgraded from Reduce to Hold in September, lifting its target to $136. That contrasts with Goldman Sachs, which cut to Sell in September 2025 with a $118 target, a call that looks offside against the current $151 price. The stock's valuation sits at roughly 16 times trailing earnings with an EV/EBITDA near 13. Those are not demanding multiples for a large-cap pharma franchise, but Goldman's bear case appears to centre on whether the pipeline can sustain that growth premium.
The company's own recent note gives some grounding: Novartis reported Q3 revenue of 9.3 billion Swiss francs, up 5% year-over-year, with oncology and emerging markets as the drivers. Full-year guidance was maintained, and analysts lifted near-term earnings estimates on the operational efficiency beat. The earnings track record adds texture: the July 2026 print produced a 2.4% one-day gain and a 6.9% five-day rise, while the April print saw a modest one-day dip of 0.9% before recovering.
The October 27 print will test whether the operational momentum Novartis described in its July release has carried into Q3, and whether the aggressive put positioning heading into the close on Thursday reflects a specific concern or simply pre-earnings caution from a holder base that bought the September rally.
Stocks in this article
See the live data behind this article on ORTEX.
Open NVS on ORTEX →How this article was generated
- Generated
- 24 Oct 2026, 04:09
- Data as of
- 24 Oct 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
- Validation notes
- soft: missing section mentions: short interest (informational only)
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.