
RCL Trails Peers on Short Pressure, Analysts Stay Bullish
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
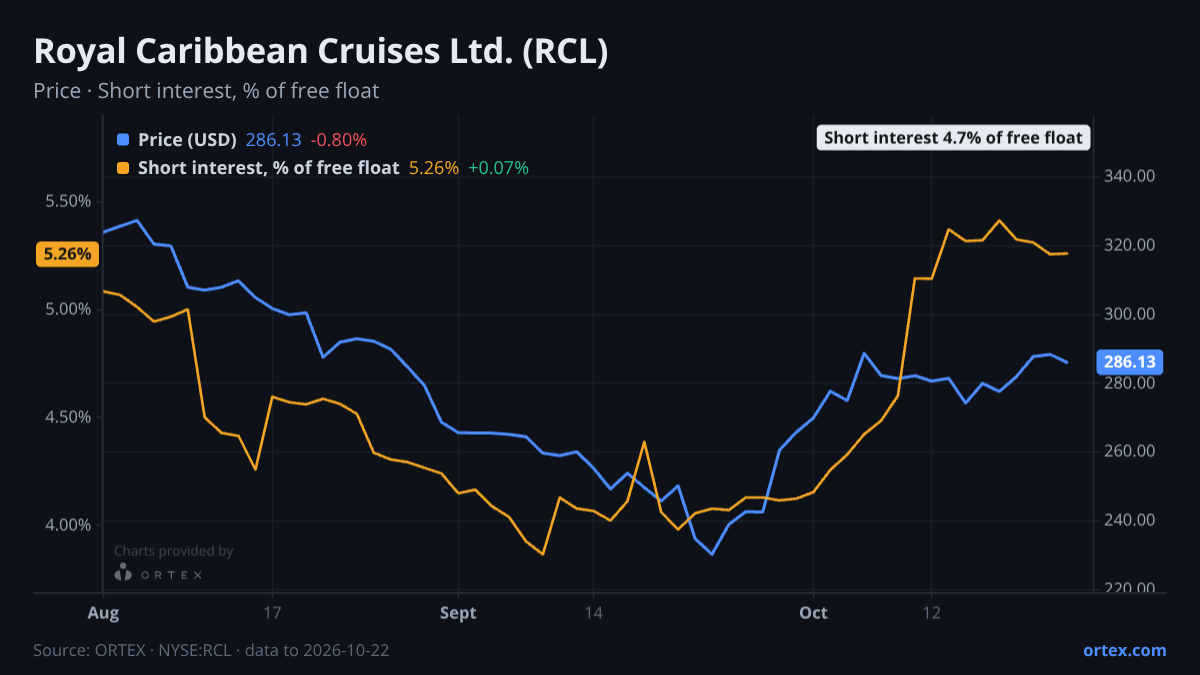
Among the major cruise operators heading into Tuesday's print, RCL is one of the lighter-shorted names in the group. Short interest at CCL and NCLH runs closer to their respective highs, while Royal Caribbean's short interest holds at 4.7% of free float, modest by sector standards and down roughly 1% over the past week despite a 28% build over the past month.
That month-long accumulation in shorts is worth context. In late September, short interest was running near 9.6 million shares. By mid-October it had climbed above 13 million before easing slightly in recent sessions to approximately 12.7 million. The borrow market offers no amplifying pressure: availability is exceptionally loose at over 1,600%, meaning roughly 16 shares are available to borrow for every one already lent out, well above even the 52-week floor of around 792%. Borrowing costs remain negligible at 0.54%. The short interest build appears to reflect a considered view rather than a squeeze-driven unwind risk.
Options positioning has drifted modestly more defensive. The put/call ratio stands at 1.03, above its 20-day average of 0.96, though the z-score of 0.85 keeps this well within normal territory. The stock fell 3.4% on Friday to $276.48, lagging peers: CCL dropped 3.6%, NCLH fell 2.8%, VIK lost 3.2%, and NCLH companion LIND shed 2.9%. Over the week, RCL's 0.4% decline roughly matched the sector median, leaving its 17.7% one-month gain intact.
The analyst community remains firmly constructive, though several desks trimmed targets in the run-up. Wells Fargo cut to $358 from $388 on October 12, and Susquehanna moved to $355 from $372 on October 20, both while keeping positive ratings. TD Cowen, by contrast, edged its target up to $340 from $337. The mean target of $350 implies roughly 27% upside from current levels. Jefferies upgraded to Buy on October 8, lifting its target to $330 from $305 after a Hold stance. The direction of travel is positive but the target reductions from Wells Fargo and Susquehanna suggest some near-term caution on the pace of margin delivery. The analyst recommendation differential factor ranks in the 100th percentile of the ORTEX universe, an unusually clean sweep of constructive ratings, though the EV/EBIT score ranks in only the 35th percentile, a reminder that valuation is not a tailwind. The PE multiple has expanded roughly 2.6 points over the past month to 14.4x alongside the stock's rally.
One ownership detail stands out. Capital Research and Management holds approximately 29.4% of shares, a dominant position that has grown by around 4 million shares in the most recently reported quarter. No 13D activist is on the register. The prior quarterly print in late July produced a 6.1% one-day gain and extended to 6.8% over five sessions, the only recent data point in the earnings reaction history.
The October 27 release will test whether the month-long accumulation in short interest reflects a genuine earnings-risk view or simply pre-event hedging that reverses once the guidance picture clarifies.
Against its peers
Shares moved -0.4% over the past week against a median of -0.3% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open RCL on ORTEX →How this article was generated
- Generated
- 24 Oct 2026, 04:15
- Data as of
- 24 Oct 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.