
PayPal Options Turn Bullish Days Before Q3 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
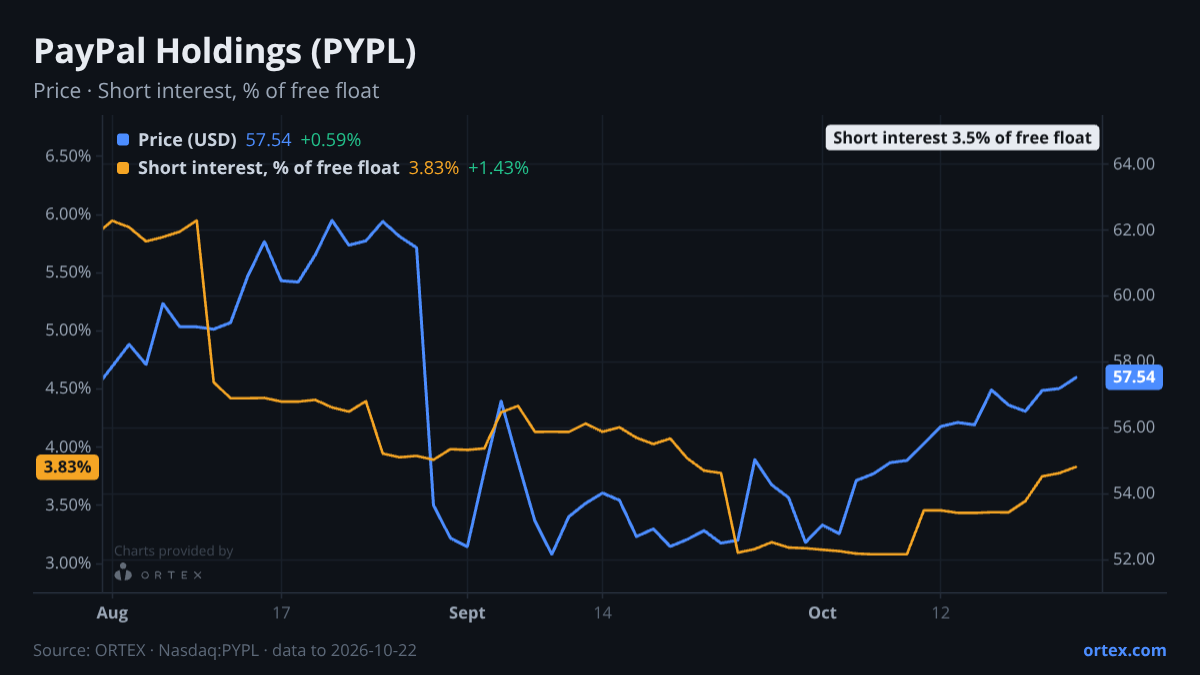
PayPal reports Q3 earnings on October 27 with the stock up just 0.6% over the past week, a soft showing against a median gain of 3.0% across its closest payments peers, as the company faces an ongoing debate about whether its core business can defend margin while growth in branded checkout slows.
Options positioning has shifted notably into the print. The put/call ratio is 0.34, near its 52-week low of 0.34 and well below its 20-day average of 0.37, almost 1.4 standard deviations light on puts relative to recent norms. That makes this one of the most call-heavy configurations of the past year, suggesting traders are positioned for an upside move rather than hedging against a disappointment. The lending market adds little drama: short interest is 3.5% of the free float, up 11.5% over the past week but still modest in absolute terms. Borrow availability remains extremely loose at 3,117%, meaning there is roughly 31 times as much stock available to lend as there is currently short. Cost to borrow is just 0.39%, near its lowest level in months. None of those signals point to a crowded short trade.
The fundamental debate is narrower than the options positioning might imply. Bulls point to PayPal's 439 million active accounts and its ownership of Venmo, Braintree and a buy-now-pay-later suite as durable monetisation levers, alongside a $1.5 billion run-rate cost reduction that management is pursuing to protect margins. Bears counter that branded checkout continues to lose ground to Shop Pay and Apple Pay, and the Q1 data underscores the tension: total payment volume rose 11% but transactions per active account fell 1%, and non-GAAP operating margin compressed by 229 basis points to 18.4%. The analyst community reflects the same split. Truist raised its target to $58 from $53 on October 23 while keeping a Hold rating. The mean price target across the consensus is $56.89, barely above the current price of $57.02, consistent with a Street that sees the stock as fairly valued rather than a clear buy. RBC stands out as the most constructive, at a $70 Outperform target set in August, but the dominant tone is neutral.
Retail attention is one signal worth noting, even if it is not a leading revenue indicator. Wikipedia views and ORTEX page-traffic data put retail attention at a z-score of 2.98 relative to the prior 90 days, close to three standard deviations above normal, a level of interest that rarely accompanies indifference to the print.
The October 27 release will test whether PayPal's Q3 efficiency improvements were enough to offset branded checkout pressure, and whether a transactions-per-account trend that was negative in Q1 has turned.
Against its peers
Shares moved +0.6% over the past week against a median of +3.0% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open PYPL on ORTEX →How this article was generated
- Generated
- 24 Oct 2026, 04:28
- Data as of
- 24 Oct 2026, 04:02
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.