
NiSource Shorts Build Ahead of Q3 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
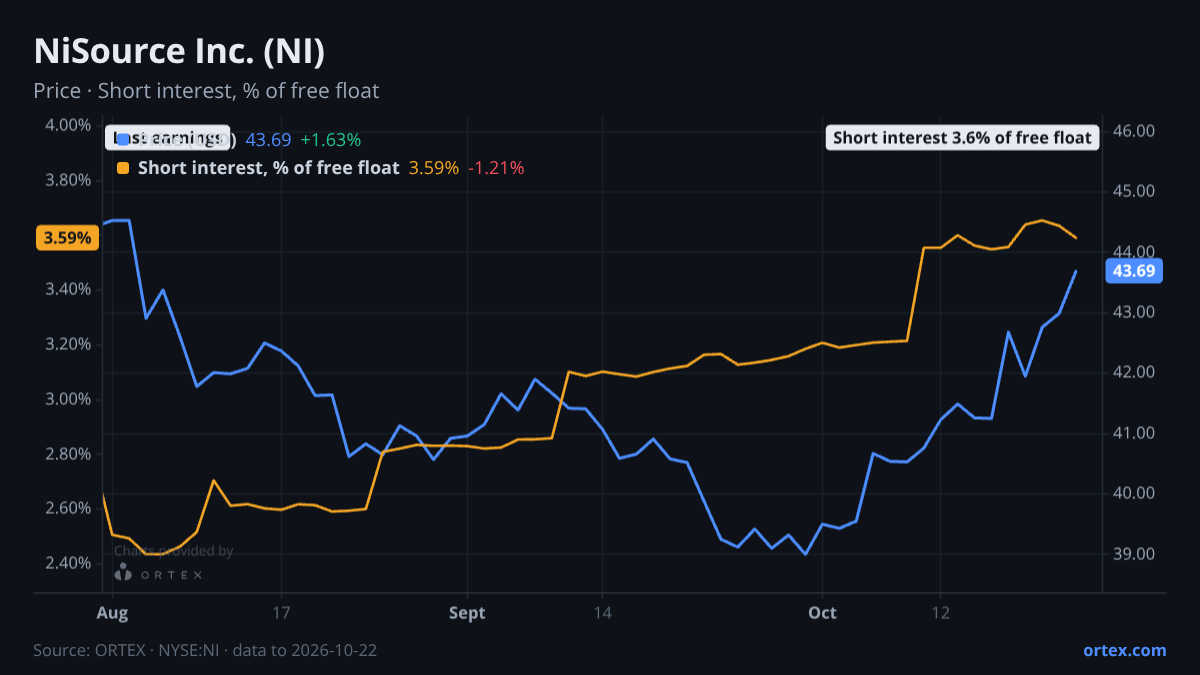
NiSource, the Indiana-based gas and electric utility, reports third-quarter results on October 28 against a backdrop of steadily rising short positions and a fresh wave of analyst target trims that have left the consensus target well above the current share price.
Short interest has climbed roughly 16% over the past month to 3.6% of the free float, the highest level in at least a year. That accumulation is not matched by any sign of stress in the lending market: borrow availability is extraordinarily loose at over 4,100% of the shares already shorted, and the cost to borrow has drifted lower over the past week to 0.54%. Options positioning adds little alarm either. The put/call ratio is 0.30, fractionally below its 20-day average and well short of any defensive extreme. NiSource edged up 1.4% on the week, broadly in line with the 1.3% to 3.1% gains posted by closest peers CNP, AEE, WEC and ED, so the short build is a sector-wide theme rather than a stock-specific call against NiSource.
Analyst activity in the past two weeks has been notably one-directional on price targets, even as the underlying ratings have held. JP Morgan kept its Overweight rating but trimmed its target to $51 from $52. Barclays maintained Overweight yet cut to $44 from $45. Citigroup, at Neutral, dropped its target by $4 to $45. Only BMO Capital moved in the other direction, lifting its Outperform target to $48 from $45. The one fresh voice is HSBC, which initiated coverage this week with a Buy rating and a $49.50 target. The mean target across the analyst group now sits at $48.09, implying roughly 11% above the October 23 close of $43.28. The disagreement is less about direction than about how much premium NiSource deserves: bulls point to an expanding generation business and data center demand growth, while the more cautious view centres on execution risk in Indiana's electric rate case, affordability pressure where the company already runs the highest investor-owned utility rates in the state, and ongoing costs from its coal retirement programme.
One alt-data reading is worth noting without being overread. The EPA's Clean Air Markets Program Data shows that NiSource's gross capacity factor by operator in June 2026 was the lowest on record since 2024, at 35.41%. That is a generation-efficiency metric from a dataset that has not been measured as a lead for the company's reported financials, so it describes the physical operation of assets rather than offering a guide to the coming print.
The insider record over the past 90 days leans negative in dollar terms, with open-market sales by the EVP and Group President and the CEO totalling over $2.5m at prices in the high $40s, all without declared 10b5-1 plans. Those trades were transacted above the current share price. Institutional ownership is stable: BlackRock added 3.5m shares to its position as of September 30, bringing its stake to 11.5% of shares outstanding.
The October 28 print will test whether NiSource's rate-case and capital-programme execution has kept pace with a forward earnings trajectory that the company's own 12-month EPS growth estimate puts in the 97th percentile of the universe, and whether the premium embedded in its valuation is one the results can defend at $43.
Against its own history
Short interest is at its highest level in at least a year.
Against its peers
Shares moved +1.4% over the past week against a median of +1.5% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open NI on ORTEX →How this article was generated
- Generated
- 25 Oct 2026, 04:07
- Data as of
- 25 Oct 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.