
Generac Options Turn Bullish While Analysts Trim Targets
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
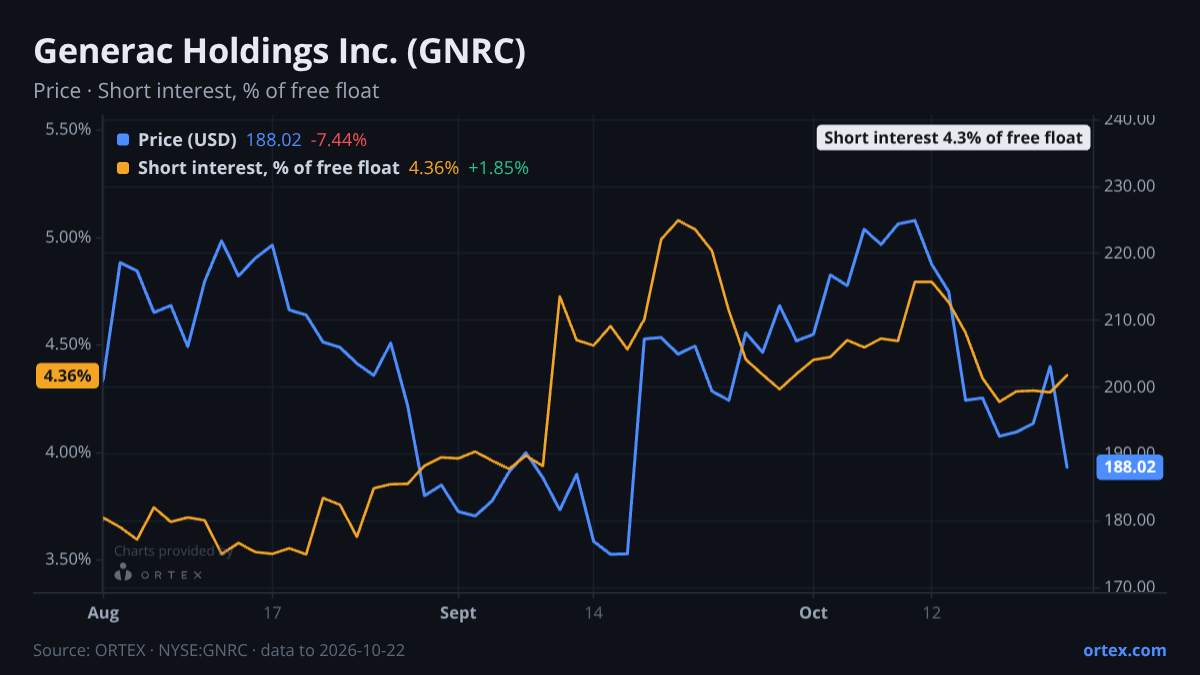
GNRC reports Q3 results on October 28 with the options market flashing an unusually bullish lean, even as analysts have been cutting price targets and the stock has retreated 9% over the past month to $186.92.
The clearest signal is the put/call ratio, which has dropped to 0.91, nearly 1.5 standard deviations below its 20-day average of 0.99. That is the lowest defensive reading in the 52-week range, which runs from 0.52 to 1.08. Two weeks ago the PCR was above 1.06, meaning call demand has accelerated sharply as the stock sold off, a divergence that is either contrarian conviction or pre-earnings positioning for a bounce. The broader lending market reinforces the lack of bearish pressure: availability is ample at roughly 4,580%, meaning there are far more shares available to borrow than currently borrowed, and cost to borrow is negligible at 0.49%. Short interest at 4.3% of the float is modest and has been declining over the past month. The ORTEX short score of 35.4 is in the lower half of the universe and has eased from 36.9 two weeks ago, confirming that the short book is not building into this print.
The analyst picture is more conflicted. The bull case rests on the Amazon long-term supply agreement, which backs up to $8 billion over seven years with 50% take-or-pay economics, and points to roughly $3 billion to $3.2 billion in data-center revenue by 2028. Keybanc upgraded to Overweight in early October, and JP Morgan raised its target to $265 in September. The bear case is grounded in execution: capacity constraints, tariff exposure, and alternator supply issues could force the company to leave revenue on the table, while the core home standby business remains hostage to the frequency of meaningful outage events. Piper Sandler initiated at Overweight with a $303 target on October 8 and then trimmed that to $279 just two weeks later, citing those same execution risks. Citigroup cut its target from $300 to $232 on September 30 while staying Neutral. The consensus mean target of $286 sits about 53% above the current price, a gap that reflects genuine disagreement about whether Generac can convert contracted demand into margin-accretive revenue.
GNRC fell 1.9% on the day of its July print, then recovered 11% over the following five sessions, suggesting the market has been willing to look through initial disappointment when the forward narrative holds. Against that, the stock's weekly move of minus 3% compares favourably to close peers: NVT fell 11.7% on the week, BE dropped 12.7%, and FPS lost 23.5%, making Generac's relative resilience notable. CEO Aaron Jagdfeld sold 5,000 shares at $206 on October 1 under a pre-arranged 10b5-1 plan, a routine mechanism that limits the signal. The institutional register is stable, with Vanguard and BlackRock together holding roughly 14% and both adding modestly in the September quarter.
The October 28 print is therefore a test of whether Generac can demonstrate that the Amazon agreement is translating into real production progress, and whether data-center margins are tracking toward the 2027 targets that underpin the wide gap between the current share price and where analysts have their targets set.
Against its peers
Shares moved -3.0% over the past week against a median of -7.5% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open GNRC on ORTEX →How this article was generated
- Generated
- 25 Oct 2026, 04:16
- Data as of
- 25 Oct 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.