
Shorts Add to a Rising Stock as Analysts Chase ServiceNow Higher
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
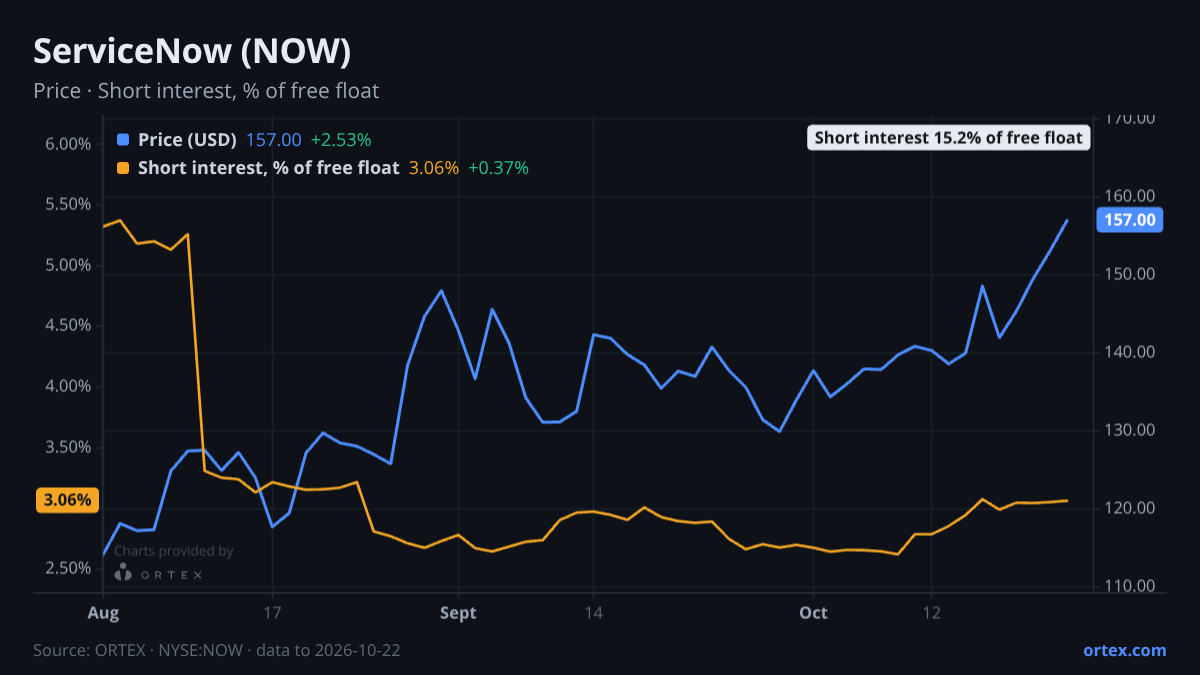
ServiceNow is not the most shorted name in its software peer group heading into Wednesday's print, but it is the one where the short rebuild has been most persistent: SI has climbed to 15.2% of the free float, up from 14.1% a month ago, while peers like ASAN and APPN have surged 22% and 27% on the week, drawing more speculative attention elsewhere. NOW itself gained 12% over the past week, slightly ahead of the peer median near 10.5%.
The short rebuild is notable precisely because it has run against a rising stock. Short interest has added roughly 2.9 million shares over the past month, reaching 31.6 million shares as of October 22. That accumulation has happened even as the stock has moved from the low $130s toward $159. The ORTEX short score has drifted higher to 32.8, its firmest reading in the current series, though still a moderate level in absolute terms. Borrow conditions impose no pressure on that positioning: availability is extremely loose at 4,838%, with borrowing costs near 0.46%, and the 52-week peak utilization was only 7%. Shorts face no meaningful cost to holding their position.
Analysts have responded to the same rally by chasing targets higher. Across October, every recent rating action has been a raise, with targets now clustered between $160 and $190. Guggenheim lifted its target to $175 on Thursday. Wells Fargo moved furthest, to $190. The consensus mean now sits around $157, essentially at the current price, meaning the Street's formal upside case has already been consumed by the recent move. The bull argument centres on ServiceNow's expansion beyond IT service management into HR and customer workflows, with FY25 NNACV growth of 9% and a path to subscription revenue growth above 17% by FY27. The bear case is more pointed: the company posted its largest ever sequential decline in Contracted Remaining Performance Obligations, with Federal obligations down 49% sequentially and 72% year-on-year, raising questions about whether enterprise demand outside the Federal channel can absorb that gap.
Past earnings reactions offer one calibration point. After the July 2026 print, the stock fell roughly 10% on the day before recovering 13% over the following five days. That sequence, a sharp initial drop followed by a recovery, reflects a pattern where the headline number disappointed but the forward commentary reassured. Options positioning is only mildly more cautious than usual: the put/call ratio is 0.93, about one standard deviation above its 20-day mean, well below the 52-week high of 1.17. That suggests hedging activity without genuine alarm.
The print will test whether CRPO can recover from its record sequential decline, and whether Federal weakness has stabilised or widened further into the broader enterprise book.
Against its peers
Shares moved +12.0% over the past week against a median of +10.5% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open NOW on ORTEX →How this article was generated
- Generated
- 25 Oct 2026, 04:17
- Data as of
- 25 Oct 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.