
MPWR Options Traders Turn Cautious Before Wednesday's Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
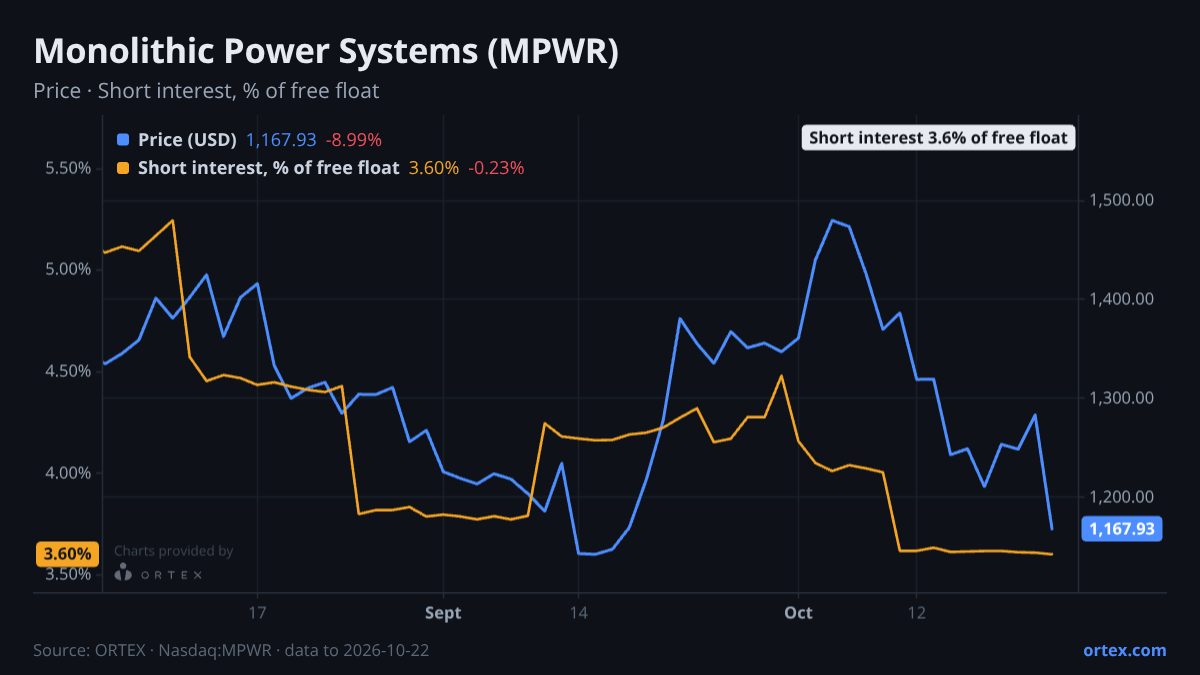
Monolithic Power Systems reports Q3 results on Wednesday after markets close, with options positioning the clearest signal of how investors are leaning into the event.
Put demand has climbed noticeably ahead of the print. The put/call ratio reached 1.21 on Friday, almost 1.8 standard deviations above its 20-day average of 1.09. That is the most defensive options posture the stock has carried in some time, though it remains well below the 52-week peak of 1.82, so the hedging is elevated rather than extreme. The move coincides with a difficult month for the shares: MPWR closed at $1,140.12 on Friday, down 17% over the past 30 days and 5.8% on the week, a steeper decline than the median peer move of roughly 2.2%. Close peers LSCC and MTSI also fell sharply on the week, off 7.2% and 9.9% respectively, suggesting sector-wide pressure rather than stock-specific selling.
The short-selling picture is less dramatic. Short interest amounts to 3.6% of the free float, down 13% over the past month as some bears have covered into the weakness. Borrow costs remain low at 0.46% annually, and share availability is effectively unlimited, making a squeeze dynamic irrelevant to the setup. The ORTEX short score of 33.8 is also unremarkable and has barely moved over the past two weeks, confirming there is no meaningful build-up of new short conviction going into Wednesday.
The analyst community is broadly constructive but has been trimming expectations. Oppenheimer and Wells Fargo both cut price targets this week, to $1,500 and $1,550 respectively, while maintaining positive ratings. TD Cowen also lowered to $1,700. The consensus target of $1,800 still implies substantial upside from current levels, but the direction of travel is clearly downward. The bull case rests on MPWR's proprietary BCD technology and its exposure to AI data centre power demand, where Enterprise Data revenue reportedly grew 164% year over year and management had raised its 2026 growth outlook to 130%. Bears point to the concentration of that growth in a handful of hyperscaler customers, with 90% of revenue flowing through distributors and each day of inventory representing an $11 to $12 million revenue swing. The EV/EBITDA multiple near 27.7 leaves little room for guidance disappointment.
On the ownership side, CEO Michael Hsing sold approximately $40 million of stock on September 28 across multiple tranches, all executed under a pre-arranged 10b5-1 plan. Planned sales carry less signal than discretionary ones, but the filing confirms Hsing's holdings have moved modestly lower heading into the quarter. The most recent earnings reaction offers context: the July print produced a 14% single-day gain and held an 8.8% advance over the following five days.
Wednesday's result will test whether MPWR's AI data centre momentum has stayed strong enough to justify a premium multiple after a month in which the stock has already given back a substantial portion of its year-to-date gains.
Against its peers
Shares moved -5.8% over the past week against a median of -2.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open MPWR on ORTEX →How this article was generated
- Generated
- 26 Oct 2026, 04:40
- Data as of
- 26 Oct 2026, 04:03
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.