
AIT Falls 10% in a Week While Peers Hold Steady
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
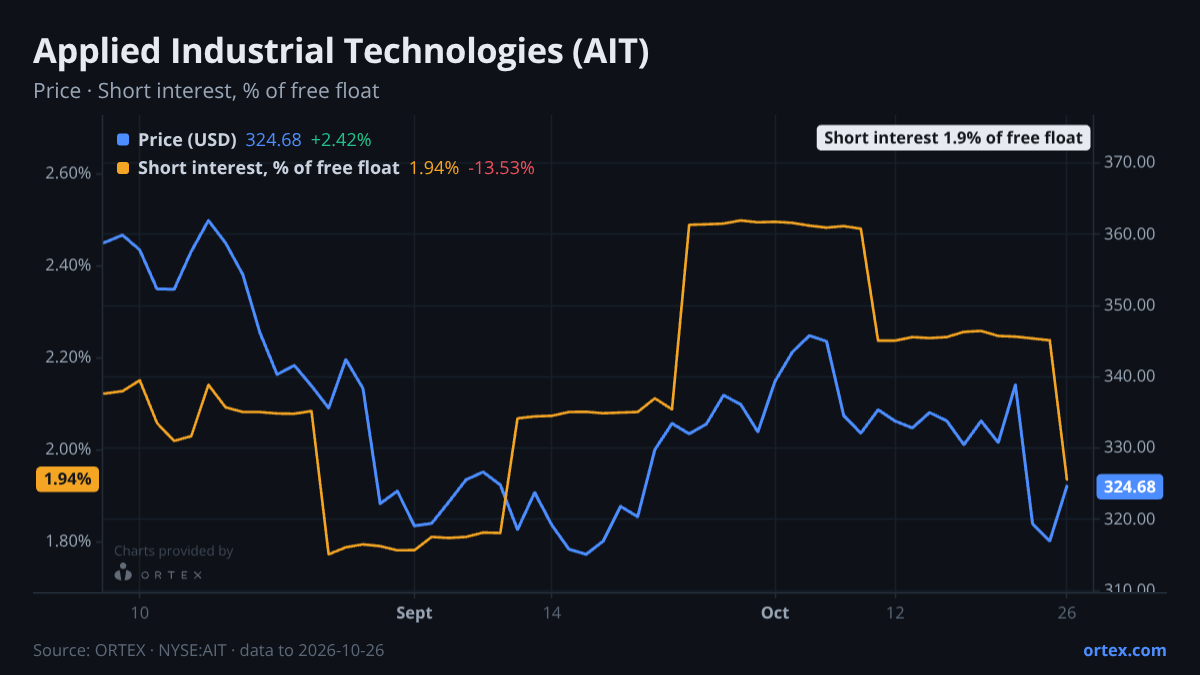
Applied Industrial Technologies, a bearings and industrial components distributor reporting fiscal Q1 results on October 29, has dropped 10% over the past week to $297.58, a move that stands in sharp contrast to most of its closest peers. WCC fell 3.6% over the same period. URI rose 9.5%. HRI gained 2.1%. AIT's decline is running roughly 2.1 standard deviations below its own typical weekly price move, making this week's selloff unusual by the company's own history, not just relative to the sector.
Options positioning has turned more defensive as the stock has fallen. The put/call ratio is at 2.60, above its 20-day average of 2.31 but off the 52-week peak of 2.84 reached on October 23. That peak marked the highest demand for downside protection in a year. The ratio has eased modestly since, with the z-score now at 0.67, roughly two-thirds of a standard deviation above normal. Since the previous preview published on October 24 noted the PCR at 2.84, the directional picture in options has not changed: protection demand remains elevated, it has simply come off the extreme. Short interest, at 1.9% of free float and falling 14% over the past week, offers no amplification to that caution. Shares available to borrow in the lending market run at more than 73 times current short positions, leaving no squeeze dynamic in play.
The debate among analysts centres on whether AIT's premium valuation can survive a tougher industrial demand environment. The bull case rests on last quarter's results: FY4Q EPS of $3.17 beat expectations by 9%, revenue rose 10.4% to $1.35 billion, and the company guided for $11.65 to $12.15 in adjusted EPS for FY27 with 4% to 6.5% sales growth. Double-digit order growth for a third straight quarter and $461 million of free cash flow in FY26 give the constructive camp a firm foundation. Analysts at Mizuho, BofA, Oppenheimer, DA Davidson, Keybanc and Baird all maintained positive ratings after the August print, lifting targets into the $390 to $420 range. The sole recent move since then came from Mizuho, which trimmed its target to $390 from $400 on October 15 while holding its Outperform rating. The bear case is simpler: at roughly 23 times trailing earnings, AIT trades well above its five-year average P/E of around 18.8 times, leaving little room for any softness in North American industrial production, tariff-related cost pressure, or a slowdown in its higher-margin Engineered Solutions segment.
Retail attention has picked up sharply around the selloff. Wikipedia views, tracked by the Wikimedia Foundation on a daily basis, are running at a z-score of 2.85 relative to the company's own 90-day history, the highest attention reading in the dataset. That is a measure of interest, not a revenue signal, but it confirms the selloff has drawn outside attention to the name.
The earnings report will test whether AIT's order momentum and margin resilience have held through a quarter in which the shares themselves have told a markedly different story from most of its industrial distribution peers.
Against its own history
This week's change in short interest is 2.1 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved -10.0% over the past week against a median of +1.8% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open AIT on ORTEX →How this article was generated
- Generated
- 28 Oct 2026, 04:03
- Data as of
- 28 Oct 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.