
Fastenal Shorts Rebuild at the Fastest Pace in a Year
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
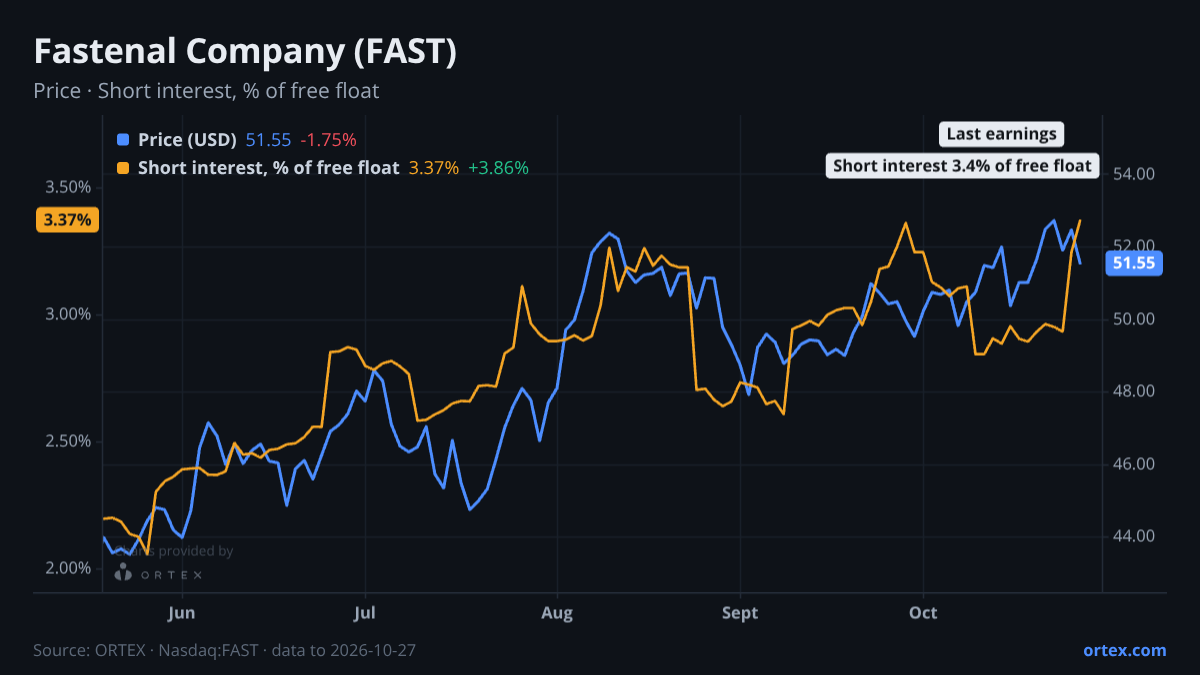
FAST is a fastener and industrial supply distributor with a $59 billion market cap, and it is drawing notably more short attention this week: short interest has jumped 16.5% in seven days to 38.6 million shares, the largest weekly increase in at least 12 months, putting the short position at 3.4% of the free float.
That move is worth pausing on. A 16.5% week-on-week rise is roughly 2.1 standard deviations above the stock's typical weekly short interest change over the past year. The position is also at its highest absolute level in the data window. The rebuild is striking partly because of what preceded it: ahead of the Q3 earnings release on October 14, shorts had been covering, and after the print (which saw the stock fall just over 2% on the day) the position sat at around 2.9% of the float. The move since then represents a deliberate re-entry, not a drift. Importantly, the borrow market is under no stress at all. Availability is exceptionally loose at 1,339%, meaning there are roughly 13 shares available for every one already borrowed. Cost to borrow is a negligible 0.43%, actually down 24% over the past month. The lending conditions offer no squeeze pressure whatsoever.
The options market, however, is telling a different story from the shorts, and that divergence is the clearest tension in the setup right now. The previous note on this name, published October 21, documented the PCR crashing to near its 52-week low of 0.34 in the days immediately after earnings. That extreme bullishness has partially faded. The ratio has climbed back to 0.44 from a low of 0.36 last week, still below its 20-day average of 0.58 and still call-heavy by historical standards, but the most aggressive call positioning is unwinding even as the shorts rebuild. The two signals are moving in opposite directions: options traders remain net positive on the name, while short sellers are adding exposure at an above-average rate.
The Street's view is divided, which gives both camps something to lean on. Argus Research raised its target to $59 last week, while Baird holds an Outperform with a $60 target. Against that, Bernstein maintained its Underperform even after lifting its target to $47, and Wolfe Research initiated at Underperform in September with a $51 target. The mean analyst target sits at $51.07, essentially flat with the current price of $51.55, which reflects a Street that has already priced in the bull case for Fastenal's Onsite and vending model without leaving much room for multiple expansion. The EV/EBITDA of 25.9x has compressed slightly over 30 days, and the stock's valuation factor ranks in the 17th percentile on an EV/EBIT basis, a signal that even some bulls acknowledge the shares are not cheap. The bear argument centres on gross margin pressure: the Q2 print showed gross margin at 44.6%, with price/cost still a negative 40 basis point drag, and large national account growth mixing the business toward lower-margin contracts.
One data point worth flagging: retail attention on FAST has spiked, with a Wikipedia views z-score of 2.0 against the stock's own 90-day history as of October 21. That is elevated interest, not a revenue indicator, but it sits alongside the short rebuild and the partial PCR reversal as a sign the stock is drawing more attention than usual for a mid-cycle industrial name.
Insider activity from August shows net selling of roughly $2.5 million over the 90-day window, mostly option exercises followed by open-market sales at prices around $51 to $52. None of the transactions were flagged as being under a 10b5-1 plan, but the values are modest relative to the market cap and the pattern is consistent with routine compensation-related selling rather than a conviction view. JP Morgan Asset Management added nearly 9 million shares in the September quarter, by some distance the largest institutional flow in the top-holder table. BlackRock and State Street also added incrementally.
With the next earnings event not until January 19, the near-term question is whether the short rebuild continues at this pace or stabilises now that the post-earnings re-entry trade is largely done. The stock is down fractionally on the week while close peer URI gained 11.3% and FERG added 1.1%, a relative underperformance that may itself be part of what is attracting fresh short interest. Whether that gap narrows or widens into year-end is what the positioning data will reflect over the coming weeks.
Against its own history
This week's change in short interest is 2.1 standard deviations above the company's typical weekly move over the past year. Short interest is at its highest level in at least a year.
Against its peers
Shares moved -0.2% over the past week against a median of +1.5% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open FAST on ORTEX →How this article was generated
- Generated
- 28 Oct 2026, 18:16
- Data as of
- 28 Oct 2026, 18:15
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.