
Avantor Options Turn Defensive as Shorts Hit Record Low
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
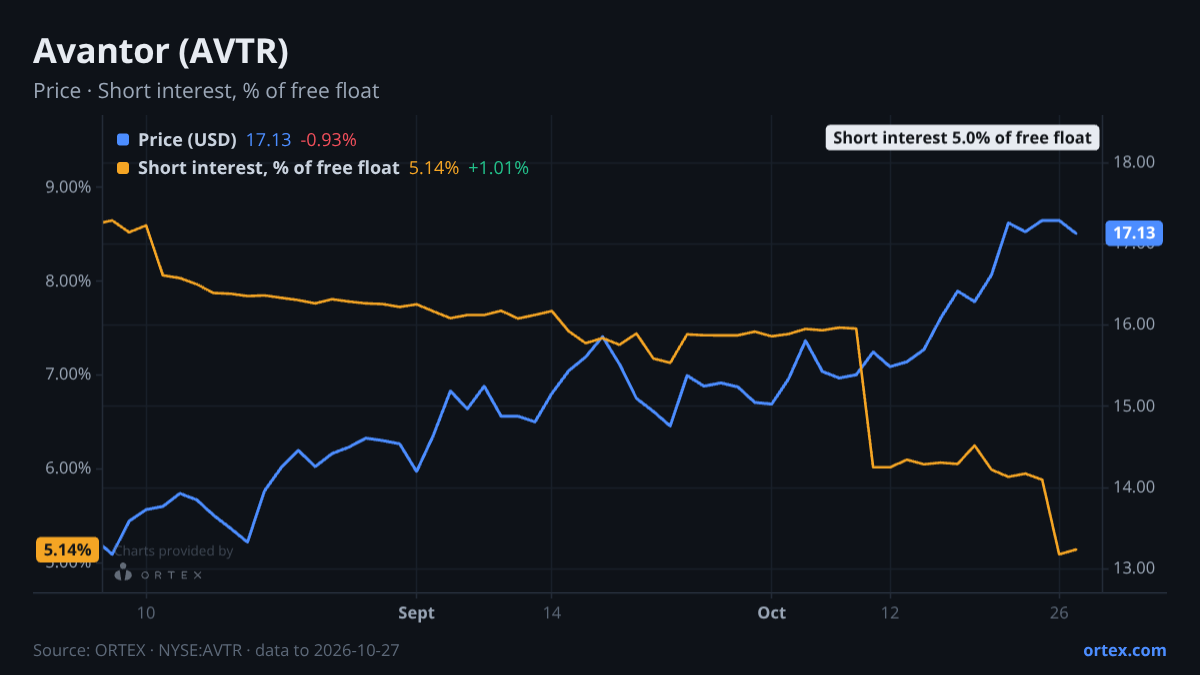
AVTR reports Q3 results on October 30, arriving with short positions at their lowest level in the observed dataset and options traders suddenly buying more protection than at any point in months.
The options shift is the sharpest development of the past 24 hours. The put/call ratio jumped to 0.70 on October 28, nearly three times the prior week's reading and more than two standard deviations above its 20-day average of 0.24. That is the most defensive options posture recorded in recent months for a stock where call buying had dominated. The move came on the same day the share price fell 2.6% to $16.69, extending a weekly loss of 3.3% that puts Avantor behind every close peer in the group. TMO gained 1.5% on the week, WAT rose 4.2%, MEDP added 4.6%, and CRL gained 8.4%. Avantor's underperformance is about 4.5 percentage points behind the peer median over that stretch.
The short interest picture reads very differently. Positions have dropped to roughly 33.8 million shares, or about 5% of free float, down 18% on the week and 31% over the past month. That is the most aggressive pace of short-covering in the observed history, continuing the unwind that previous notes tracked from roughly 49 million shares in early October. Borrow conditions reinforce the message: availability is above 4,600%, meaning shares available to lend are roughly 46 times the existing short position, and the cost to borrow is 0.36%. There is no mechanical pressure pushing shorts out. The covering appears to reflect a genuine change in view rather than a squeeze.
The debate among analysts captures the same tension. The bull case rests on Avantor's Revival programme showing real operational traction: VWR returned to positive organic growth at 1.7%, better than expected, while BMP posted a smaller-than-feared decline alongside double-digit order growth and a 1.1x book-to-bill. Management raised FY26 organic revenue guidance to a range centred on flat and reaffirmed $500 million to $550 million in free cash flow. The bear case is structural. Bears argue organic growth is likely to lag peers by three to four percentage points annually through 2028, that demand normalisation in lab supply has repeatedly disappointed, and that free cash flow guidance looks stretched after only $39 million in Q1. Morgan Stanley raised its target to $15 in mid-October while holding an Equal-Weight rating. TD Cowen lifted its target to $17 on the same day, also maintaining Hold. The Street's consensus target of roughly $16 sits close to the current price, leaving little implied upside and keeping ratings clustered in neutral territory.
Dodge & Cox remains the dominant holder with roughly 17.7% of shares, having added to its position in the latest reported quarter. BlackRock and Dimensional also added shares. No 13D activist is on the register, and recent insider activity consists entirely of tax-withholding transactions rather than open-market trades, offering no directional signal.
Tomorrow's print will test whether Avantor's operational recovery is progressing fast enough to close the growth gap with peers, and whether the margin trajectory can support a valuation that the Street is treating as already roughly fair.
Against its own history
This week's change in short interest is 1.8 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved -3.3% over the past week against a median of +1.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open AVTR on ORTEX →How this article was generated
- Generated
- 29 Oct 2026, 04:22
- Data as of
- 29 Oct 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.