
NEXA Short Interest Doubles on Eve of Q3 Results
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
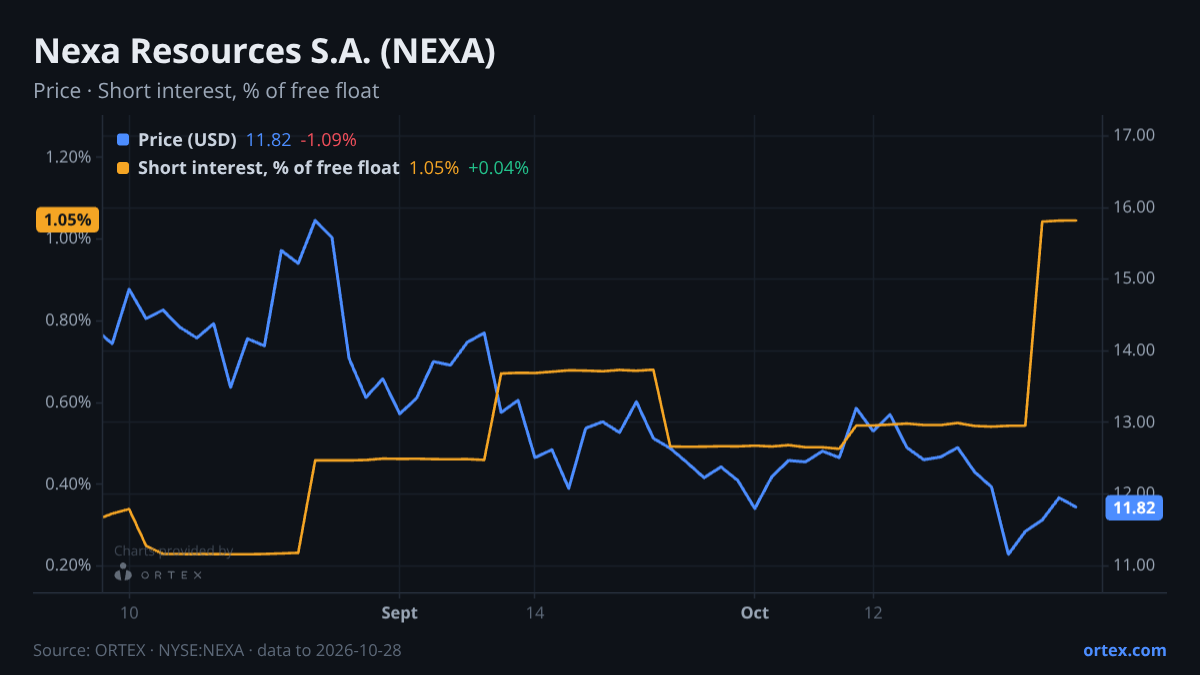
Nexa Resources, the Luxembourg-registered zinc and copper miner operating primarily in Brazil and Peru, reports third-quarter results today, and the lending market is flashing a signal worth noting. Short interest nearly doubled in a single week, jumping 93% between October 22 and October 26 to roughly 489,000 shares, the highest level recorded in at least a year. That move is 2.6 standard deviations above Nexa's typical weekly shift, making it an outlier even for a stock that has seen its short position drift higher through October. Despite that, availability in the lending pool remains extraordinarily loose at 4,218%, meaning lenders have far more shares available than are currently borrowed. Borrowing costs are also minimal at 0.54%, down 13% over the past month. The short position is large in momentum terms, not in structural terms.
The stock itself has pulled in the other direction. NEXA gained 7.5% over the past week to close at $12.00, a performance that stands out against a peer group that moved down a median of 2.4% over the same period. Correlated names like SCCO and FCX both declined. That divergence, shorts doubling while the share price climbs, sets up a tension the quarterly numbers will resolve one way or the other.
The analyst picture is cautious but not hostile. Targets across the coverage universe sit above the current price, with the consensus mean at $14.04, implying roughly 17% potential return from yesterday's close. BofA Securities carries an Underperform rating with a $14 target, while JP Morgan and Scotiabank hold neutral-equivalent stances. Morgan Stanley's $12.50 Equal-Weight target sits closest to where the stock is trading. The key disagreement is over the trajectory of free cash flow and leverage. The bull case rests on operational progress at the Aripuanã zinc mine in Brazil and a path toward $248 million in free cash flow by 2027, with the smelting segment running cash costs of just $0.11 per pound. The bear case points to an EPS miss in the most recent quarter, a net debt-to-EBITDA ratio that has been hovering above 2x, and downward revisions to EBITDA estimates through 2027.
One piece of independent data adds texture. Brazil's Agência Nacional de Mineração (ANM) recorded the largest June on record for CFEM zinc royalties, at 1.73 million reais, since the series began in 2022. Copper royalties for the same month ran 160% above June a year earlier. Neither dataset has been measured as a lead indicator for Nexa's reported figures, so no direct inference about the print is warranted. But the royalty data, which reflects actual extraction volumes across Brazilian mining operations, confirms that June-quarter activity in the country's zinc and copper sector was running at historically elevated levels.
Options traders are leaning toward calls rather than puts. The put/call ratio of 0.40 is more than one standard deviation below its 20-day average, the most call-heavy positioning of the past year. That matches the recent price strength and contrasts sharply with the jump in short interest, leaving the Q3 report to decide which signal was reading the situation correctly.
Against its own history
This week's change in short interest is 2.6 standard deviations above the company's typical weekly move over the past year. Short interest is at its highest level in at least a year.
Against its peers
Shares moved +7.5% over the past week against a median of -2.4% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open NEXA on ORTEX →How this article was generated
- Generated
- 30 Oct 2026, 04:35
- Data as of
- 30 Oct 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.