
Coherent Bounces Hard but Earnings Loom Five Days Out
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
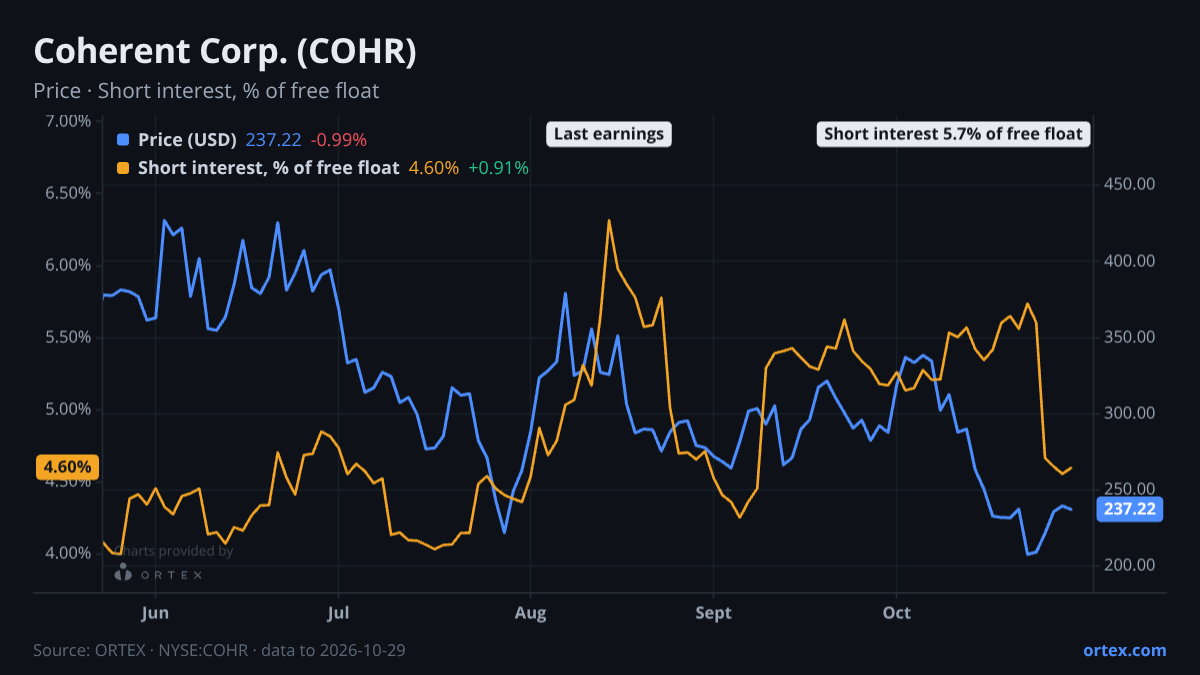
Coherent Corp. has staged a sharp reversal: up 14% on the week to $237.22, recovering roughly half the ground lost in last week's 20% collapse, with fiscal Q1 results due in five days.
The bounce comes with an unmistakable shift in short positioning. Short interest dropped 17% over the week to 5.7% of free float, from a recent high above 11 million shares to just over 9 million. That is a fast unwind. The borrow market confirms the easing: cost to borrow fell nearly 20% on the week to 0.37%, a low level by any measure. Availability has opened up dramatically, rising 74% on the week to 3,025%, meaning the lending pool is far from stressed. The ORTEX short score has also stepped down, from around 38.4 on October 20 to 35.1 now, pointing to reduced short-side pressure overall. Short sellers who built into the selloff appear to have taken profits into the bounce.
Options tell a different story, and it is worth naming the contrast. The put/call ratio is 1.50, right in line with its 20-day average of 1.50. That near-zero z-score says options traders are not adding fresh hedges into earnings, but the PCR itself remains elevated in an absolute sense. At 1.50 it is well above the 52-week low of 0.52 and not far off the 52-week high of 1.72. Structurally, this is a stock where puts consistently dominate calls. The absence of a spike this week likely reflects short covering removing the most urgent demand for downside protection, rather than a genuine shift in sentiment.
The Street is actively repricing ahead of November 4. Two more target cuts arrived this week. B. Riley's analyst lowered his target this morning from $297 to $262, keeping a Neutral. Needham's analyst trimmed from $420 to $380 on Monday, holding Buy. StoneX initiated with a Buy at $425 last week, providing a partial offset. The mean analyst target is $394, implying roughly 66% return potential from current levels, a gap that reflects genuine disagreement rather than consensus conviction. The bull case rests on Coherent's indium-phosphide expansion as the key bottleneck-breaker for AI data centre interconnects, with management targeting a doubling of internal InP capacity by the September quarter and further doubling by end of 2027. The bear case is harder to ignore ahead of a print: FY26 operating cash flow of $79.5 million against $1.1 billion of capex and negative free cash flow of $1 billion, inventory up 79.5% to $2.6 billion, and $11.8 billion of future vendor commitments. The analyst recommendation differential ranks in the 98th percentile of all stocks, meaning the gap between the most bullish and most bearish views is unusually wide. That divergence is the setup, not a consensus.
There is an activist on the register worth noting. BCPE Watson (DE) BML, LP holds a Schedule 13D position, the last disclosed stake being 5.2% of the class, and has filed five times since November 2025, most recently in February 2026. A Schedule 13D signals active rather than passive intent. The standard caveat applies: stakes are as last disclosed around the 5% threshold, and the holder may have moved below that level without further filing. On the institutional side, BlackRock added 1.66 million shares through September and Capital Research and Management initiated a position of 3.68 million shares, also through September. T. Rowe Price added 1.54 million shares in the same period. The inflows from large institutions contrast with the insider register, which shows net selling of roughly $8.2 million over the past 90 days, almost entirely through tax-withholding transactions (transaction code F) rather than discretionary open-market sales. The CFO's 18,284-share withholding on October 12 accounts for the bulk of that figure. Compensation mechanics rather than conviction selling.
Peers diverged on the week. TTM Technologies led the cohort with a 19% gain. Fabrinet added 10% before giving back 5% on Thursday. Corning and Keysight rose 4% to 6%. PLXS was the outlier, down 2% on the week and falling another 10% Thursday. Coherent outpaced most of the group, consistent with the short-covering dynamic amplifying the rebound rather than fundamental leadership.
The earnings history adds relevant texture without pointing to an obvious pattern: the August 2026 print moved the stock up 7% on the day but down 11.5% over the following five sessions, suggesting initial relief followed by a reassessment. The next print arrives November 4. The key questions will be whether cash flow progress and InP capacity ramp can shift the bear argument on working capital, and whether the analysts still holding large targets find reason to revisit their numbers after the call.
Against its peers
Shares moved +14.1% over the past week against a median of +5.3% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open COHR on ORTEX →How this article was generated
- Generated
- 30 Oct 2026, 17:31
- Data as of
- 30 Oct 2026, 17:20
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.