
Citigroup Joins JP Morgan in Backing SKYD Ahead of Earnings
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
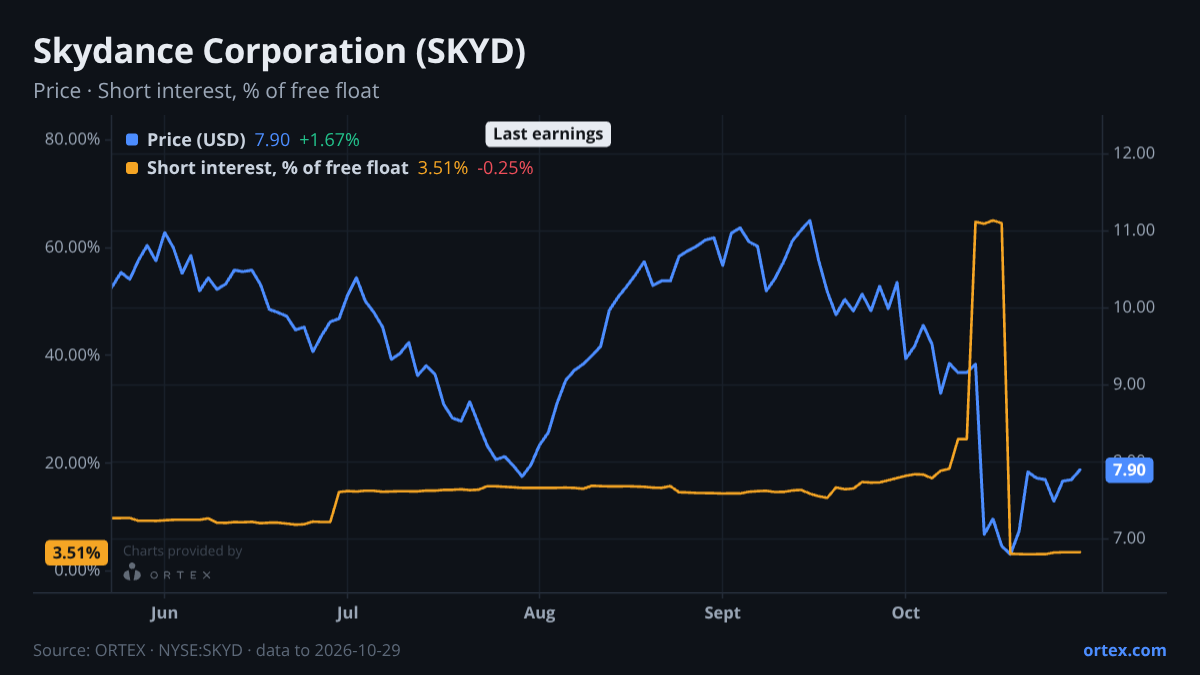
SKYD heads into its November 4 earnings print with short sellers still building positions, options traders turning more bullish, and two of the biggest names on Wall Street shifting constructively in the same week.
The most notable development since the last note is Citigroup's reinstatement of coverage with a Buy rating and a $10 target on October 26. That follows JP Morgan's upgrade to Neutral with a $9 target on October 23, previously covered here. Together they represent the first positive analyst momentum after weeks of cuts. Bernstein still sits at Underperform with a $6 target, and Barclays keeps its Underweight at $7. But the direction of travel has shifted. The panel mean is $8.87 against a current price of $7.95, implying roughly 12% upside if the consensus holds. The bull case is straightforward: $6 billion-plus in cost synergies, DTC now profitable at $251 million adjusted EBITDA, and Studios EBITDA that doubled last quarter. The bear case is equally clear: $79 billion of pro forma net debt, a synergy delivery schedule that leaves no room for execution slippage, and affiliate revenue in structural decline.
Short interest has kept climbing despite the partial stock recovery. Shorts grew 12% over the past week to approximately 144.6 million shares, and have risen 76% over the past month. That is a meaningful and sustained build. FINRA's most recent fortnightly figure puts short shares at 145.9 million with a days-to-cover reading of 3.53. The borrow market has eased somewhat from its mid-October tightness: availability has loosened to 33.6%, back from the 52-week low of 19.4% hit on October 15. Cost to borrow has also pulled back, running near 1.88% after touching 3.37% earlier in the month. The short score is a further confirmation: it reads 60.4, placing SKYD in the 11th percentile of the universe on short score rank, meaning shorts are more committed here than on nearly 90% of comparable names. The setup is a stock where institutional shorts are rebuilding even as two major banks turn constructive, a genuine tug-of-war into the print.
Options positioning has shifted sharply toward the bullish side. The put/call ratio has dropped to 0.52, well below its 20-day average of 0.68. A month ago it was running above 1.23. That reversal points to a significant rotation from downside hedging toward call buying, consistent with traders positioning for an upside surprise on November 4 rather than protecting against further losses. The 52-week range for the PCR runs from 0 to 1.58, so the current reading sits toward the more optimistic end of the spectrum.
Ownership tells its own story about how the stock came to exist in its current form. Redbird Capital's Gerald Cardinale received a grant of 333 million shares on October 6, making Redbird the largest disclosed holder at 8.7% of shares. David Ellison holds 6.7%. Laurene Powell Jobs received a grant of 20.8 million shares on the same day. These are equity grants tied to the merger mechanics, not open-market conviction buys, and the stock is now trading well below the $12 grant price. The CFO, Dennis Cinelli, exercised and immediately sold 95,401 shares on October 15 at $7.26, a routine but not encouraging action from a standing-start insider. Wikipedia attention has spiked sharply, with the Wikimedia/ORTEX page-view composite running at a z-score of 3.8, pointing to a notable increase in retail interest around the earnings date.
The prior two quarters both produced positive one-day and five-day moves after results: the August print saw the stock gain 6.6% on day one and 14.1% over five days. The stock has fallen 20% over the past month and is down around 47% year-to-date, so the base into which any earnings reaction lands is already depressed. Whether the November 4 print sharpens or resolves the standoff between a growing short book and two newly constructive major banks is the most important question for the week ahead.
Against its own history
Short interest is at its highest level in at least a year.
Against its peers
Shares moved +2.3% over the past week against a median of -1.0% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open SKYD on ORTEX →How this article was generated
- Generated
- 31 Oct 2026, 17:30
- Data as of
- 31 Oct 2026, 17:30
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.