
CVS Health: Short Sellers Exit Ahead of Wednesday Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
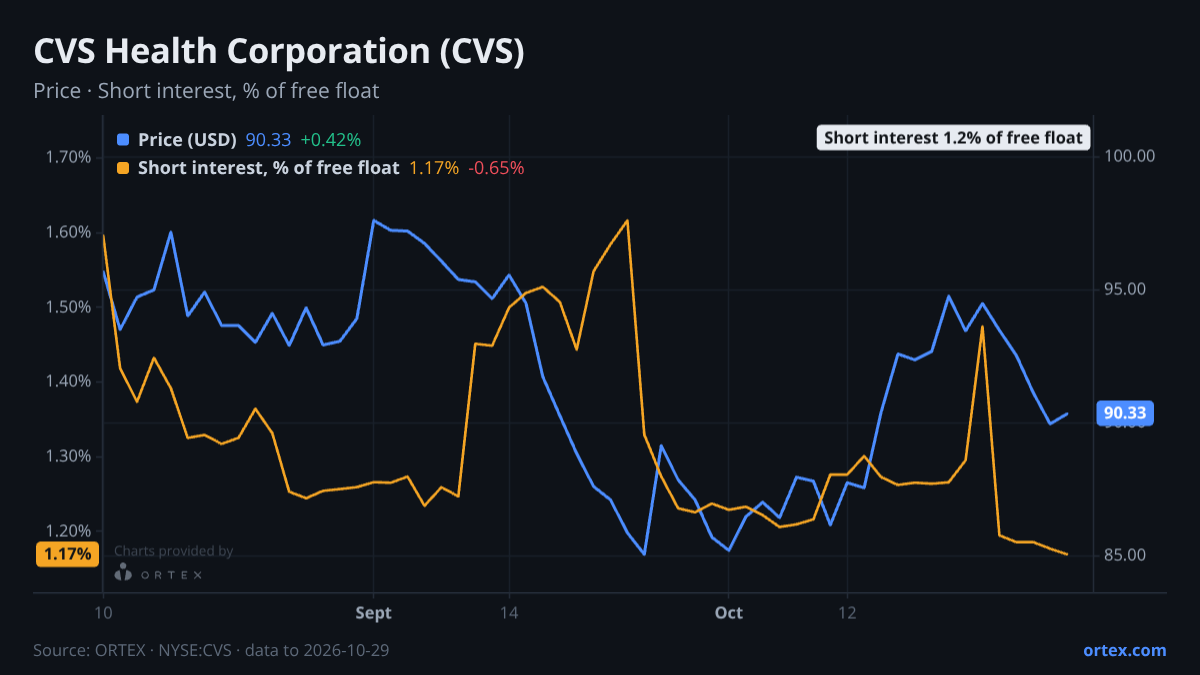
CVS Health Corporation reports Q3 results on Wednesday with short sellers in full retreat, yet the options market is sitting closer to its most defensive posture of the past year.
Short interest has fallen 28% over the past month to 1.2% of the free float, the lowest level in at least a year. That weekly decline of nearly 10% is more than two standard deviations below the typical weekly move, an unusually sharp exit. The borrow market reflects the same picture: availability is essentially unlimited, with more than a billion shares available to lend and cost to borrow still below 1%, despite a sharp one-week jump to 0.70% from 0.09%. The cost-to-borrow spike looks like a data artefact rather than a tightening signal given how abundant the lending pool remains. There is nothing in the positioning data to suggest organised bearish conviction ahead of this print.
The options market offers a mild counterpoint. The put/call ratio, at 0.94, is running above its 20-day average of 0.91 and close to the 52-week high of 0.97. The z-score of 0.74 is modest, meaning this is cautious rather than alarmed. What it does show is that investors are paying slightly more than usual for downside protection into Wednesday, even as short sellers have been reducing exposure. The stock itself fell 3.4% over the past week against a median decline of around 2.5% for its closest peers. UNH dropped 2.7%, CI fell 2.8%, and CNC lost 2.5%, so CVS's underperformance was real but not dramatic.
The analyst community remains constructive in aggregate, with a mean price target of $115.48 against the current price of $90.25, implying meaningful upside, though the most recent target change available in the data came from Leerink Partners in mid-October, which trimmed its target to $112 while holding its Outperform rating. The debate is a familiar one for integrated healthcare companies. The bull case rests on CVS's scale across pharmacy, PBM, and insurance, plus margin recovery in Healthcare Benefits and the care-delivery optionality of Oak Street. The bear case points to three-way headwinds: PBM pressure from competition and 340B scrutiny, elevated medical benefit ratios in Medicare Advantage, and persistent pharmacy reimbursement compression. With 2028 EPS guidance already trimmed to $9.71, the bar for restoring confidence is specific rather than directional.
The last quarterly print, in August, produced a one-day decline of nearly 8% and a five-day loss of over 9%. Wednesday's result will test whether the restructuring of Healthcare Benefits margins has progressed enough to change that pattern, or whether elevated utilization continues to set the tone.
Against its own history
This week's change in short interest is 2.2 standard deviations below the company's typical weekly move over the past year. Short interest is at its lowest level in at least a year.
Against its peers
Shares moved -3.4% over the past week against a median of -2.5% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open CVS on ORTEX →How this article was generated
- Generated
- 1 Nov 2026, 04:08
- Data as of
- 1 Nov 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.