
Cummins Analysts Slash Targets Ahead of Q3 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
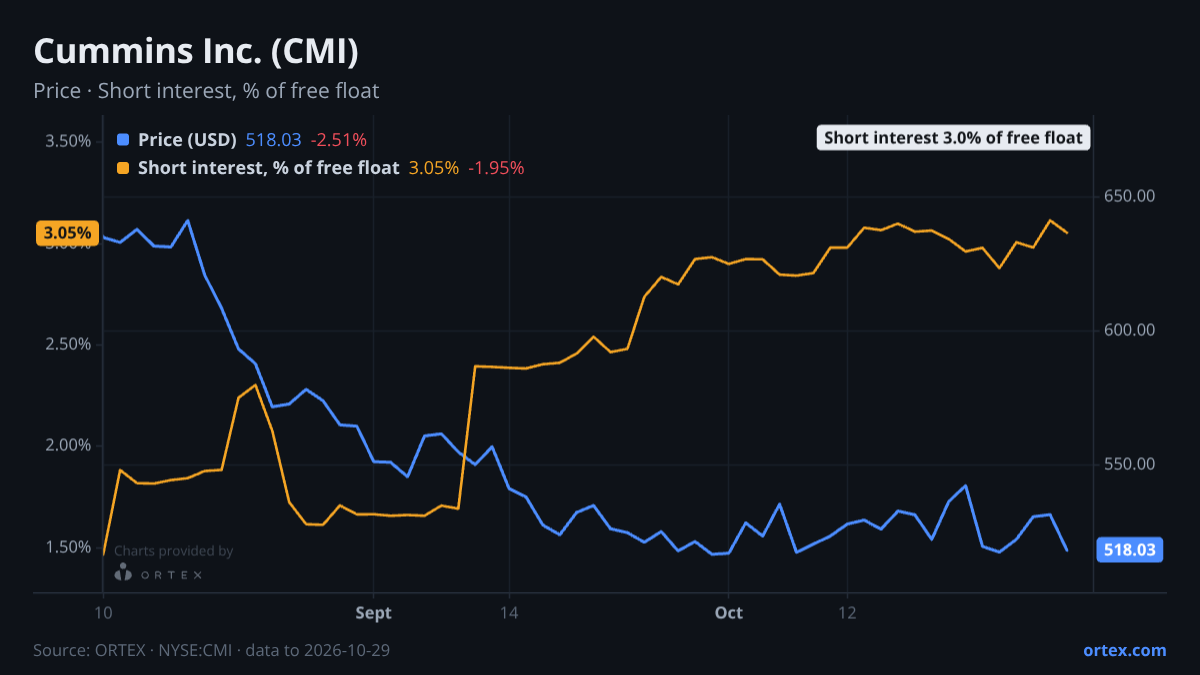
CMI reports Q3 results on November 4, trading at $500.09 after sliding 3.3% over the past week, a move that looks notably soft against a median gain of 0.7% for its closest industrial peers.
The most striking feature of the pre-earnings setup is the breadth and speed of analyst target cuts. Seven firms have trimmed their price targets since late September, with Wells Fargo cutting twice in the same month, moving its target from $874 down to $760 in early October, then to $608 last week, while holding an Overweight rating throughout. Barclays and Citi followed with similar moves, dropping to $675 and $630 respectively from prior targets above $750. JP Morgan, which holds a more cautious Neutral, cut to $600. The consensus mean now sits at roughly $709, still well above the current share price, but the trajectory of the revisions tells a clearer story than the absolute level: the Street is becoming more selective about what Cummins can deliver, and how soon.
The underlying debate splits along a familiar line for industrial names caught between growth pockets and structural headwinds. Power Systems has been the standout, with an 18% revenue jump last quarter and raised full-year guidance pointing to $34.7 billion to $36.4 billion in sales. Power generation demand, particularly in North America, has given management enough conviction to lift the top-line outlook. Against that, the bear argument centres on margin pressure: gross margins contracted 120 basis points year-on-year to 22.9%, hit by weaker North American truck volumes and tariff costs, while the China heavy-truck market has continued to deteriorate. The combination of a shrinking addressable market in key commercial vehicle segments and ongoing tariff drag is what the target cuts are really pricing in, not a collapse in the business, but a lower ceiling on near-term earnings power. Forward earnings revisions are still moving in a positive direction, with the 12-month forward EPS growth rank sitting in the 90th percentile of the universe, though the PE multiple has compressed about 1.1 points over the past 30 days as the stock has de-rated.
Short interest and borrowing conditions offer little signal in either direction. Short interest is running at 3% of the free float, up roughly 23% over the past month in share terms, but borrow availability remains exceptionally loose. Availability is near 9,250% of current short interest, meaning the lending pool is barely touched, and cost to borrow has fallen 40% over the past week to 0.35%. The options market is equally calm: the put/call ratio of 0.83 is barely above its 20-day average of 0.82, well within one standard deviation of normal. Nothing in the positioning data suggests traders are bracing for a sharp move in either direction. Wikipedia traffic for CMI is running at an elevated z-score of 2.7 against its own 90-day history, which reflects a spike in retail attention around a name that doesn't normally attract it, likely tied to the tariff and industrial-demand headlines that have driven the analyst activity.
The November 4 print will test whether Power Systems momentum is durable enough to offset continued softness in truck engines and international markets, at a valuation where the stock trades at roughly 14.7 times earnings with the Street still cutting numbers.
Against its peers
Shares moved -3.3% over the past week against a median of +0.7% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open CMI on ORTEX →How this article was generated
- Generated
- 1 Nov 2026, 04:09
- Data as of
- 1 Nov 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.